What Your Monthly Payment Actually Looks Like
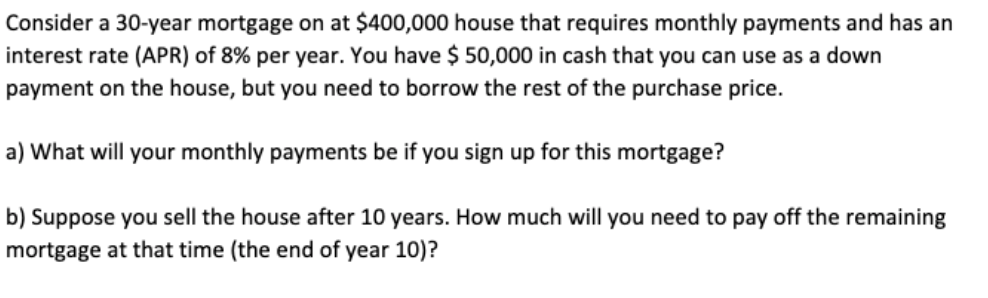
The base principal and interest on a $400,000 loan at 7% over 30 years comes out to roughly $2,661 per month. That number is easy enough to find on any calculator site, but it is only half the conversation. The real payment your lender collects includes taxes, insurance, and potentially HOA dues or PMI. If you are budgeting around that $2,661 figure without accounting for the rest, you are going to be surprised when the first bill hits. I ran into this exact issue with a client back in 2019. She had scoped out homes based purely on the principal and interest number from an online calculator. When we got to closing, her actual monthly payment was nearly $400 higher once escrow items were folded in. We had to revisit her qualification and she ended up dropping one price tier. It was a rough few weeks. The workaround now is simple: I always run the full payment through the lender's disclosure spreadsheet before we even look at listings seriously.
Mortgage Payment On 400 000 For 30 Years
Here is the breakdown if you want to see how the pieces fit together. The standard amortization formula is M = P * [r(1+r)^n] / [(1+r)^n - 1]. P is your loan amount, r is your monthly interest rate (annual rate divided by 12), and n is the total number of payments, which is 360 for a 30-year loan. Plug in 7% and you get that ~$2,661 figure. Different rates shift the number dramatically. At 6% the payment drops to about $2,398. At 8% it climbs to roughly $2,934. The difference between those two rates on a $400,000 loan is over $500 a month, which adds up to $180,000 in extra interest paid over the life of the loan. That is not a rounding error. That is a meaningful chunk of money that disappears because of a single percentage point.
How To Calculate This Yourself
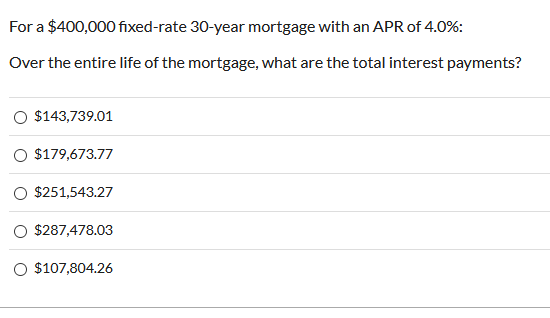
You do not need a paid tool for this. Excel handles it fine. The PMT function is what most people reach for. The syntax is =PMT(rate, nper, pv). For our example you would type =PMT(0.07/12, 360, 400000) and Excel returns a negative number because it treats it as an outflow. If you want a positive display value, wrap it in a NEG function or add a minus sign in front. The result should land right around 2661.26. If you prefer a standalone calculator, Google has a built-in mortgage calculator you can access by searching "mortgage calculator" directly in the search bar. It does not require a download. Just type in the loan amount, interest rate, and term length and it spits out the monthly figure instantly. It also shows you the total interest paid, which is useful for seeing the full cost picture. For people who want something they can keep on their phone or share with a spouse, I recommend the mortgage calculators built into the major bank apps. Chase, Wells Fargo, and Bank of America all have them free. They are no different from the web versions in terms of accuracy, but having one saved in your banking app means you are not hunting for a URL every time you want to run a quick number.
Get the Full Details
Things Most People Miss
PMI is the big hidden one. If your down payment is less than 20%, you will likely be paying private mortgage insurance on top of everything else. On a $400,000 loan with a 5% down payment, that could add another $150 to $200 a month depending on your credit score and the exact loan program. The good news is PMI automatically drops off at 78% loan-to-value by law, and you can request cancellation at 80%. The bad news is nobody reminds you of this unless you ask. Another thing that sneaks up on people is the difference between the note rate and the APR. Lenders will advertise a rate like 6.75% but the APR might show 7.12%. The APR includes closing costs and fees rolled into the calculation. It is a more honest reflection of what the loan actually costs you, but it is easy to miss if you are only comparing the headline rate. There is also the matter of payment scaling. Your first payment might go almost entirely toward interest. In the early years of a 30-year loan, a huge portion of each payment is interest, not principal. I remember looking at a statement for a friend of mine who had been paying for three years and realized he had only chipped away maybe $15,000 of his $350,000 balance. That is normal amortization, but it is startling if you do not expect it.
When The Standard Approach Breaks Down
Online calculators assume a straightforward conventional loan with perfect credit and a standard down payment. They do not account for jumbo loan thresholds, adjustable-rate resets, or state-specific transfer taxes. If you are in a high-tax state like New Jersey or Connecticut, property taxes alone can push your monthly payment well above what a basic calculator shows. I had a borrower in Newark whose principal and interest was around $2,100 on a $500,000 loan, but property taxes added another $700 a month. The calculator would have told him the payment was $2,100. The real payment was $2,800. Another scenario where manual calculations fall apart is when you have points. Buying down your rate with discount points changes the math in a way most free calculators do not handle well. You need to factor in the upfront cost of those points against the monthly savings they generate. It is a break-even analysis, not just a payment calculation. I usually build a simple spreadsheet for this that compares the total cost at two different rate options over however many years the borrower plans to stay in the home.
A Few Practical Notes
If you are looking to lock in a rate soon, get pre-approved before you start house hunting. It takes about 24 to 48 hours, gives you a clearer picture of what you can afford, and makes your offer look stronger to sellers. A pre-approval is not a commitment from the lender, but it signals that you have the financial backing to close. Also keep in mind that making extra principal payments early in the loan can shave years off the term and save you tens of thousands in interest. One extra payment per year, or even rounding up your monthly payment to the nearest hundred, makes a noticeable dent. The savings are most impactful in the first five to seven years when the interest portion of your payment is still dominant.