What mortgage planning actually looks like before you apply
Most people start thinking about mortgage planning when they've already found a house they want to buy. By then, the leverage window is already closing. I spent years processing loan files for regional lenders, and the difference between a clean close and a three-week delay usually comes down to whether someone did the math backward from their target payment instead of forward from their qualifying income. Here's how the process actually works when you're not doing it for the first time. Your debt-to-income ratio, or DTI, is calculated two ways. The front-end ratio looks at housing costs against gross monthly income. The back-end ratio includes every minimum monthly debt obligation you have. Lenders typically cap the back-end at 43 percent for conventional loans, though some programs stretch to 50 percent under certain conditions. I once had a borrower who was approved on paper for a $420,000 loan at 6.75 percent. Her DTI sat just under 43 percent when we pulled her credit report. Two days before closing, her auto loan lender refinanced her car payment from $380 to $510 without telling her, pushing her DTI to 45.2 percent. We had to pull a second appraisal, re-underwrite, and she lost the seller's earnest money deposit. That's why Mortgage Planning isn't about finding what you can borrow. It's about freezing your debt profile thirty days before you apply and keeping it frozen until after funding. Start with your gross monthly income. Take that number and multiply it by 0.43, then divide by your projected housing payment ratio. This gives you a target home price that won't make your lender nervous. Work backward from there using current rates and add property taxes, homeowners insurance, and HOA fees into the calculation. Don't use a online calculator alone. Those tools default to 28 percent front-end ratios and often exclude HOA, PMIs, or flood zone requirements that will show up later and wreck your approval.
I use a simple spreadsheet I built over about eight years of processing. It takes income, outstanding debts, projected down payment, and estimated rates, then outputs both front-end and back-end DTI at three different interest rate scenarios. The column that matters most is the rate sensitivity row. It shows how much your DTI changes per quarter-point shift in the rate, which tells you whether a rate buydown is worth the upfront cost or whether locking immediately makes more sense. Most people I work with don't realize that paying two points to drop half a percent doesn't improve their qualification. It improves their payment. Those are two different numbers, and lenders evaluate them separately.
Self-employed income documentation
If you're self-employed, the conventional approach averages your last two years of Schedule C or corporate tax returns and applies a 25 percent buffer for expenses. This means a business showing $120,000 in net profit on your taxes might qualify based on roughly $90,000 annually, or $7,500 per month. But here's the thing nobody explains upfront: if you deducted a large vehicle purchase, equipment expense, or retirement contribution in the most recent tax year, that deduction stays on the return even if you took the expense for tax purposes only. The underwriter will add it back as a non-recurring expense and recalculate your qualifying income downward. I had a client who ran a small landscaping company. His two-year average net profit was around $145,000, which should have qualified him comfortably for a conventional loan. In year two, he bought a $42,000 truck and depreciated it using Section 179. The underwriter added back the full depreciation and cut his qualifying income by roughly $18,000 annually. We solved it by pulling his year-one tax return, which didn't have the depreciation, and averaging those figures instead since the truck wasn't present in the first year. The loan closed fourteen days later. Without that workaround, it would have been denied on documentation grounds.
Get the Full Details

Miscellaneous assets and reserve requirements
Lenders require reserves depending on the loan type and your risk profile. Conventional loans typically ask for two to six months of PITIA reserves, meaning principal, interest, taxes, insurance, and HOA dues. Some jumbo programs demand up to twelve months. The reserves must come from verifiable assets, and that's where people make mistakes. They'll show a $50,000 savings account, but half of that came from a recent wire transfer from a relative. Gifts are allowed for down payments, but reserves usually need to be seasoned for at least two months of bank statements. A large deposit sitting in an account for three weeks gets sourced aggressively. I've seen borrowers use 401(k) loans as reserves. This generally doesn't count. Lenders prefer liquidity that they can trace and verify. Credit union accounts sometimes cause issues because the underwriter can't electronically verify the balance through third-party platforms. A phone call to the credit union can add five days to processing. It sounds minor, but in a competitive market where closings are scheduled back-to-back, five days can break a transaction.
Common counter-intuitive truths
One thing people rarely understand is that paying off a small credit card balance before applying does not always help. If the card has a zero balance but was carrying a balance during the most recent statement cycle, paying it off reduces your reported utilization, which helps your credit score slightly. But if you close the account entirely, you lose that credit line, which can actually lower your score by reducing your total available credit. The score impact is usually in the range of ten to twenty points, sometimes more depending on your existing credit mix. Another overlooked detail is the effect of co-signed loans on your DTI. If you co-sign a car loan for your sibling, the entire payment counts against you, not just your portion. Lenders don't prorate co-signed obligations. This has knocked out multiple otherwise qualified buyers, including a contractor I worked with who co-signed a loan for his daughter years earlier and forgot about it until his credit report updated with the current balance.
Practical timeline and what to do first
If you're thinking about buying within the next six months, start by pulling your full credit reports from all three bureaus. Check for accuracy errors, outdated collections, or accounts that should be paid but weren't reflected correctly. Dispute anything that's wrong. Credit repair takes sixty to ninety days typically. Use that time to stabilize your employment situation, pay down revolving balances to under 30 percent utilization, and avoid any new credit inquiries. Each hard pull from a lender application drops your score a few points, and multiple inquiries in a short window compound the damage. Get pre-approved, not pre-qualified. Pre-approval means the lender has reviewed your documents, pulled your credit, and issued a conditional commitment. Pre-qualification is a rough estimate based on what you told them verbally. Sellers treat these completely differently, and so do underwriters. A strong pre-approval letter from a reputable lender carries real weight in an offer, while a pre-qualification letter is usually ignored entirely.
Where Mortgage Planning breaks down
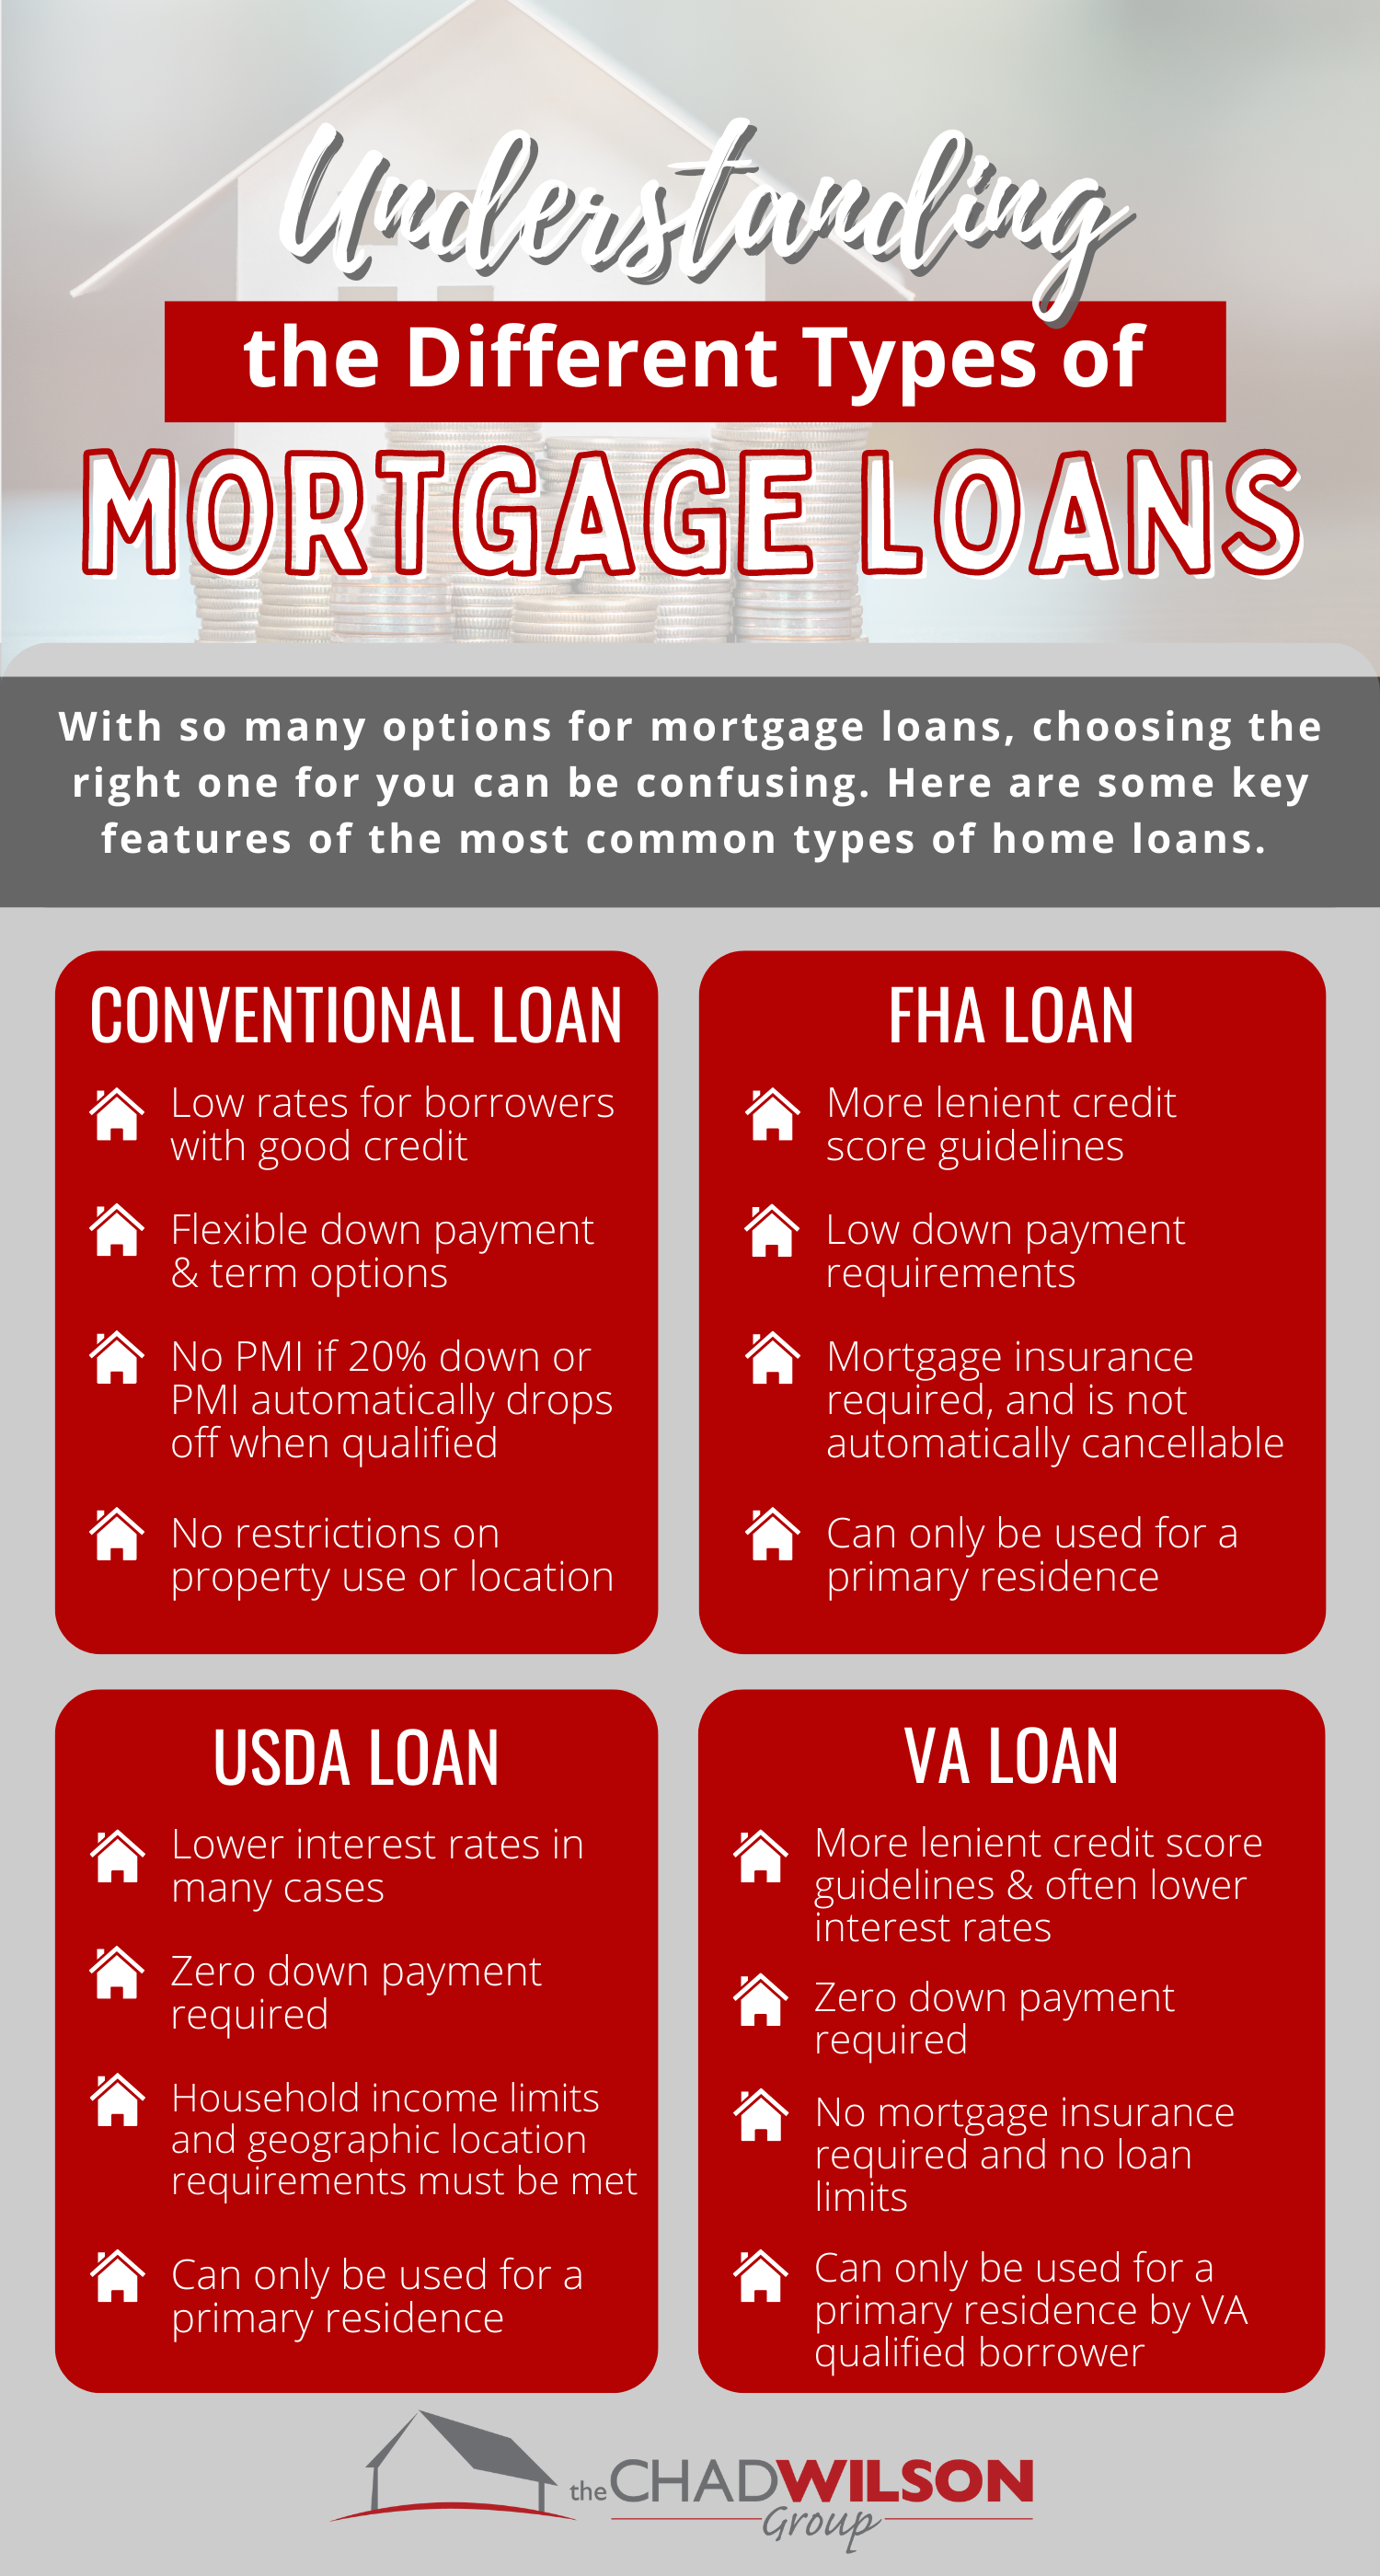
This approach works well for salaried employees, W-2 workers, and predictable income streams. It becomes significantly more complicated if you have variable income, commission structures, seasonal employment, or multiple income sources from different types of work. Independent contractors and freelancers face additional hurdles because lenders view their income as less stable. The workaround is usually to document the longest possible history, ideally two full years with consistent or growing net earnings, and to avoid making any major business structural changes right before applying, such as switching from an LLC to an S-corporation, which triggers additional documentation requirements. There's also a ceiling on how much this planning can help you. If your credit score is below 620, your DTI is above 50 percent, or you have recent derogatory events like a foreclosure or short sale within the last three years, Mortgage Planning alone won't get you to a conventional loan. You'd be better off exploring FHA or state-backed programs that have more forgiving guidelines, even if the monthly cost is higher due to mortgage insurance premiums. Knowing when to stop trying to optimize and instead switch strategies is part of the process. The best single action you can take right now is calculating your exact DTI with every known debt included and comparing it against the 43 percent threshold. Run that number through a rate sensitivity model. Then sleep on it. Most decisions made in a rush around mortgage applications end up costing more than the alternative of waiting three to six months to enter the market with a stronger profile.