Mortgage discount points are an upfront fee paid to lower your interest rate. One point equals 1% of your loan amount. Paying points trades short-term cash for long-term savings, and the break-even calculation tells you whether that trade is actually worth it for your situation.
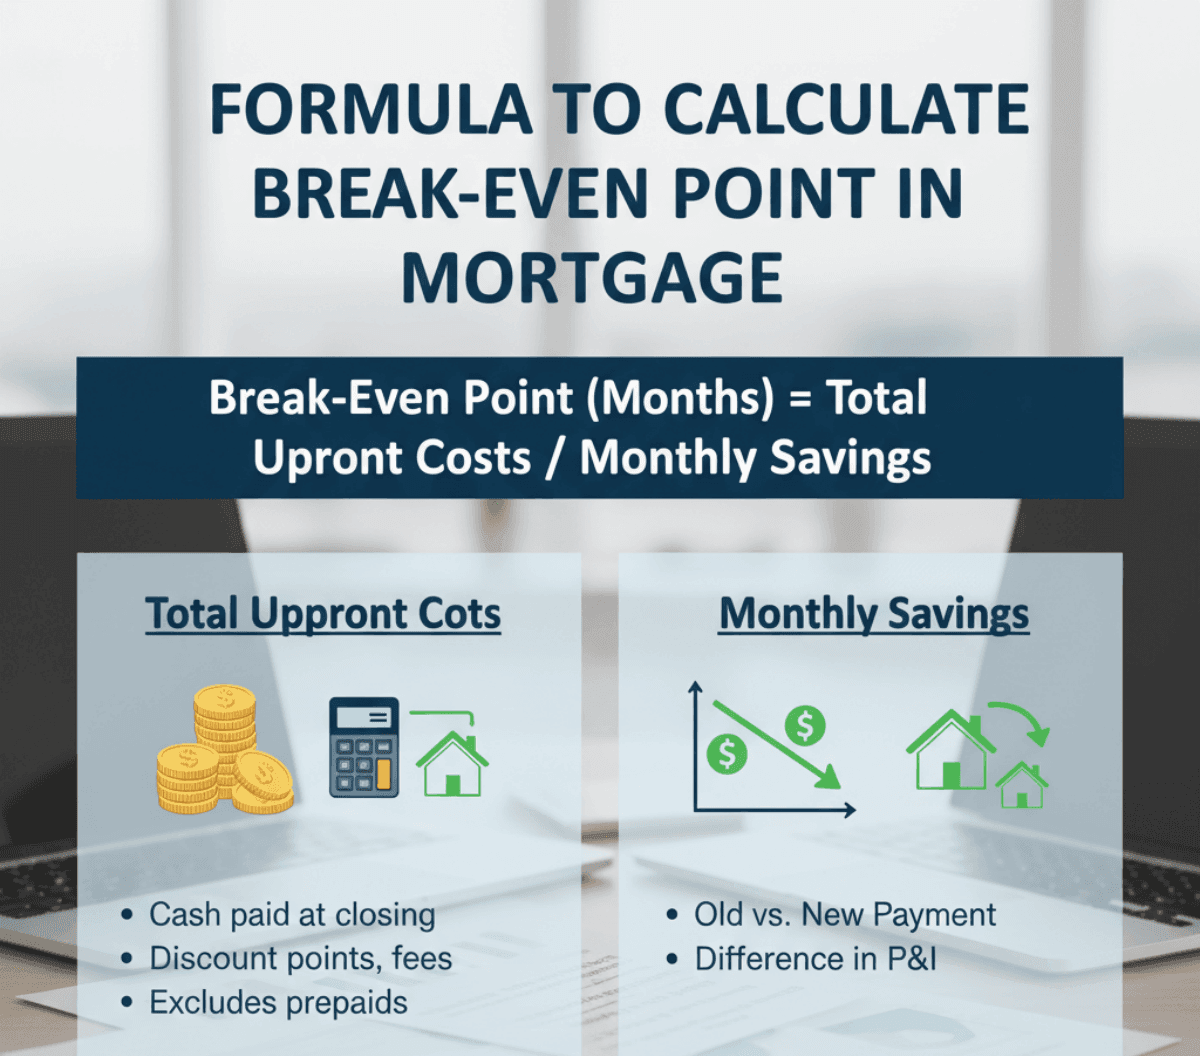
The basic formula is straightforward: divide the total cost of the points by your monthly interest savings. That gives you the number of months until you recover the upfront cost.
How to Use a Mortgage Point Break Even Calculator
I built a simple tool for this because most online calculators make assumptions that don't hold in real transactions. You'll need four numbers: the loan amount, the current rate without points, the discounted rate after buying points, and the number of points you're considering purchasing.
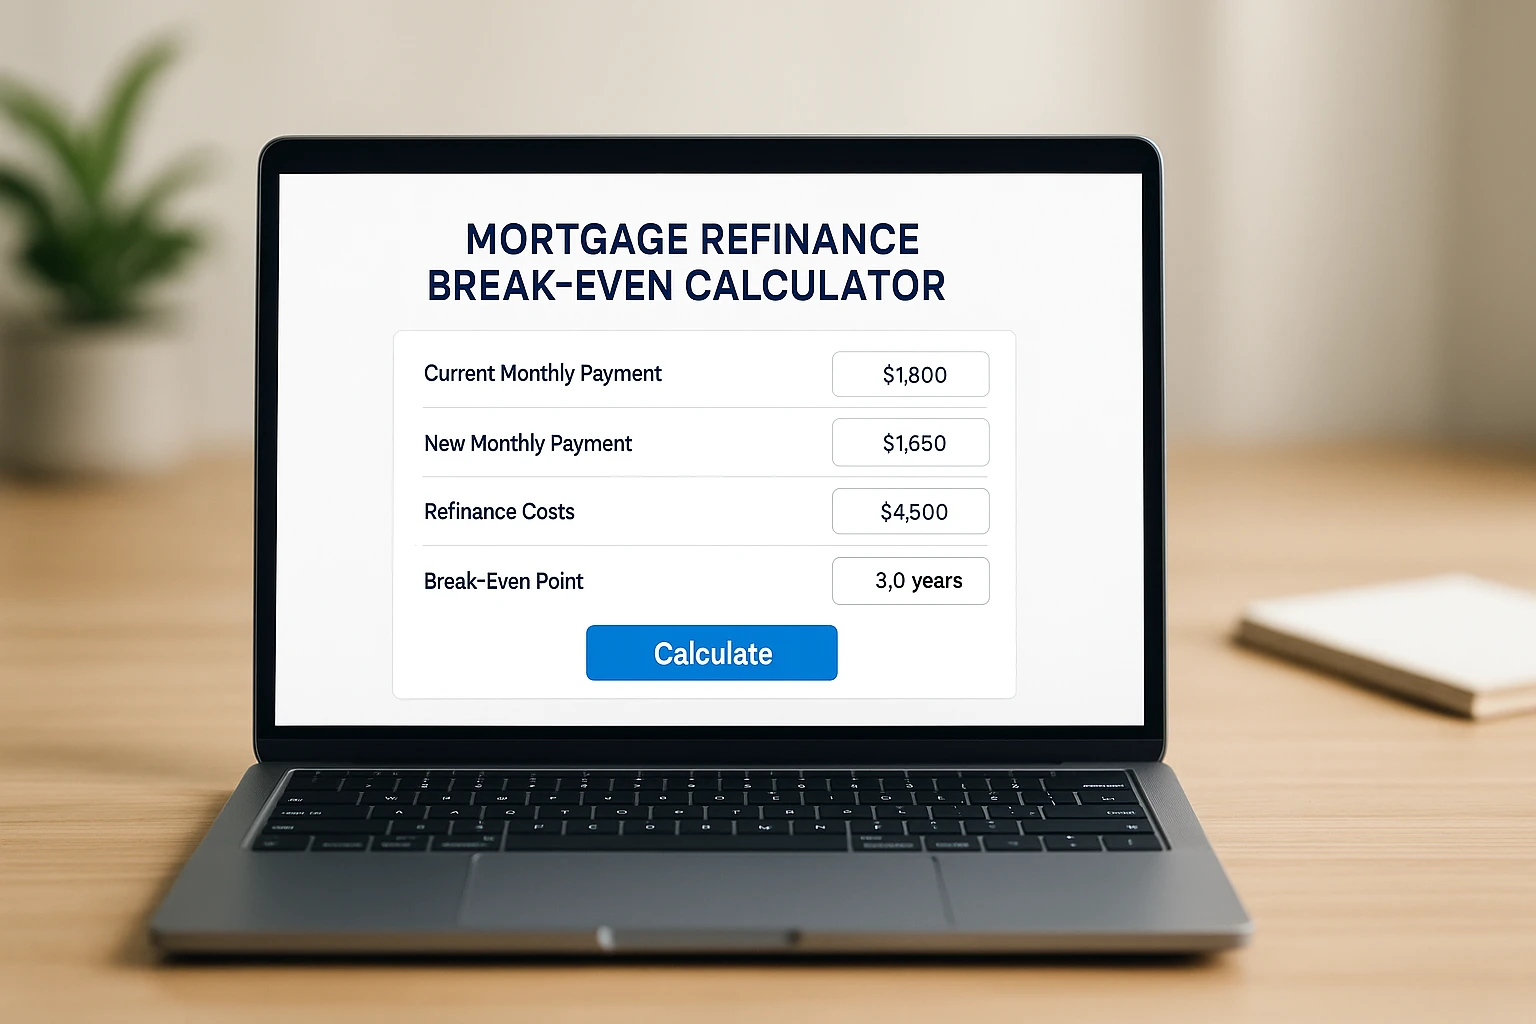
Enter the loan amount. Enter the existing rate and the new rate after discount points. Enter how many points you're buying. The calculator computes the total upfront cost, your monthly savings, and the break-even period in months. It also converts that into years and months for readability.
Here's an example from a recent file I worked on. A borrower was looking at a $385,000 loan at 6.75% versus 6.25% if they bought two points. The upfront cost was $7,700. Their monthly payment dropped from $2,496 to $2,371, a savings of $125 per month. The break-even came out to about 62 months, or roughly five years and two months. They planned to stay in the house for twelve years, so the math worked. Not always the case.
The Mechanics Behind the Calculation
The core computation works like this. The cost of points is the loan amount multiplied by the number of points expressed as a decimal. Monthly savings is the difference between the payment at the original rate and the payment at the discounted rate. The break-even in months is the total point cost divided by the monthly savings.
Payment calculations use the standard amortization formula. For a fixed-rate loan, the monthly payment is the loan amount multiplied by the monthly interest rate, divided by one minus one over one plus the monthly rate, all raised to the number of payments. This is standard mortgage mathematics.
The calculator runs client-side JavaScript, so the math happens instantly in the browser. There's no server call, no data leaving your machine, no waiting on a backend. This matters when you're comparing multiple scenarios back to back during a busy closing week.
Real-World Complications That Online Calculators Miss
The clean formula breaks down fast once real-world factors enter the picture. Here's what I've seen actually affect whether points are worth it.
Refinancing risk. The break-even assumes you keep the loan for the full period. If you move, refinance, or sell before the break-even point, you've lost money. I had a client in 2022 who bought two points on a refi at 5.5% going to 5.0%. The break-even was 41 months. She sold her house 18 months later because her job relocated. She never recovered the points cost. Any reasonable analysis needs to factor in your actual expected holding period, not just hope it works out.
Prepayment behavior. Most borrowers don't make exactly 30 years of payments. Extra principal payments, annual overpayments, or just making two extra payments a year change the equation dramatically. When I first started running these calculations, I used a standard payment comparison that ignored prepayment. That was wrong. The fix was to simulate the actual amortization schedule with the borrower's stated prepayment plan, then compare total interest paid between the two scenarios. This usually shifts the effective break-even by 6 to 14 months depending on how aggressively they pay down the loan.
Tax implications. Discount points are generally tax-deductible in the year paid, but only if you itemize deductions and only on your primary residence. This changes the real cost of points. A borrower in the 24% tax bracket who itemizes effectively pays 76 cents on the dollar for each point. The calculator currently shows the gross cost. You need to mentally adjust for your tax situation, or note the after-tax cost separately.
Closing cost stacking. Sometimes points are bundled into a broader renegotiation of fees. Lenders might credit you back on origination fees if you buy points, or vice versa. The break-even calculation should use the actual net cash-out at closing, not just the theoretical point cost. I had a situation where a borrower was quoted "two points" but the lender also added a $1,200 processing fee that wasn't there on the no-points option. The true cost was higher than the calculator would show with just the point input. Always compare total closing costs between the two scenarios.
Rate lock expiration. Points are part of the rate lock agreement. If your rate lock expires before closing and the new rate is different, the entire calculation changes. I've seen this bite people when locks expire on a Friday and underwriting drags into the next week. The calculator assumes the rates you enter are the rates you actually get. They might not be.
When Points Make Sense and When They Don't
Points make sense when you plan to stay in the home well past the break-even point and you have the cash available without depleting reserves. Points do not make sense when the break-even extends beyond your expected ownership period, when you'd need to tap retirement accounts or high-interest debt to cover the cost, or when the rate difference is smaller than typical lender credits offer for free.
Lender credits are the counterpoint to points. Instead of paying upfront, you accept a higher rate and the lender covers some closing costs. For someone selling in three years, lender credits almost always beat points.
Using the Calculator Properly
Run it for multiple point options simultaneously. Buy one point, buy two points, buy zero. The comparison between scenarios reveals more than any single number. The tool recalculates instantly when you change inputs, so try several configurations in one session.
Save your results. Take a screenshot or note the break-even months for each scenario. File comparison is important six months later when you're actually at the closing table and the processor asks whether you want to keep the points or switch to lender credits.
The calculator gives you a baseline. It doesn't replace a full loan estimate comparison from your lender, and it doesn't account for every variable in your specific financial situation. But it does give you a quick, private way to understand the core trade-off before you sit down with a loan officer and start negotiating.
Gallery Mortgage Point Break Even Calculator
Mortgage Points Break-Even Calculator Excel at Olivia Brewster blog
Mortgage Points Calculator - Break-Even Analysis Tool
Mortgage Points Break-Even Calculator | Super Global Calculator
Solved - How to Calculate Break-Even Point in Mortgage?
Mortgage Refinance Break Even Calculator Guide