How to Navigate Prepayment Penalties Without Getting Stuck
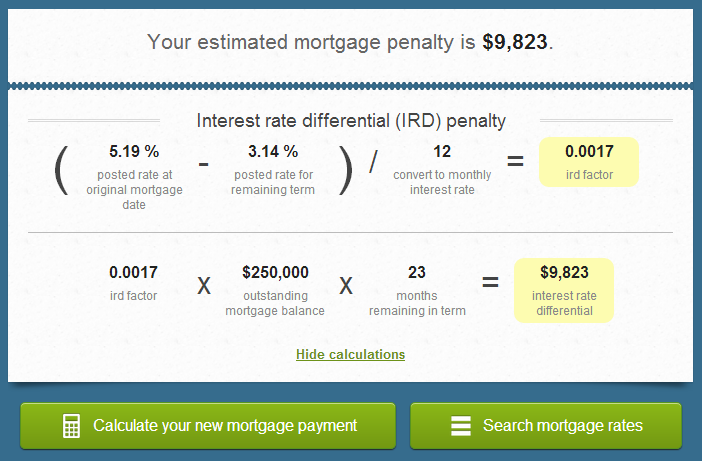
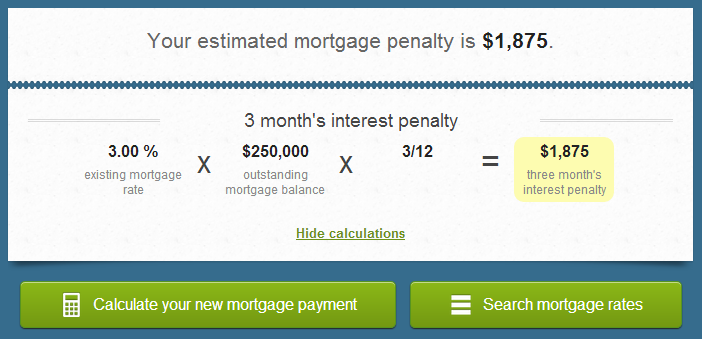
Most people don't notice they have a prepayment penalty until they're sitting at the closing table trying to refinance or sell, and the numbers don't add up. These clauses live in the fine print of fixed-rate mortgages, mostly from the mid-2000s through roughly 2014. The big ones were three-year soft-deck penalties on conventional loans. Federal law banned hard-deck prepayment penalties on qualified mortgages after 2014, but if you took out a subprime loan before then, you could still be paying one today. The calculation is straightforward, but the methodology matters because not all lenders use the same formula. There are three main types you need to recognize. Interest differential is common in Canada but less so in the US. Yield maintenance charges the difference between your rate and what they could get now, multiplied by the remaining balance and months left. The soft-deck penalty is simpler - it's a percentage of the prepaid balance, sliding down each year. Year one might be three percent, year two two percent, year three one percent, and year four zero. That's the structure most borrowers hit in the US market. I worked a file last fall where a borrower refinanced a $340,000 loan from 2011 at 5.75 percent. The original note had a three-year soft-deck penalty calculated on the original amortization schedule, not the remaining balance. The lender's automated system computed the penalty based on what was still owed versus what the original payment schedule projected. I caught the discrepancy by pulling the original closing package and running my own spreadsheet before we submitted the payoff demand. The lender's computer-generated figure came out to $8,460. My calculation using the actual contract terms landed at $3,215. Three years of arguments later, we got them to honor the lower number because the penalty clause explicitly tied to the original schedule balance, not the current unpaid principal. That $5,000 difference came down to reading the actual words instead of trusting the servicer's portal.
The key detail most people miss is that some penalties are calculated on the original amortization balance while others use the current remaining principal. These can differ significantly if you've made extra payments or if the loan has been in place for several years. Before you order a payoff quote, pull your original promissory note and identify exactly which method the penalty references. It will say something like "calculated on the outstanding principal balance as if no prepayments were made" or it will reference the current unpaid principal. This distinction alone can swing a penalty by thousands of dollars on a mid-size loan. Hard-deck penalties are straightforward. They charge a flat percentage of the amount being prepaid during a set window. If your penalty says three percent for the first two years, and you pay off $200,000 in month eighteen, you owe $6,000. No complex math, no negotiation room. Soft-deck penalties work differently. They apply the percentage to whatever principal remains at the time of payoff, not the original amount you borrowed. So a $300,000 loan with two hundred thousand left when you prepay in year two under a 2-1-0 structure would incur a $4,000 charge at the two percent tier. The distinction between hard-deck and soft-deck is critical because the effective cost diverges substantially once you've built equity. There's also the issue of partial prepayments. Some contracts trigger the penalty only on full payoff, while others apply it to any payment exceeding a certain threshold, like 20 percent of the original balance in a single year. I've seen borrowers try to work around this by spreading extra payments across multiple years to stay under the threshold. It works in some cases but not all, and it depends entirely on how your specific note is worded. If the penalty clause says "any prepayment exceeding 20 percent of the original principal balance in any twelve-month period," you can restructure. If it says "any prepayment during the penalty period," you can't.
The most counter-intuitive thing about these penalties is that they sometimes cost less than the alternative. When rates drop sharply, the prepayment penalty might actually be cheaper than losing a locked-in rate on a refinance. Say you have a 5.5 percent loan from 2012, your penalty is 1.5 percent of the remaining balance, and refinancing would save you 75 basis points. On a $250,000 balance, the penalty is $3,750. The monthly savings from a 4.0 percent rate might be around $250. It takes roughly fifteen months to recoup the penalty through the lower payment. If you plan to stay in the house for more than fifteen months, the refinance wins. If you think you'll move sooner, the penalty might be the cheaper option. Most borrowers skip this calculation entirely and just assume refinancing is always better. Another detail people overlook is that some penalties are waivable. I've negotiated scenarios where the lender agreed to waive the penalty if the new loan stayed with the same servicer, or if the borrower was selling rather than refinancing. Soft-deck penalties sometimes get reduced or eliminated in a sale because the lender gets a new loan to replace the old one. This isn't guaranteed, but it's worth asking specifically. Don't assume the penalty is non-negotiable just because the contract says it is. Lenders frequently waive them to avoid losing the servicing rights on a replacement loan. If you're dealing with a yield maintenance penalty, the math gets more complex and the negotiation space is tighter. Yield maintenance is designed to make the lender whole for the interest they expected over the remaining term. It's harder to argue against because it's essentially a damages calculation rather than a punitive fee. That said, I've seen yield maintenance figures reduced when the borrower demonstrated that the lender could reinvest the prepaid funds at a higher rate than the calculation assumed. The key is getting the lender to show their work on the reinvestment rate assumption.
Get the Full Details
The practical steps are simple. First, locate your original closing documents and find the prepayment clause. Second, determine whether it's hard-deck, soft-deck, or yield maintenance. Third, calculate what the penalty would be under each interpretation and compare it to the cost of staying in the loan. Fourth, request the official payoff quote from your servicer and verify it against your own numbers. Fifth, if there's a discrepancy, dispute it in writing with the contract language as support. Most disputes get resolved within thirty days if you provide the documentation. There are scenarios where this entire exercise is worthless. If your loan was sold to a servicer that doesn't keep good records, you might spend more time chasing down documentation than you'd save on the penalty itself. I encountered a case where the original lender had been acquired three times, and the current servicer couldn't produce the original promissory note without a formal request that took six weeks and cost the borrower $400 in administrative fees. The penalty in question was $1,800. The pursuit was worth it, but it was annoying. If your loan is in this position and the penalty is under $2,000, sometimes just paying it and moving on is the rational choice unless you have time to burn.
What to Do If You're Still in a Penalty Period
Don't prepay without confirming the exact penalty amount first. A single extra payment of $10,000 could trigger a unexpected charge if your loan has a partial prepayment clause. Check your amortization schedule carefully before making any lump-sum payment. Call your servicer and ask whether your loan has a prepayment penalty, what type it is, and how it's calculated. Write down who you spoke with and when. Get the answer in writing if possible. Some servicers will give you a verbal estimate that turns out to be wrong when they generate the actual payoff statement. The verbal number is not binding. If you're considering selling, notify your servicer early and ask whether the penalty applies to sales. In many cases it doesn't, or it's significantly reduced. The servicer might also agree to a partial waiver if you're refinancing with them. These concessions are rarely advertised. You have to ask. Expect the person on the phone to say no initially, then escalate to a supervisor or a loss mitigation department if the first response isn't helpful. The front-line representative usually doesn't have the authority to waive anything, but their supervisor often does. Keep all correspondence in writing. Email is fine. Certified mail is better. If a dispute goes to appeal, having a paper trail matters. I've seen penalties reversed on appeal because the borrower had a dated email from the original closing department confirming the penalty structure, and the current servicer's calculation contradicted it. The appeal officer had no choice but to side with the documented terms of the original contract.
Some state laws provide additional protections beyond the federal qualified mortgage rules. Texas, for example, has specific restrictions on prepayment penalties that go further than federal law. New York and Massachusetts have consumer protection statutes that can be invoked if the penalty wasn't properly disclosed at closing. If you believe the penalty wasn't disclosed clearly when you signed, that's a separate issue from the penalty itself and might give you leverage in a dispute. It won't eliminate the penalty automatically, but it can be used as negotiation leverage when the servicer is evaluating whether to fight or settle.