How to Track Your Actual Mortgage Principal Balance Without Getting Lost in the Numbers
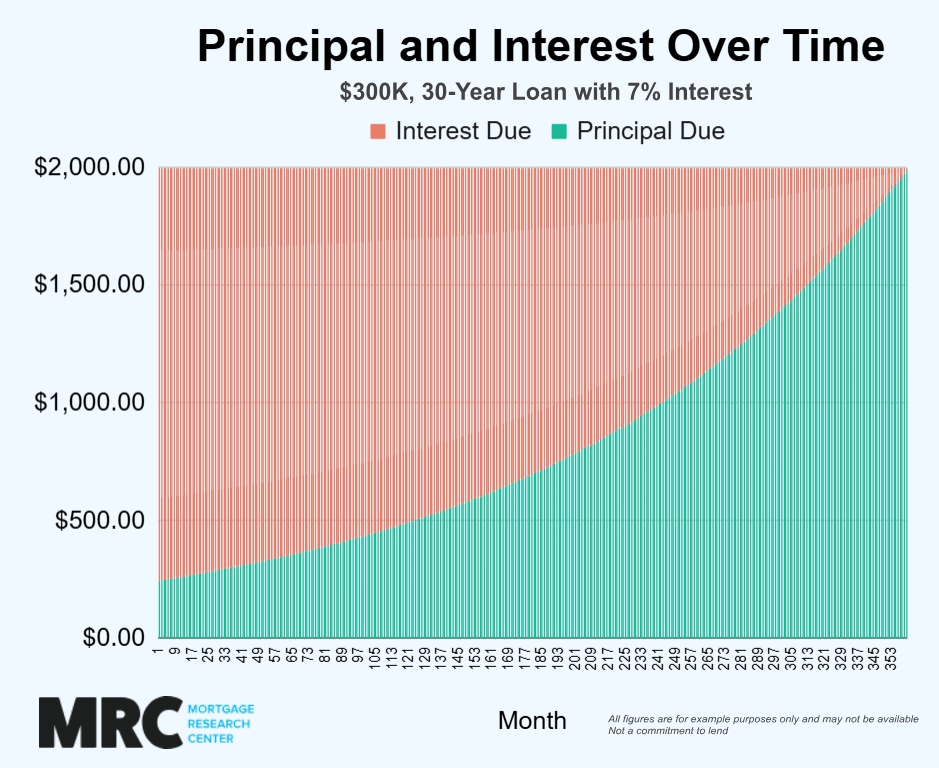
The mortgage principal balance is the amount you still owe on the original loan amount, excluding interest, taxes, and insurance. Most people confuse it with their total monthly payment or their home equity, which creates real problems when they try to make decisions about refinancing, selling, or extra payments. I see this mistake constantly. When you take out a loan for $400,000 to buy a house, your initial mortgage principal balance is $400,000. Every month, a portion of your payment goes toward paying down that balance and the rest goes toward interest. Over time, the principal portion grows and the interest portion shrinks. That shifting ratio is what amortization means in practice. Here is the thing most calculators and lender statements don't make obvious: your principal balance does not decrease at a steady rate. In the first year of a 30-year fixed loan at 6.5% interest on $400,000, you might only reduce the principal by about $4,200 despite paying roughly $30,000 in total payments. That leaves a remaining mortgage principal balance of around $395,800. The math feels brutal when you see it laid out like that, but it is how these loans work from day one.
To find your exact current balance, log into your servicer's online portal and look for the line labeled "principal balance" or "remaining principal." Do not confuse this with your escrow balance or your estimated home equity. The principal balance number is what matters for debt-to-income ratios, refinancing eligibility, and understanding how much real ownership you actually have.
Calculating It by Hand When Your Servicer Is Being Unhelpful
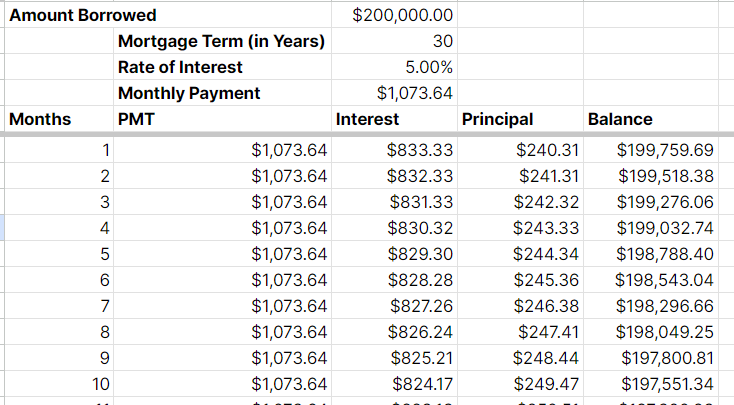
Sometimes the online dashboard is outdated, shows a stale figure from months ago, or simply refuses to display the current number. I had this happen with a client who was trying to qualify for a cash-out refi and her servicer's portal showed a balance that was $8,000 higher than what it should have been based on her payment history. The discrepancy came from a late-fee capitalization that the servicer added to the principal rather than tracking separately. This is a known issue with older servicing systems. Here is the formula you can use to verify the number yourself: Your remaining balance equals the original loan amount minus the total principal paid to date. To calculate principal paid, you can use the standard amortization formula or a simple Excel layout. Create columns for payment number, total payment, interest portion, principal portion, and remaining balance. Start with your original balance in row one. For each subsequent row, multiply the previous balance by your monthly interest rate to get the interest portion, subtract that from your fixed monthly payment to get the principal portion, and deduct that principal from the previous balance. After twelve iterations on that $400,000 loan at 6.5%, you should land very close to the $395,800 figure I mentioned.
Get the Full Details

If you want a faster method, the FV function in Excel or Google Sheets will give you the remaining balance directly. The formula looks like this: FV of the remaining payments at your interest rate. Specifically, =FV(monthly_rate, remaining_payments, -monthly_payment, original_loan). This approach is reliable and takes about two minutes to set up correctly.
Why the Balance Matters More Than You Think
Your principal balance determines several things that affect your financial life directly. It establishes how much home equity you have, which impacts your ability to refinance without private mortgage insurance, qualify for a home equity line of credit, or sell without bringing cash to closing. Lenders typically require a certain loan-to-value ratio, and that ratio is calculated using your principal balance against your current home value, not your original purchase price. Here is a nuance most people miss. Making extra payments toward principal does not always reduce your balance the way you expect. Some servicers apply prepayments to future interest first, particularly if you are near a prepayment penalty window. I worked with a borrower who made a $25,000 lump-sum payment and three months later discovered only $3,200 of it had actually reduced the principal. The rest was sitting in an unapplied suspension account because the servicer had not yet processed the interest recalculation. The workaround was to call the servicing department, request a principal-only application in writing, and get a written confirmation of the new balance within 30 days. Most larger servicers can do this, but you have to push for it because their automated systems default to the slower processing path.
Common Mistakes That Inflate Your Reported Balance
Property tax and insurance escrow shortages are a major source of confusion. When your escrow account runs low, the servicer may increase your monthly payment and sometimes advance the shortfall into the principal balance as a suspended asset. This increases your reported mortgage principal balance even though you have not actually borrowed more money. The charge appears on your statement as an escrow shortage advancement, but if you are not reading the breakdown carefully, it looks like regular principal reduction. Another issue is capitalized interest. If you miss a payment and the servicer rolls the missed interest into your balance instead of charging it as a separate fee, your principal balance increases. This happens more often than you would expect with loans that have entered forbearance or modification programs. During the pandemic era, this was widespread. Even now, servicers sometimes capitalize delinquent interest during loss mitigation processing, and the new balance carries forward incorrectly on statements. Appraisal gaps in refinancing can also inflate the balance unexpectedly. When you refinance and the home appraises for less than the new loan amount, some loan programs allow you to finance the gap, which increases your principal balance beyond what the property is actually worth. This creates negative equity immediately and can trap you in the loan for years.
When You Should Check Your Balance Regularly
I recommend reviewing your principal balance every quarter at minimum. Set a calendar reminder for the first week of January, April, July, and October. Pull your official statement from the servicer, not just the dashboard number, because the printed statement reflects actual posted transactions. Compare it against your own amortization schedule and flag any discrepancy larger than $200. Most errors fall into one of three categories: a payment was not applied to principal, an escrow advancement was capitalized, or a fees package was added to the balance without proper notice. If you are planning to sell or refinance within six months, check monthly. The balance directly affects your net proceeds and your refinancing terms, and small discrepancies compound quickly when you are calculating closing costs or estimating payoff amounts.
A Note on Where This Approach Falls Short
The manual calculation method I described works for standard fixed-rate mortgages with no modifications, forbearance, or unusual payment structures. It breaks down for adjustable-rate mortgages that have reset, government loans with subsidy adjustments, or loans that have gone through a modification program. In those cases, the balance calculation becomes unpredictable because the servicer may have changed the interest rate, extended the term, or restructured the payment in ways that a simple amortization formula cannot account for. The only reliable approach there is to request a formal payoff quote from your servicer, which will reflect all current adjustments. Payoff quotes are valid for 30 days and include the precise principal balance plus any accrued interest and fees up to a specified date. Understanding your mortgage principal balance is not complicated, but it requires attention to detail that most lenders will not volunteer. The numbers on your statement are usually correct, but when they are wrong, the corrections are slow and often incomplete unless you actively monitor them. A quarterly check takes about ten minutes and can save you thousands over the life of the loan by catching errors before they lock in.