How to Navigate Mortgage Qualifying Without Losing Your Mind
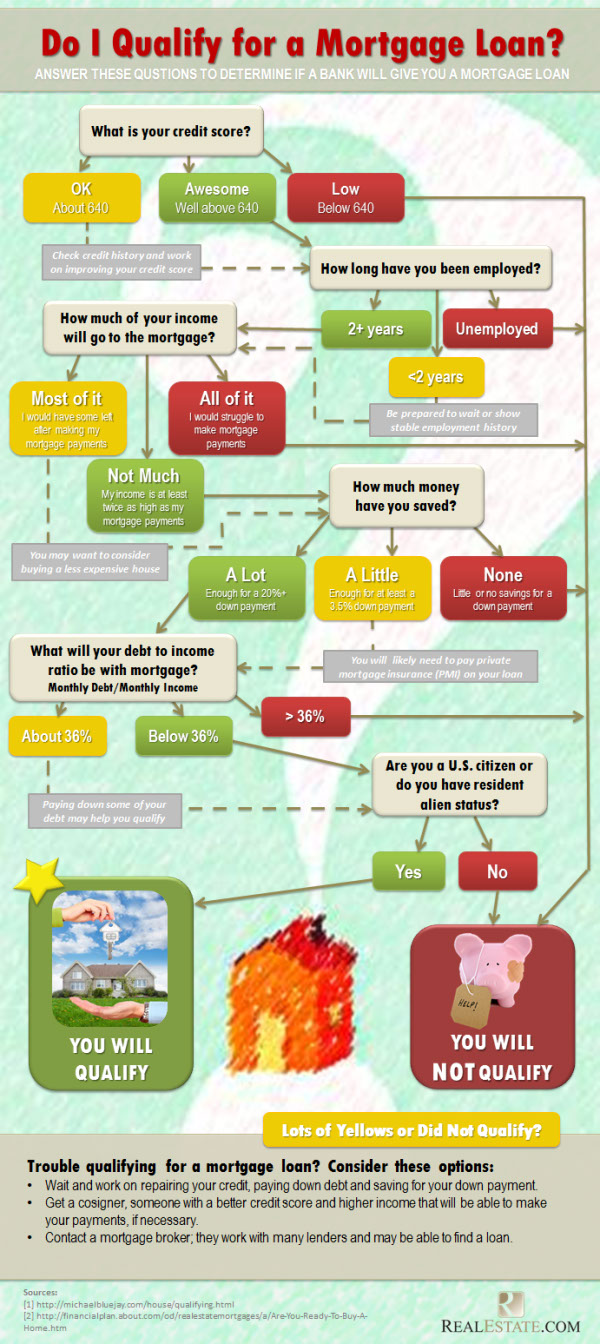
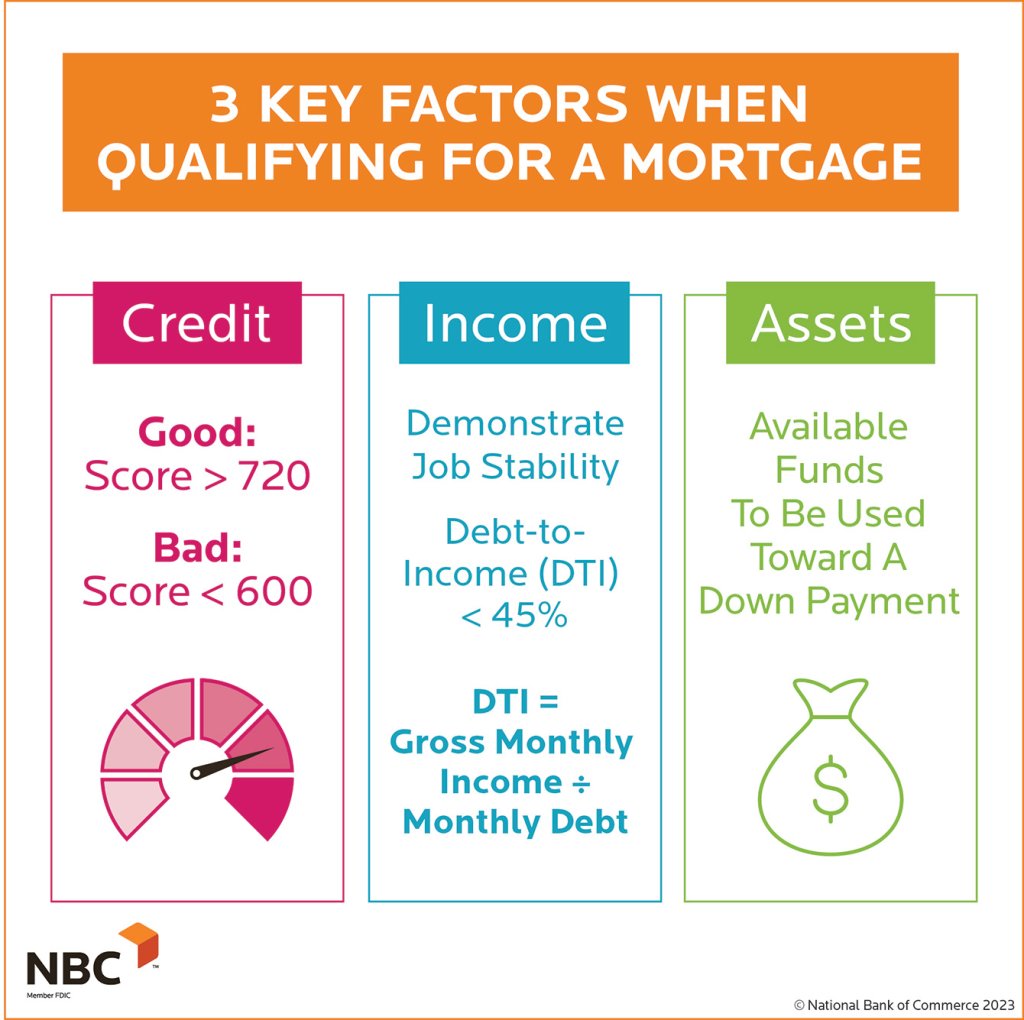
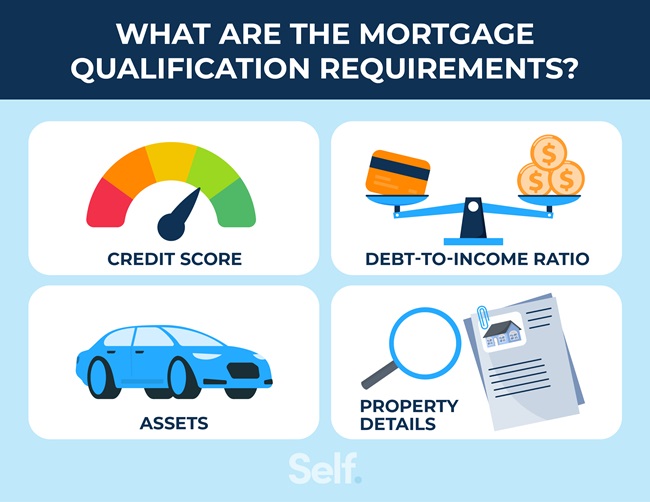
Mortgage Qualifying is the process lenders use to determine whether you can afford a home loan. It sounds straightforward until you've been sitting at your kitchen table at 11pm on a Tuesday, trying to figure out why your self-employment income isn't counting the way your tax returns suggest it should. The basics are simple enough. Lenders look at your debt-to-income ratio, credit score, employment history, and available assets. But the devil is in the details, and most people I talk to have never actually spoken to a loan officer who explains what's happening under the hood.
What Mortgage Qualifying Actually Involves
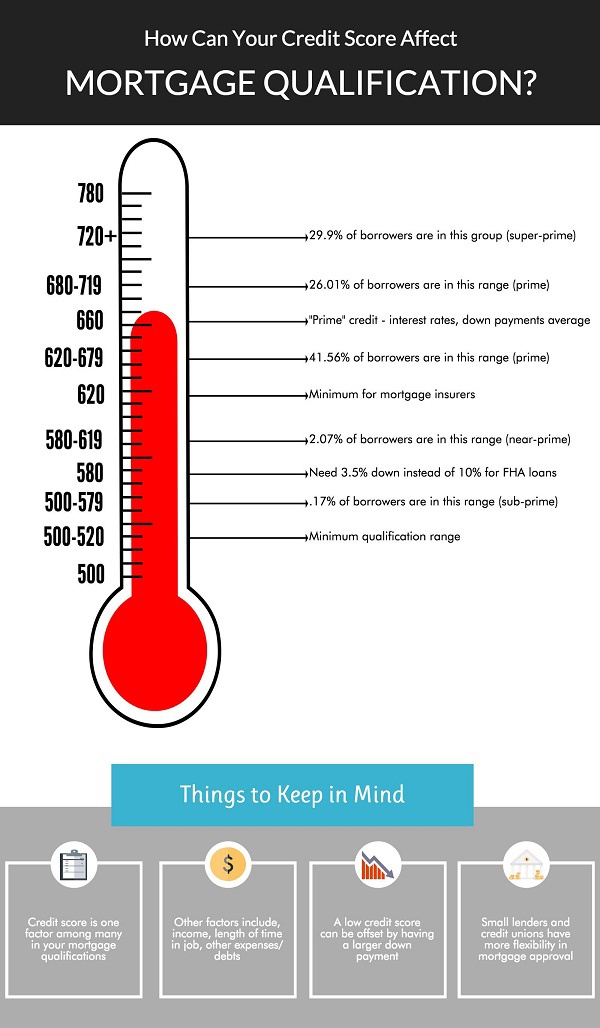
DTI ratios are the first thing that trips people up. Most conventional loans require you to stay under 43% of your gross monthly income going toward debt payments. Some programs go higher. Federal Housing Administration loans can stretch to 50% in certain cases, but you'll pay extra for that flexibility in the form of mortgage insurance premiums. Credit scores matter, but not as much as people think. A 620 score gets you approved for conventional financing, though you'll likely see rates three or four percentage points higher than someone with a 760. The real damage happens when you're stuck between score tiers. Going from 740 to 739 can cost you thousands over the life of a thirty-year loan. It's not dramatic, but it's real. Employment verification is where things get complicated. Standard practice requires two years of documented employment in the same field. The logic is sound on paper. In practice, it creates absurd situations where someone gets denied because they switched from teaching to instructional design, even though the work is substantially identical.
The Side Hustle Problem Nobody Talks About
Here's a scenario I dealt with about three years ago. A client came to me with strong credit, solid employment at a tech company, and a profitable side business generating roughly $3,000 a month in additional income. He had complete bookkeeping, quarterly tax filings, and everything looked good on paper. Underwriting flagged his self-employment income because his Schedule C showed a net profit that was inconsistent month to month. They wanted two full years of income averaging out to a favorable number. His first year of business was rough. He took a hit on revenue early on, which dragged the average down enough to push his qualifying income below what he actually needed. The workaround: we pulled his year-to-date figures and had him provide a letter from his primary employer confirming his base salary wouldn't change for the foreseeable future. Combined with the year-to-date self-employment income, the compensating factors were enough to get the file approved. It wasn't the cleanest application I've ever seen, but it worked.
Get the Full Details
Assets and Reserves
Lenders want to see reserves, meaning money left over after your down payment and closing costs are accounted for. Conventional loans typically require two to six months of mortgage payments sitting in the bank. The exact amount depends on your credit profile, how many units you're buying, and whether you're a first-time buyer. Gift funds from family are acceptable, but they need proper documentation. A signed gift letter stating the money is not a loan, plus proof of transfer from the donor's account to yours. Skip the paperwork and your closing date moves two weeks into the future while the processor tracks down whatever you neglected to include.
Common Pitfalls That Delay Approvals
The biggest mistake I see people make is opening new credit accounts during the application process. Even a small purchase on a new card that shows up on your credit report mid-underwriting can trigger a manual review. The loan officer might not know you applied for it. The underwriter will see the inquiry and either ask questions or delay the decision. Another issue is large deposits into your checking account. If you move ten thousand dollars from a savings account at one bank to your checking at another, the underwriter needs a paper trail. They need to see that the money came from an established source. Transfers between accounts at the same institution are straightforward. Moving money around multiple banks requires documentation that not everyone has ready to go. Self-employed borrowers often make the mistake of paying down business debts right before applying, thinking it improves their DTI. It does, technically. But it also reduces your cash reserves. Lenders care about both. Sometimes paying down debt is the right call. Sometimes it's counterproductive, and the reserves you depleted matter more than the slightly better ratio.
Adjustable-Rate vs. Fixed During Qualification
There's a difference between qualifying at the initial interest rate and qualifying at the fully indexed rate on an adjustable mortgage. Some lenders will use the teaser rate for the first five or seven years, which makes your monthly payment look lower and your DTI look better. Others use the fully indexed rate, which factors in where the index is expected to be. If your goal is to qualify on paper, the teaser rate method is more forgiving. If your goal is to actually afford the payment when the rate adjusts, the fully indexed method is honest. Both approaches are valid. Just know which one your lender is using before you start comparing numbers.
When Mortgage Qualifying Fails Completely
Let me be blunt about the scenarios where standard qualifying doesn't work. If you're self-employed and your business has less than two years of history, most conventional loans are off the table unless you have significant assets and an excellent credit profile. You'll be looking at portfolio lenders or non-QM products, which come with higher rates and stricter terms. If you've had a foreclosure or short sale within the last three to seven years, your options narrow considerably. Conventional loans require seven years from foreclosure. FHA loans allow three years in some cases. Private mortgage insurance requirements will also be steeper. There are programs that exist, but they're not competitive with standard financing. Investment properties are a different beast entirely. Lenders typically require a higher credit score, a larger down payment, and they count rental income at 75% of the projected amount rather than 100%. The downside is that the qualification standards are designed to make investment purchases harder. That's by design. They want to ensure you can cover the payment if the unit sits vacant.
Practical Steps Before You Apply
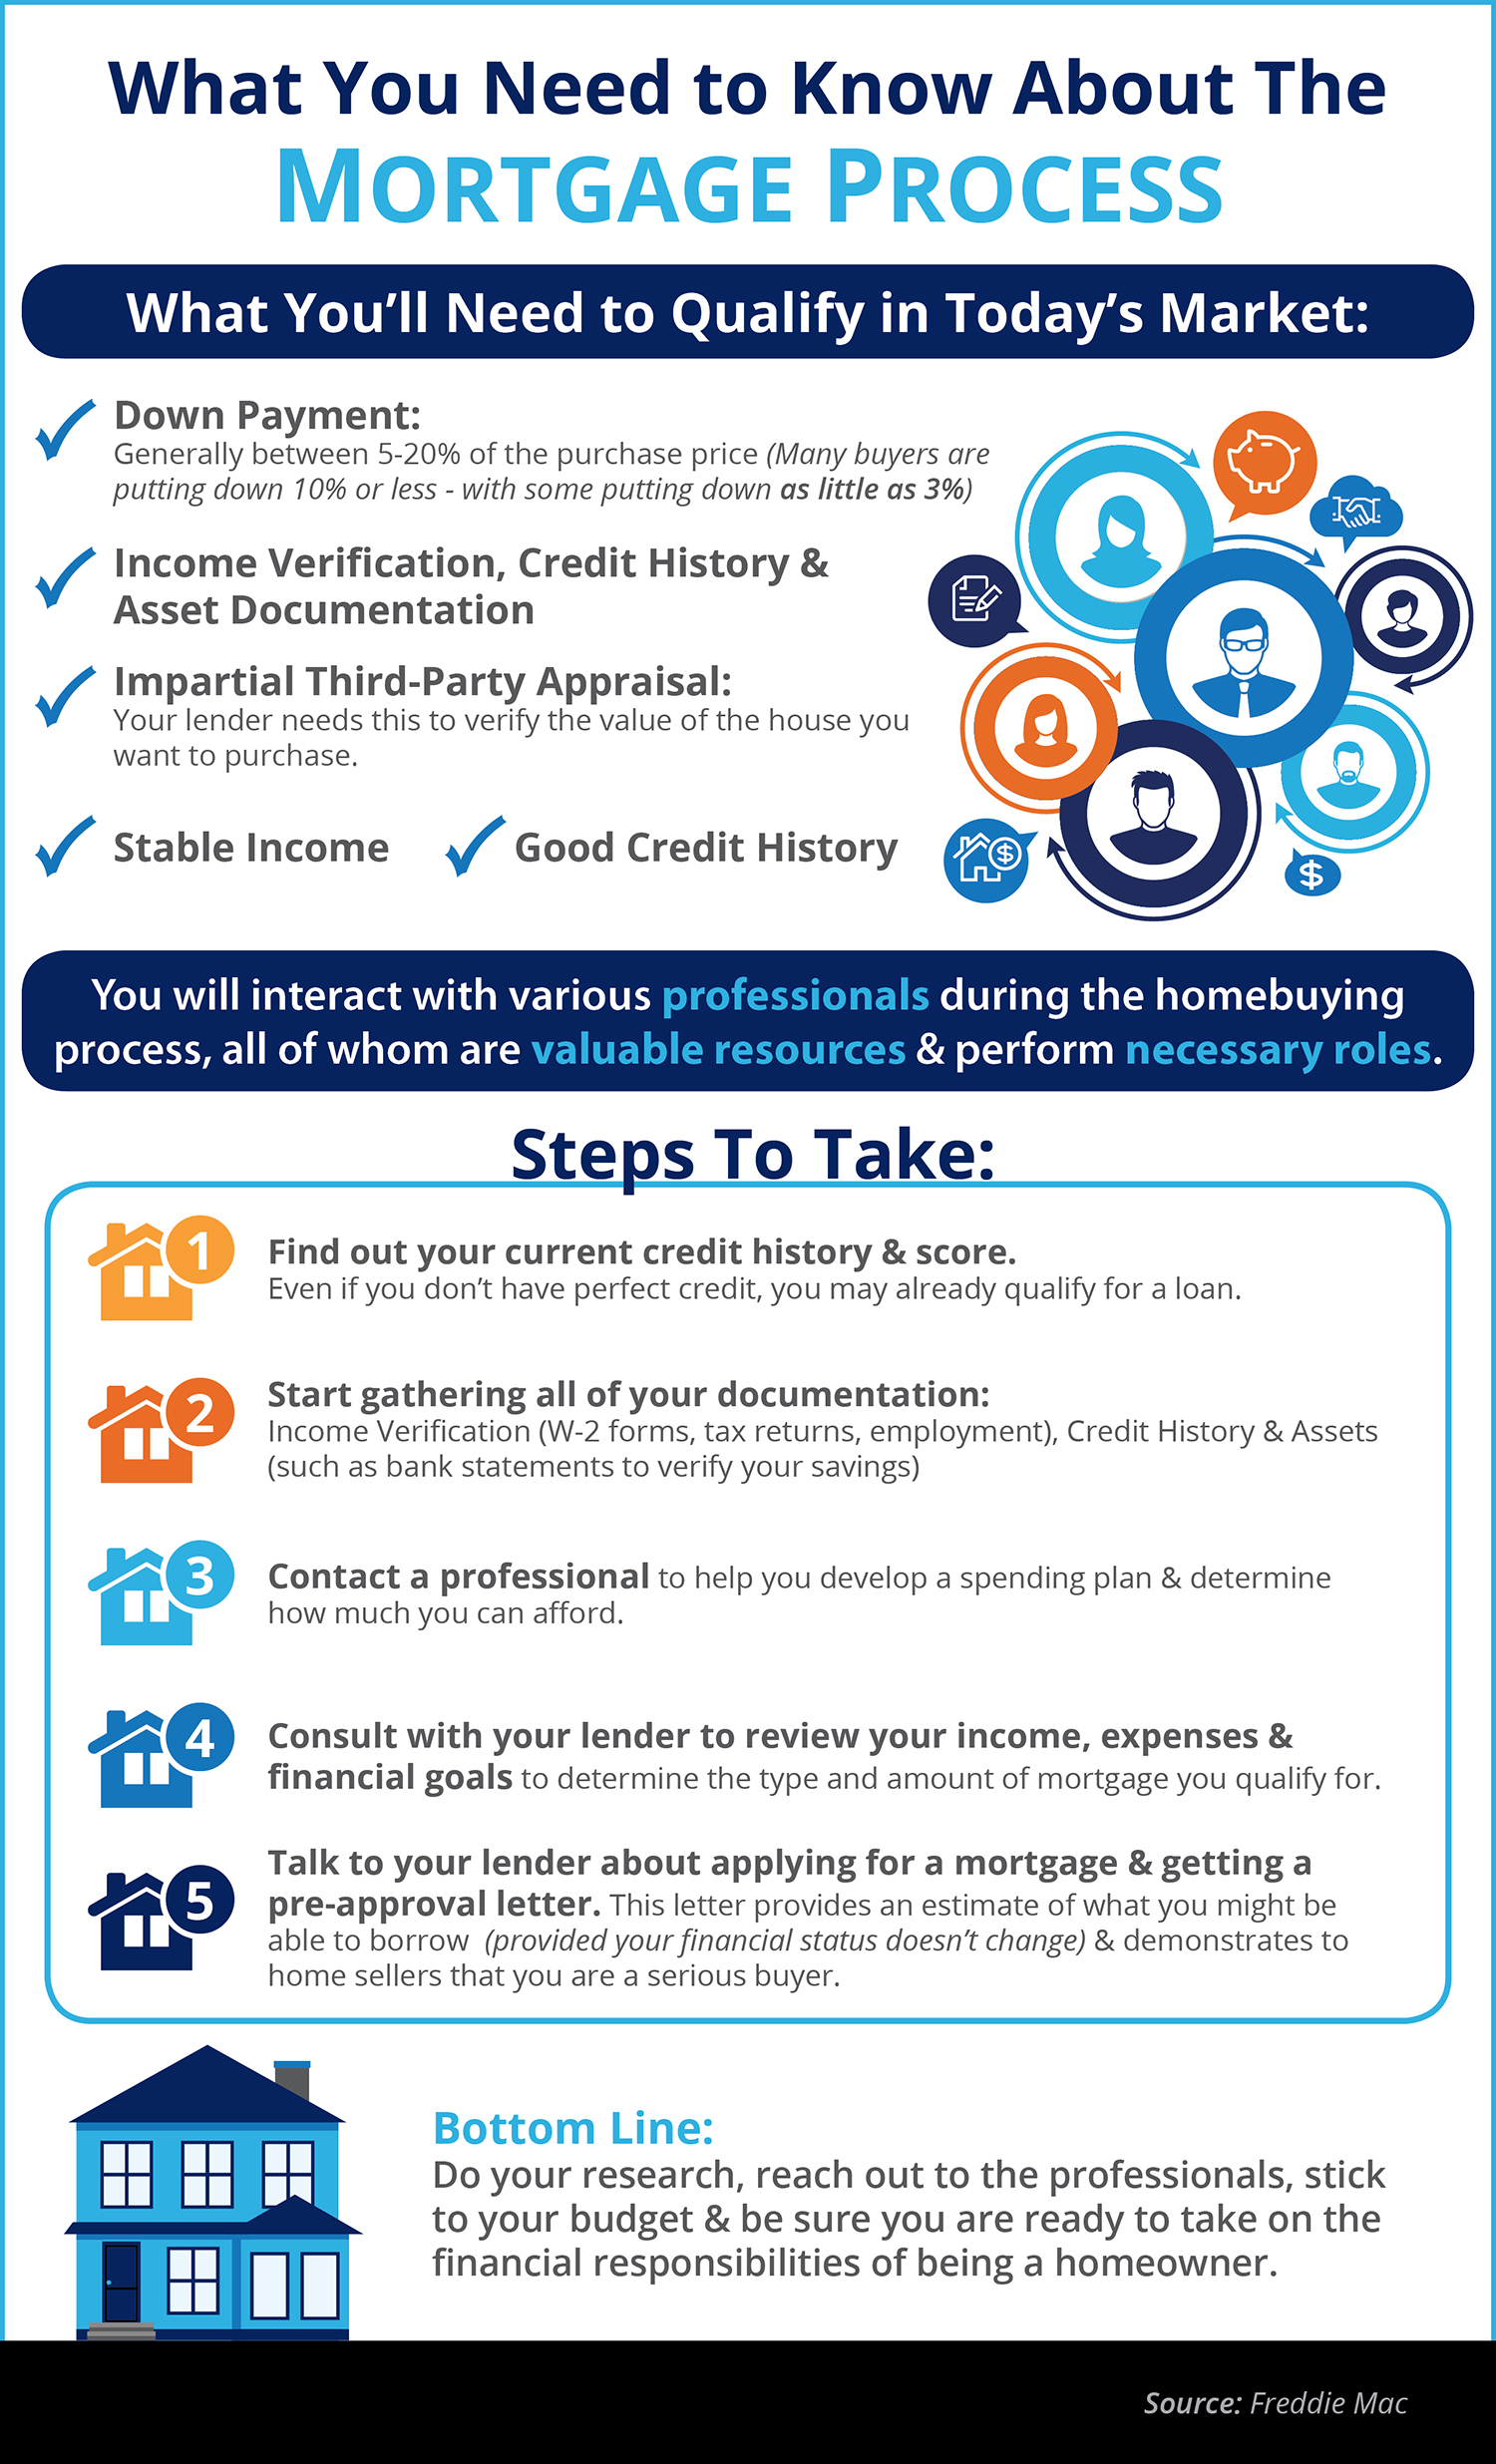
Pull your credit reports from all three bureaus and check for errors. Dispute anything that's incorrect before you submit an application. A wrong late payment notation can tank your score by fifty points or more. Calculate your DTI on your own. Use gross income, not net. Include every debt obligation: car loans, student loans, credit cards, child support, anything with a monthly payment. Lenders will calculate this themselves, but knowing your number ahead of time prevents unpleasant surprises. Organize your documentation before talking to a lender. Tax returns for the last two years, W-2s, pay stubs for the last thirty days, bank statements for the last two to three months, and documentation for any gifts or large deposits. Having everything ready speeds up the process significantly and signals to the loan officer that you're serious and organized.
The Underwriting Gap
One thing most people don't understand is the gap between conditional approval and clear to close. Conditional approval means the underwriter has reviewed your file and identified conditions that need to be satisfied. It's not a done deal. Some conditions are routine, like verifying your employment one final time. Others can be blockers, like unexpected activity on your credit report or a new debt that shows up before closing. I had a file once where the borrower received a small inheritance between conditional approval and closing. The money went into his checking account, which looked like an undocumented deposit. We had to provide the death certificate, the probate documents, and the chain of transfers. It added five business days to the process. Not catastrophic, but something nobody warned him about. Mortgage Qualifying is less about meeting a checklist and more about understanding the criteria your lender is applying. The system is designed to catch risk, and the faster you can identify your own risk factors before the underwriter does, the smoother the whole process becomes.