How FHA Mortgage Rates Actually Work in Practice
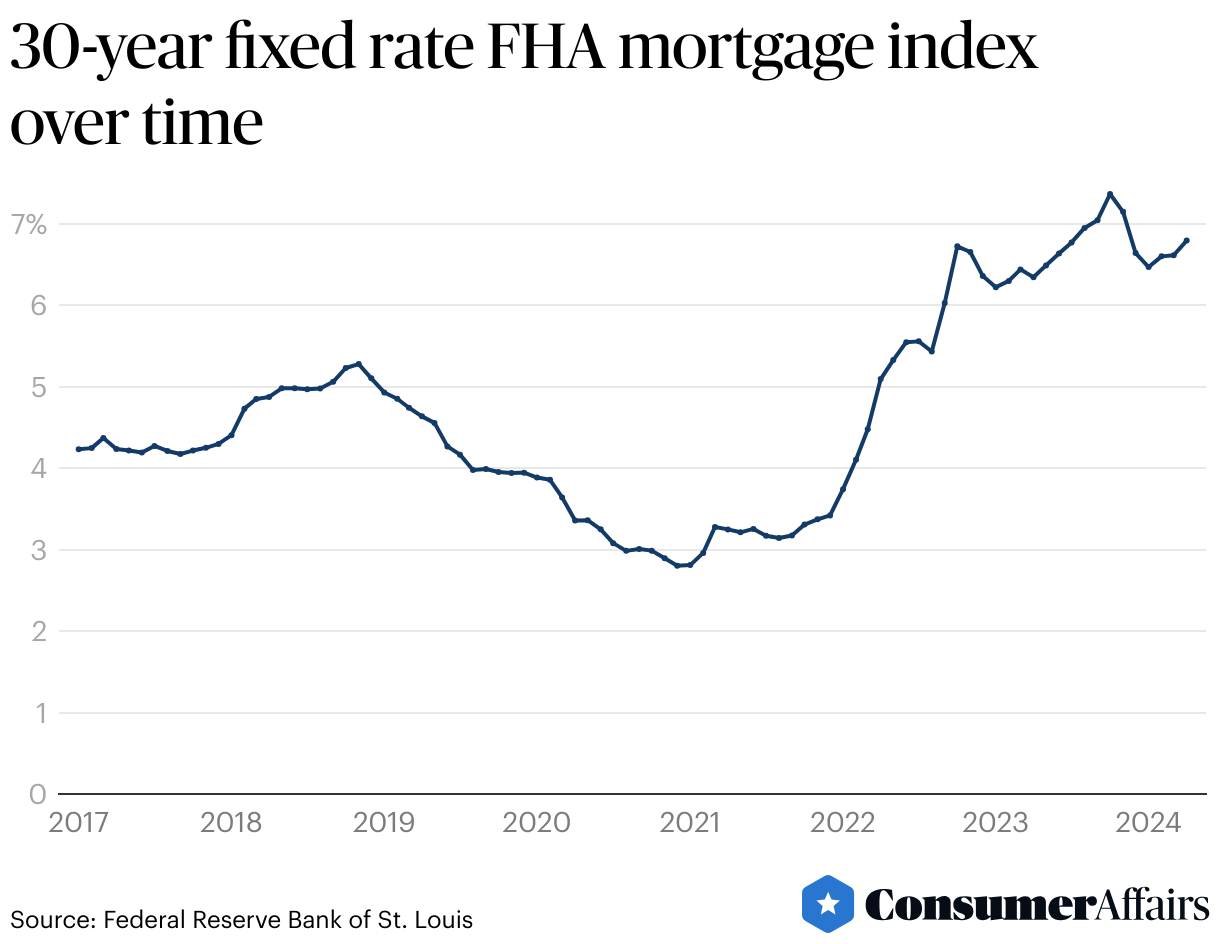
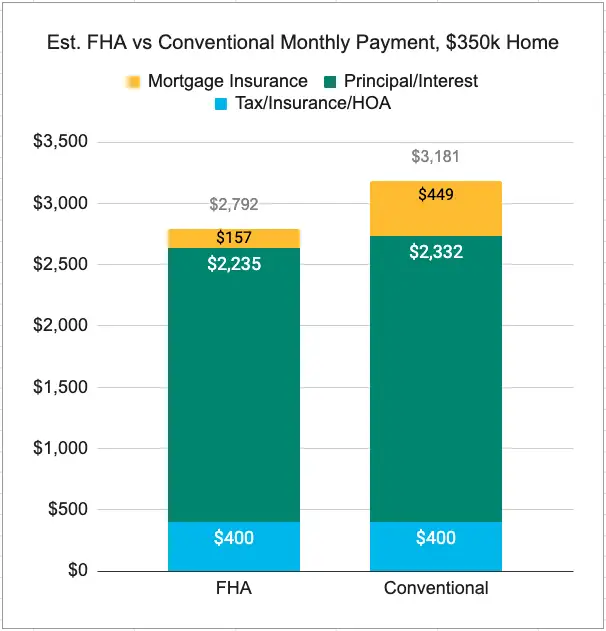
FHA loans use the same interest rate pricing as conventional loans, but the total cost picture looks different because of the mortgage insurance premiums you have to pay on top. Most people only look at the headline rate when comparing FHA rates vs conventional rates, and that is a mistake. The annual MIP can add roughly 0.55% to your effective borrowing cost, which completely changes which option is cheaper month to month. You can pull FHA rates from several places, and they vary by source. The Fed HPI data doesn't publish rate quotes directly, but it shows the broader trend. Most people check the major lender sites, use RateEngine-level platforms, or look at Freddie Mac's Primary Mortgage Market Survey, which is probably the most reliable weekly aggregate. When I need a quick check I run a rate order through my LOS and compare three lenders on the same loan profile. Same LTV, same credit tier, same lock period. Anything less than that and you are comparing apples to oranges and wasting about 20 minutes of your day. The rates you see posted online are usually promotional base rates. The actual rate you get depends on your credit score band, loan amount relative to county limits, debt-to-income ratio, and whether you are buying or refinancing. A 680 credit score borrower with a 72% LTV gets something noticeably different from someone at 760 with a 60% LTV. I had a borrower last year who was quoted 7.125% by a retail lender and then got 6.625% through our wholesale channel on identical terms. The 50 basis point difference came down to how the two shops priced FHA paper that week. Wholesale channels often trade on tighter spreads for government-backed products.
The Mortgage Insurance Premium Issue
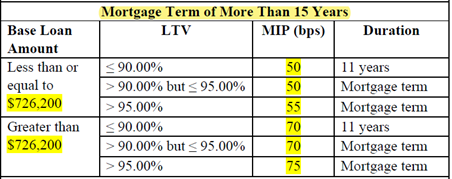
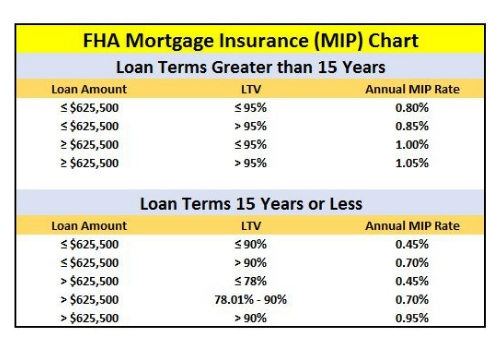
This is where most people get burned. FHA requires both an upfront MIP and an annual MIP. The upfront premium is typically 1.75% of the base loan amount, and you can roll it into the loan or pay it out of pocket. The annual MIP runs 0.55% for most standard 30-year purchases, billed monthly. Here is the thing nobody emphasizes enough: if you put down less than 10%, the annual MIP lasts for the entire life of the loan. Period. There is no way to drop it unless you refinance into a conventional loan later. I ran into a situation recently where a client wanted to cancel the MIP after seven years because they thought they could reach 20% equity through principal paydown alone. That does not work with FHA. You have to refinance. She ended up locking into a conventional loan at a slightly higher rate but dropped the MIP and saved roughly $180 a month. We ran the break-even analysis and it took about 22 months to recoup the refinance costs, which was acceptable given where rates were at the time. If you are in that position, keep a close eye on rate spreads and your loan-to-value ratio. Once you hit 78% LTV through payment alone you can request cancellation on a conventional loan, but that rule never applies to FHA.
What Actually Moves FHA Rates Day to Day
FHA rates track the broader bond market. They move with Treasury yields, specifically the 10-year, and with Ginnie Mae MBS spreads. When the Fed signals a pause or a cut, FHA rates usually follow within a couple of trading sessions. When inflation data comes in hot, they jump. The spread between conventional and FHA can widen or narrow depending on investor demand for government-backed paper. Right now, in the current environment, that spread hovers around 10 to 25 basis points with FHA often trading slightly higher because of the MIP risk premium investors factor in. Loan size matters more than people expect. FHA has county loan limits that change every year. In 2024 the baseline limit was $498,257 and high-cost areas went up to around $1,149,825. If your conforming loan is above the FHA limit but below the jumbo threshold, you are looking at a Jumbo FHA loan, and those come with different pricing. The rates tend to be slightly higher because the pool of investors willing to buy that paper is smaller. I had a client in San Diego last spring who was about $40,000 over the FHA ceiling. We ran the numbers against a jumbo conventional and the jumbo FHA was actually cheaper after insurance, but the upfront costs were higher. It took me about 45 minutes to build a side-by-side comparison that made sense to her. The spreadsheet came out to roughly $63 a month difference in total payment, which sounds small but adds up to over $22,000 over 30 years.
Get the Full Details

Practical Ways to Get a Better Rate
Pay points. One point buys you 0.25% off your rate on most FHA products. If you are closing a $400,000 loan, that is $4,000 upfront for a permanent 25 basis point reduction. On a 30-year fixed that saves you roughly $90 a month. The breakeven is about 47 months. If you plan to stay in the house longer than four years it is almost always worth it. I usually tell clients to buy one point unless their credit score is in the 660s, in which case the rate drop from points is smaller and the math gets fuzzy. Increase your down payment to 10%. That is the single biggest lever you have for lifetime MIP cancellation. At 10% or more, the annual MIP drops after 11 years instead of lasting forever. If you can scrape together that extra 5%, you should seriously consider it. The alternative is paying MIP for three decades, which on a $350,000 loan at 0.55% annually means roughly $1,925 per year in insurance you will never get back. Shop multiple channels within a two-week window. Rate shopping within 14 days counts as a single hard pull for scoring purposes, so you can get quotes from four or five lenders without tanking your score. I recommend running at least three quote comparisons. The variance between lenders on the same FHA product can be 30 to 50 basis points, sometimes more. That is $100 to $175 a month on a typical loan, or $36,000 to $63,000 over the life of the loan. Not something you want to leave on the table because you called one bank and accepted their first number.
When FHA Is the Wrong Choice
FHA is not universally better just because the down payment is lower. If you have a credit score above 740 and can put down 20%, a conventional loan will almost certainly cost you less over time. The MIP on FHA erodes the benefit of a potentially lower rate. I had a borrower last year with a 780 score and $80,000 saved who insisted on FHA because a friend told her it was easier to qualify. She qualified easily for conventional, got a rate that was 37 basis points lower, and would have saved over $40,000 in MIP by just going conventional. She stuck with FHA for three years, then refinanced to conventional when rates dropped and finally saw the savings, but those three years of unnecessary MIP payments totaled about $17,500. She could have avoided that entirely. If your credit score is below 620, FHA is still your best option since most conventional lenders won't touch you at that tier, but even then the rates you get will be poor. You are better off spending six to twelve months rebuilding your score before you apply. A 20-point jump from 610 to 630 can move you from sub-prime pricing to near-prime pricing, and that difference is usually 75 to 125 basis points. On a $300,000 loan that is $225 to $375 a month. No amount of FHA flexibility makes up for bad credit pricing.
Lock vs Float Decision
Once you pick a lender and get a rate lock, you are either locked in or floating. A lock locks your rate for a set period, usually 30 to 60 days. A float means you are riding the market and hoping rates go down before closing. I generally recommend locking on FHA loans unless you have a very strong view on where rates are heading and the lock period gives you room to move. The reason is simple: FHA rates are already crowded with MIP risk, and a rate increase of even 25 basis points during lock expiration can wipe out your entire down payment advantage over conventional. Floating feels smart until it doesn't, and then you are stuck choosing between a worse rate or walking away from the contract. If you do decide to float, make sure your contract has a float-down option. Some lenders offer it for an additional fee, usually 0.25% to 0.50% of the loan amount, but it lets you capture a lower rate if the market moves in your favor while protecting you from rate increases. It is worth the fee if you think rates might dip before closing. I had a client who locked at 7.00%, rates dropped to 6.50% mid-lock, and we exercised the float-down for 0.25%. She saved roughly $150 a month on a $320,000 loan. The float-down fee was $800. She broke even in about five and a half months and then kept saving for the rest of the term.