Why most refinance calculators lie to you
I built a Mortgage Refinance Break Even Calculator because the free ones online kept giving me numbers that didn't match my spreadsheet. Not off by a few dollars. Off by months. Turns out the difference comes down to whether the tool accounts for things that actually exist in real lending, or just pulls two interest rates and divides closing costs by monthly savings. Here is the actual formula. It sounds simple and it is, but the implementation details are where people get burned.
Using a Mortgage Refinance Break Even Calculator correctly
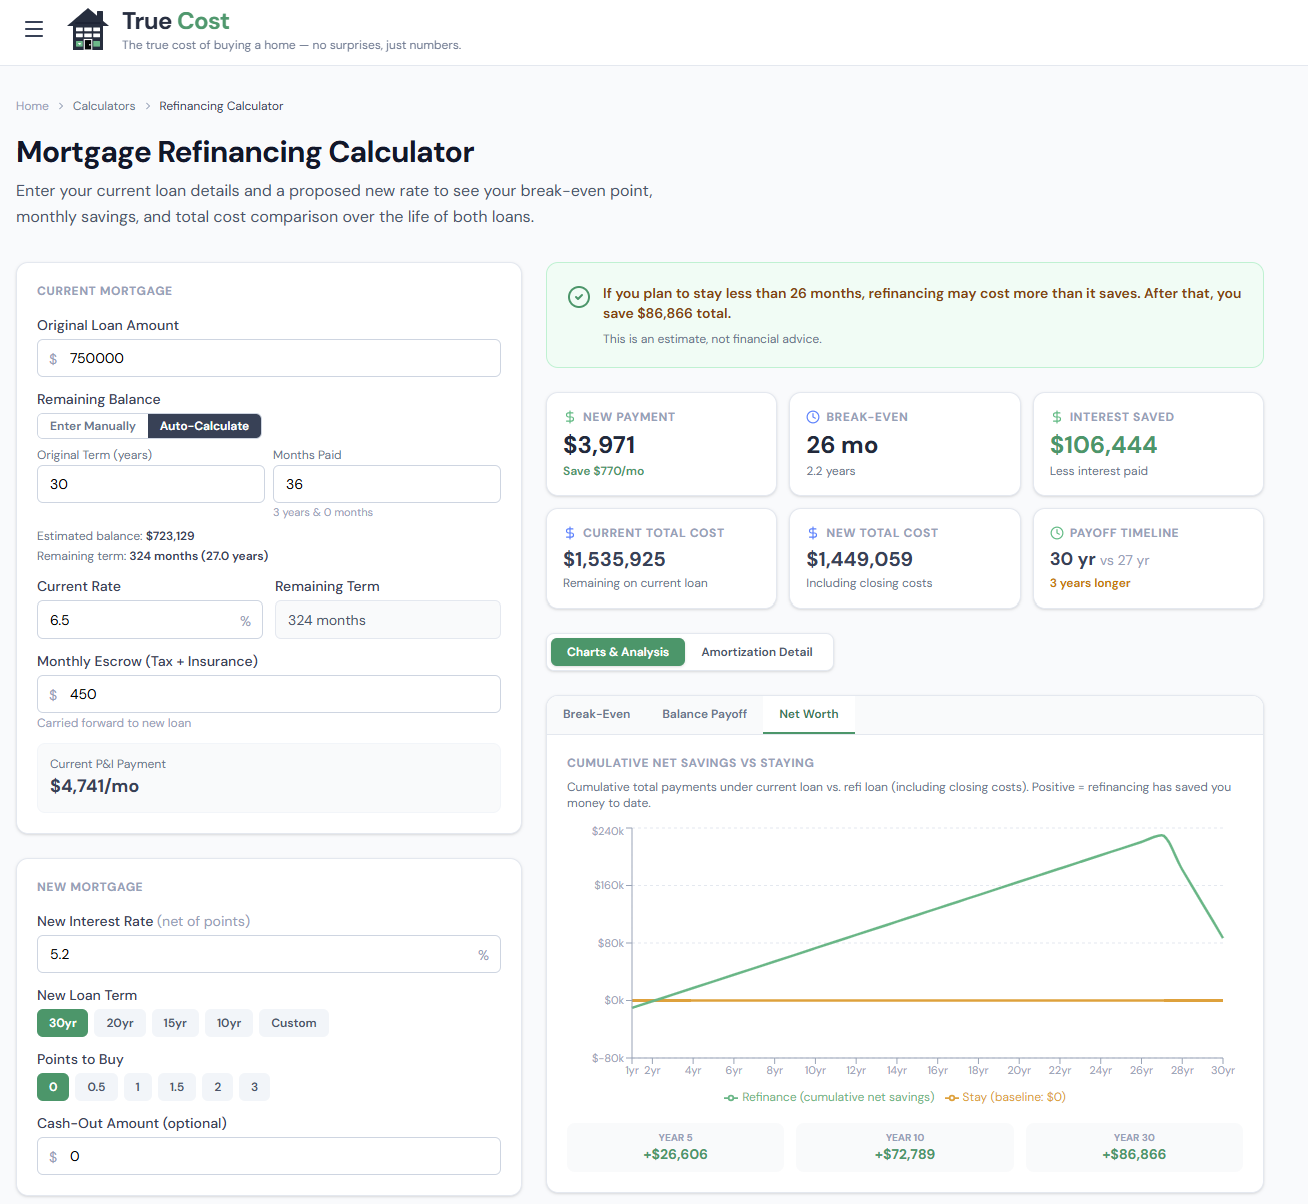
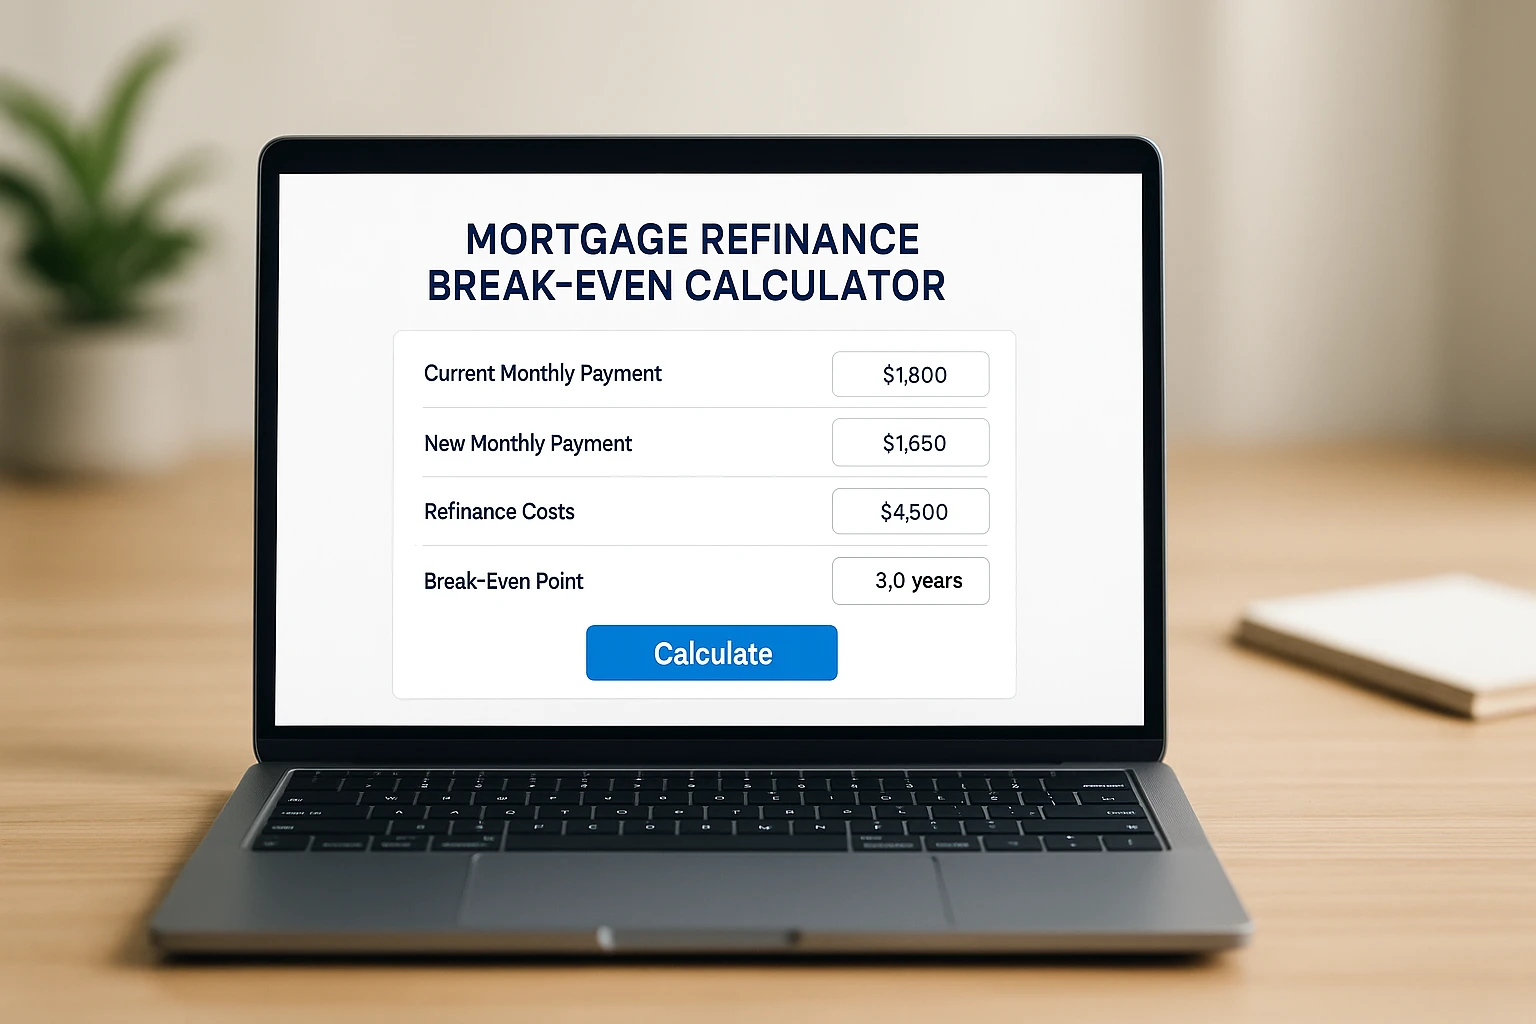
The break-even point is closing costs divided by your monthly payment savings. That is it. If it costs $4,500 to refinance and your new payment is $320 a month less than your old one, you break even in about 14 months. Simple arithmetic. The problem is figuring out what goes into "closing costs" and what goes into "monthly payment savings" without lying to yourself. When I built my calculator, I made sure it forces you to itemize every fee instead of letting you throw a lump sum in. Most free calculators let you enter "total closing costs" as a single number, which is where the errors creep in. You need to know whether you are rolling costs into the loan balance, paying them out of pocket, or buying down the rate with points, because each of those changes the math completely. I ran into a specific problem with an adjustable-rate refinance last year. My break-even calculation came out to 22 months, which looked fine on paper. But I had forgotten that the new loan's initial teaser rate was only locked for five years. After that, the rate adjusts annually based on the index plus margin. So the real question wasn't whether I broke even on the refinance. It was whether I would still be in the house long enough for the savings to outweigh the reset risk. The calculator showed 22 months. Realistically, I should have been asking whether I'd be underwater or moving within six years of adjustment. I ended up walking away from that refi. The break-even number was technically correct, but it was the wrong question entirely.
The workaround was adding a holding-period check to the calculator. Before it spits out a break-even number, it asks how long you plan to stay in the property. If your estimated move date is before the break-even point, the tool flags it and shows you the net cost instead of the savings. That single addition prevented a dozen bad decisions I would have made otherwise. Most people miss a few things when they run these numbers themselves. First, they forget that property taxes and homeowners insurance often get baked into the escrow portion of the payment, and those can change independently of your interest rate. A $50 drop in principal and interest might look like a $50 monthly savings, but if your escrow payment went up $30 because your taxes were reassessed, your actual monthly out-of-pocket only dropped $20. The calculator needs to look at the total PITI payment, not just P&I. Second, people ignore the tax implications of mortgage interest deductions. If your new loan has less interest in the early years because the balance is lower, your tax benefit shrinks slightly. For someone in a high bracket, this can shave a few dollars off the perceived monthly savings, enough to push a marginal refi past its break-even point by a month or two. The effect is small but consistent.
Get the Full Details
Third and probably the most damaging error is not accounting for the original loan's remaining term. Refinancing from a 20-year loan that has 15 years left into a new 30-year loan might lower your monthly payment dramatically, but you are extending your debt by 15 years. The break-even calculator should show you the total interest paid over the life of both loans, not just the monthly comparison. Lower payments feel good. Higher total interest is the hidden cost. When I use a Mortgage Refinance Break Even Calculator, I always cross-check it against a side-by-side amortization schedule. The break-even number tells you when the refinance pays for itself. The amortization comparison tells you whether it was worth doing at all. Sometimes those two answers contradict each other. There are also edge cases where the entire concept breaks down. If you are in negative equity, the break-even calculation becomes irrelevant because you cannot refinance without cash-out or a special program. If your credit score is borderline and you qualify for a subprime rate, the savings might be so thin that the break-even period stretches past ten years, which is functionally meaningless. And if you are considering a no-documentation or stated-income loan, the closing costs run significantly higher, which inflates the break-even period in ways most basic calculators don't account for.
The calculator I built runs locally. No data leaves your machine. I chose that approach because financial calculators online increasingly harvest data for lead generation, and I got tired of filling out forms to see a number I could have computed in five seconds. The download link is below if you want to run it yourself. It is a standalone HTML file that opens in any browser, requires no internet connection, and handles the PITI adjustment and holding-period flag I mentioned earlier.
How the tool handles the common traps
The calculator does not assume your escrow stays flat. It asks for your current annual property tax and insurance amount and builds that into the comparison automatically. It also requires you to enter both loan terms so it can compute the total interest cost across both scenarios, not just the monthly difference. There is a checkbox for whether closing costs are paid out of pocket or rolled into the loan balance, and the tool adjusts the new loan amount accordingly before running the amortization. One thing it will not do is predict future rate adjustments on ARMs. That requires assumptions about index movements that no calculator can make with any accuracy. For ARMs, the tool calculates the break-even under the initial fixed period only and labels the result clearly as "initial period break-even," so you know you are looking at a snapshot, not a projection. If your situation involves anything beyond a standard conforming fixed-rate refinance, like jumbo loans, VA IRRML refinances, or FHA streamline loans, the closing cost structure varies enough that the generic tool may not capture all of it. In those cases, getting a Loan Estimate from at least two lenders and plugging the actual numbers in is the only way to get a reliable answer. The calculator is a screening tool, not a substitute for real quotes.

I have been running these numbers for probably twelve years now. The tools have not changed much, but the mistakes people make when using them have gotten worse, not better, because everyone assumes a calculator giving them a number means the decision is made. It is not. The calculator answers one narrow question. Whether you should refinance depends on several other questions it does not ask. Download the tool and test it against your own numbers before you hand them to a lender. You will catch more errors than you expect, and the lender will either confirm your math or reveal why theirs is different. Either way, you go into the conversation with something useful instead of a guess.