Understanding How Mortgage Calculators Actually Work in Practice
I spent most of my early career running numbers for clients who had no idea what their monthly payments would look like until they saw them on screen. The tools we used back then were spreadsheet-based and required manual adjustments every time a variable changed. Most people I worked with didn't understand why their payment jumped when interest rates shifted by half a point, or why their insurance estimate could make or break their qualification.
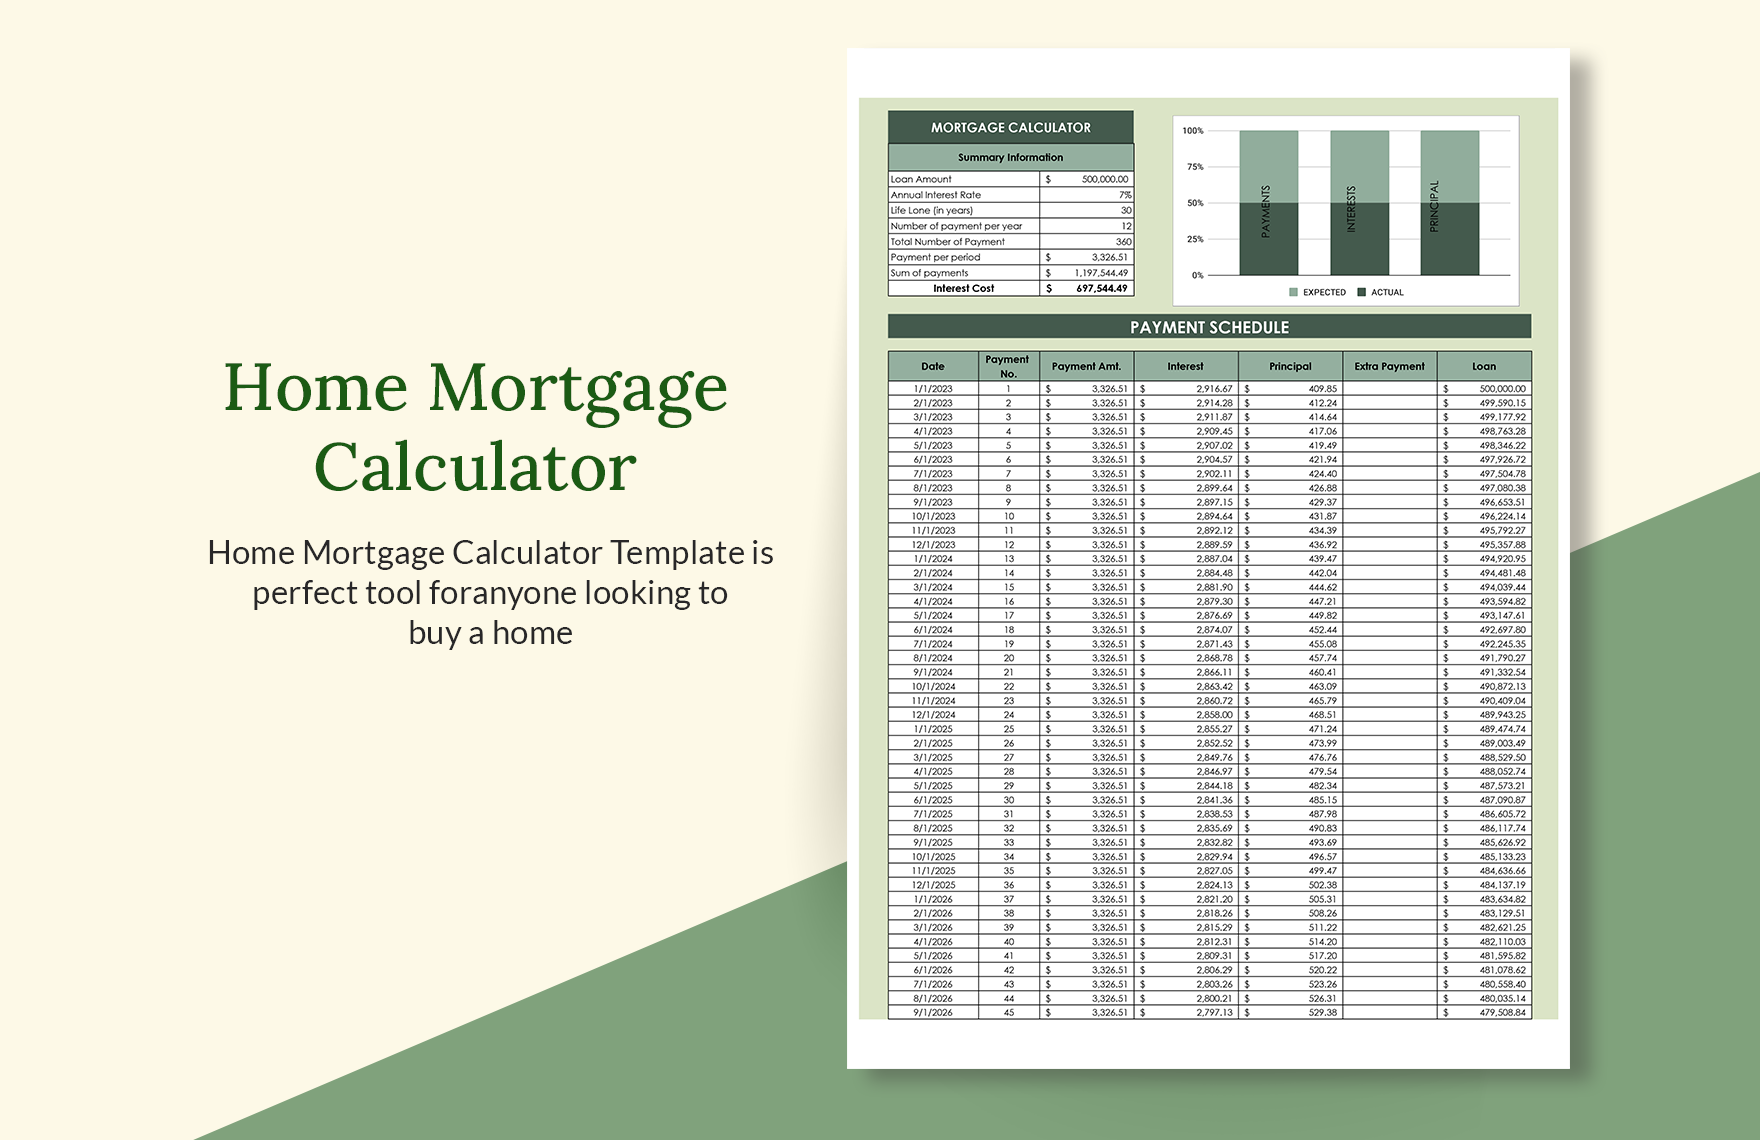
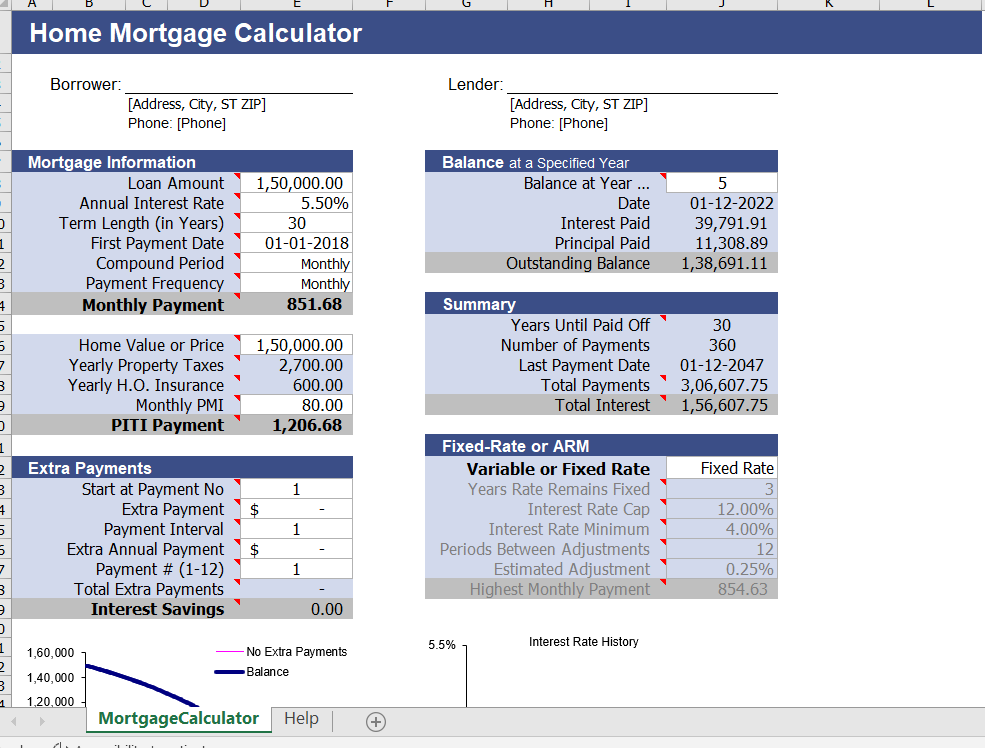
A Mortgage Selling Calculator is essentially a tool that models out the total cost of homeownership over time. It takes your purchase price, down payment, interest rate, loan term, and other recurring costs like property taxes and insurance, then projects what you will actually pay month by month. Some also factor in PMI, HOA fees, and maintenance reserves. The output is usually a monthly payment figure and a total lifetime cost number.
Using a Mortgage Selling Calculator for Real Transactions
The first time I used an automated calculator properly was around 2015 when a lender asked me to run comparative scenarios for a client considering both a conventional and an FHA loan. I had been doing these by hand using Excel templates that I inherited from a previous job. The new calculator processed everything in seconds and showed side-by-side comparisons of principal and interest, escrow components, and total interest paid over the life of each loan.
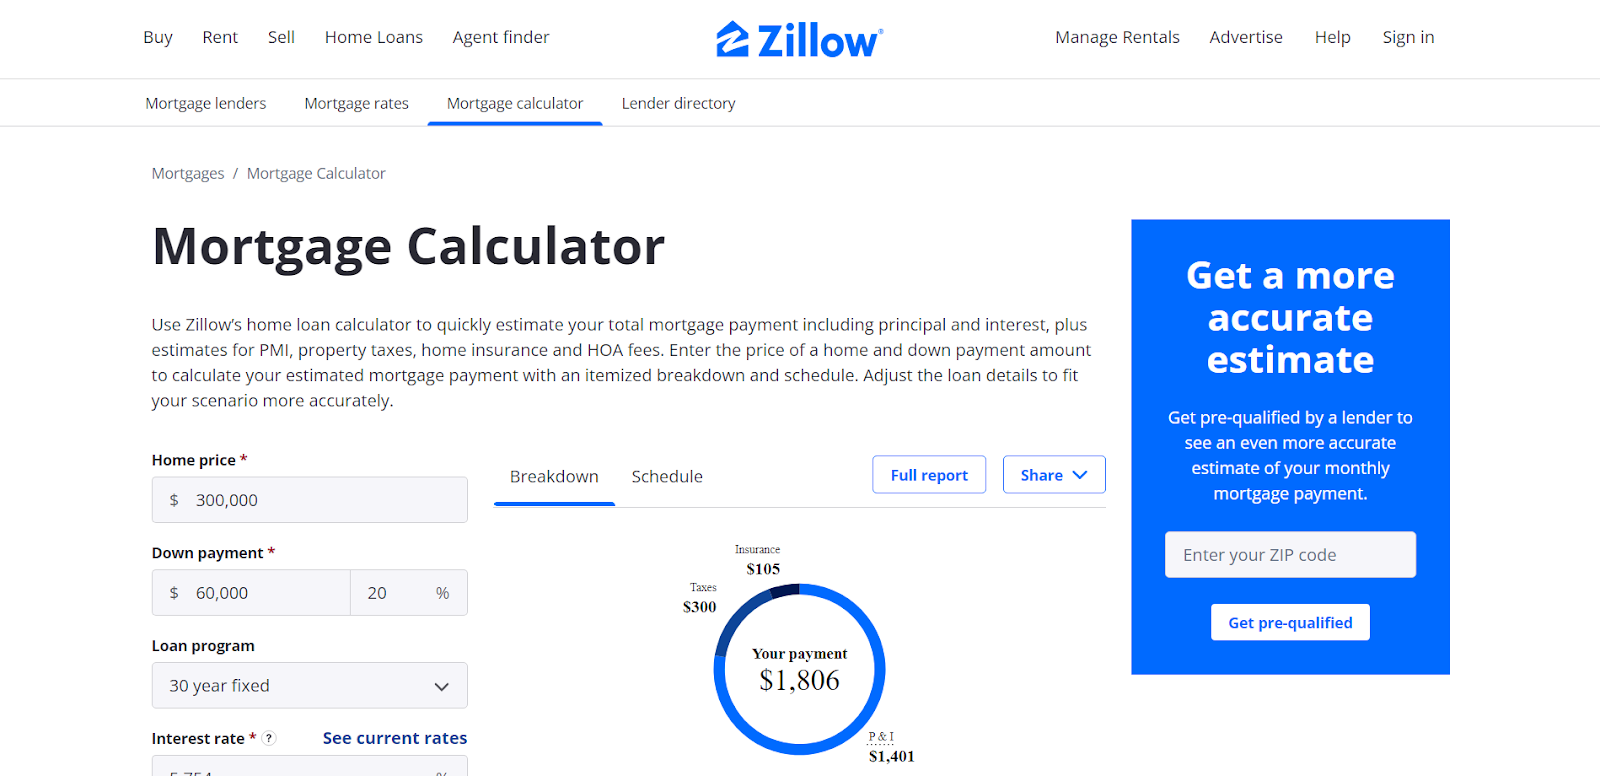
Here is what most calculators don't show you clearly upfront. They typically display the principal and interest portion in isolation, but the actual monthly payment includes escrow for taxes and insurance. That means your real payment could be 20 to 40 percent higher than the loan-only figure you see first. I learned this the hard way when a client showed up at my office confused because their bank statement said their payment was $2,100 and the calculator had only shown $1,600. We spent twenty minutes breaking down where the extra four hundred went.
Another thing nobody mentions until it bites you. Most online calculators use a simplified interest calculation that assumes your rate stays fixed for the entire term. In reality, if you have an adjustable rate mortgage, your payment can shift every one to five years depending on the index and margin. I had a client in 2018 whose ARM adjusted upward after year three, and her payment increased by almost three hundred dollars monthly. The calculator had never warned her about this possibility because it only modeled a fixed scenario.
The workaround I started using involved running both the base calculator and a separate amortization schedule manually. I would input the loan details into the calculator first, note the principal and interest figure, then add estimated property taxes based on local county records, homeowner insurance from a quick quote, and PMI if the down payment was under twenty percent. This usually took me about twelve minutes total and produced numbers that matched what lenders actually quoted within a fifty dollar range.
When Calculators Fail and What to Do Instead
There are several scenarios where even a good Mortgage Selling Calculator gives misleading results. One major limitation is that most tools do not account for closing costs unless you manually enter them. Closing costs typically run between two and five percent of the purchase price, and they affect your cash to close even though they do not change your monthly payment. I once watched a first-time buyer think she could afford a home because the monthly payment looked reasonable, then realize she did not have enough savings to cover the three thousand dollars in closing costs.
Another failure mode involves tax benefits. Many calculators show gross payments without adjusting for mortgage interest deductions or property tax deductions that lower your effective cost. In some states you can also deduct home equity loan interest, which further changes the real monthly expense. The calculator output is technically correct but financially incomplete.
My go-to alternative when the standard calculator seems unreliable is to pull the official Good Faith Estimate and Loan Estimate documents from the lender. These are federally mandated forms that show the exact fees, rates, and projected payments for your specific situation. I usually compare the calculator output against the Loan Estimate within forty-eight hours of submission to catch any discrepancies before they become problems.
Edge Cases That Break Most Calculations
I encountered a particularly annoying edge case in 2020 involving jumbo loans and hybrid adjustable rates. A client was looking at a $850,000 property with a 7/1 ARM. The calculator showed a monthly payment of $4,200 based on the initial five point five percent rate. What it did not show was that after year seven, the rate would adjust based on the SOFR index plus a two point margin. At that point, the payment could jump anywhere from $4,800 to $5,400 depending on where rates moved. I had to manually model three different rate scenarios and present them as a range instead of a single number.
Another problematic case involves properties in special assessment districts or flood zones. A client in Florida bought a home near a hurricane-prone area, and the calculator only factored in standard homeowner insurance. The actual premium was double because of flood zone requirements and windstorm coverage mandates. This added nearly $150 monthly to her payment and pushed her debt-to-income ratio above the lender threshold.
The lesson I took away from both cases is to treat any calculator output as a starting estimate rather than a final answer. Run the numbers through it quickly to get a ballpark figure, then validate against actual lender documentation and local cost data before making any decisions. The difference between an estimate and a reality check is usually about ten to fifteen percent, and that gap can make or break a purchase.
What to Look for in a Reliable Mortgage Calculator
Not all calculators are built the same. The ones I trust most include fields for property taxes by zip code, insurance estimates that adjust for location risk, PMI calculations based on down payment percentage, and HOA fee inputs. Some also let you choose between fixed and adjustable rates and show the adjustment schedule for ARMs. I avoid any calculator that only shows principal and interest without offering these additional components, because the numbers will always be incomplete.
A practical test I use is to enter the same loan into two different calculators and compare the results. If they differ by more than two percent, I investigate which one is including or excluding certain fees. Usually the more comprehensive tool wins, but there are exceptions where the simpler calculator is actually more accurate because it avoids rounding errors in the fine print.
The bottom line is that a Mortgage Selling Calculator is useful for quick estimates and comparison shopping, but it should never replace actual lender quotes or professional advice. Use it to get in the right neighborhood, then verify every number against documented costs before you commit to anything.
Gallery Mortgage Selling Calculator
Mortgage Calculator | Wix App Market | Wix.com
Mortgage Affordability Calculator Template in Excel, Google Sheets - Download | Template.net
Mortgage Calculator - Calculate Mortgage Repayments - Chosen Home
Top 20 Mortgage Calculator Tools In 2026 - Startup Stash
Mortgage Calculator Detailed at Steve Stults blog