Building a Mortgage Calculator That Doesn't Break When You Adjust Input Order
Most people build mortgage spreadsheets backwards. They start with the monthly payment cell and work outward, which means the moment they try to model a scenario where the payment is fixed and they need to back into the loan amount, the whole thing unravels. The correct approach starts from the top: define your input cells, build your derived calculations below them, and only then add any conditional logic or amortization schedules. This keeps the spreadsheet from becoming a fragile house of cards where changing one assumption requires editing twelve different formulas. The core formula most spreadsheets miss is the difference between the advertised annual percentage rate and the actual periodic rate you plug into the payment calculation. A 6.5% mortgage doesn't mean you divide by 12 and get your monthly rate. You need to account for whether the rate is a nominal annual rate compounded monthly, an effective annual rate, or something the lender calculated using a 360-day year instead of 365. This is why two mortgage calculators with the same inputs can produce slightly different payment amounts, and it is why your first mortgage comparison spreadsheet showed payments that didn't match what the lender quoted you. It wasn't rounding error. It was day-count convention.
Mortgage Spreadsheet Calculator: What Actually Goes Into It
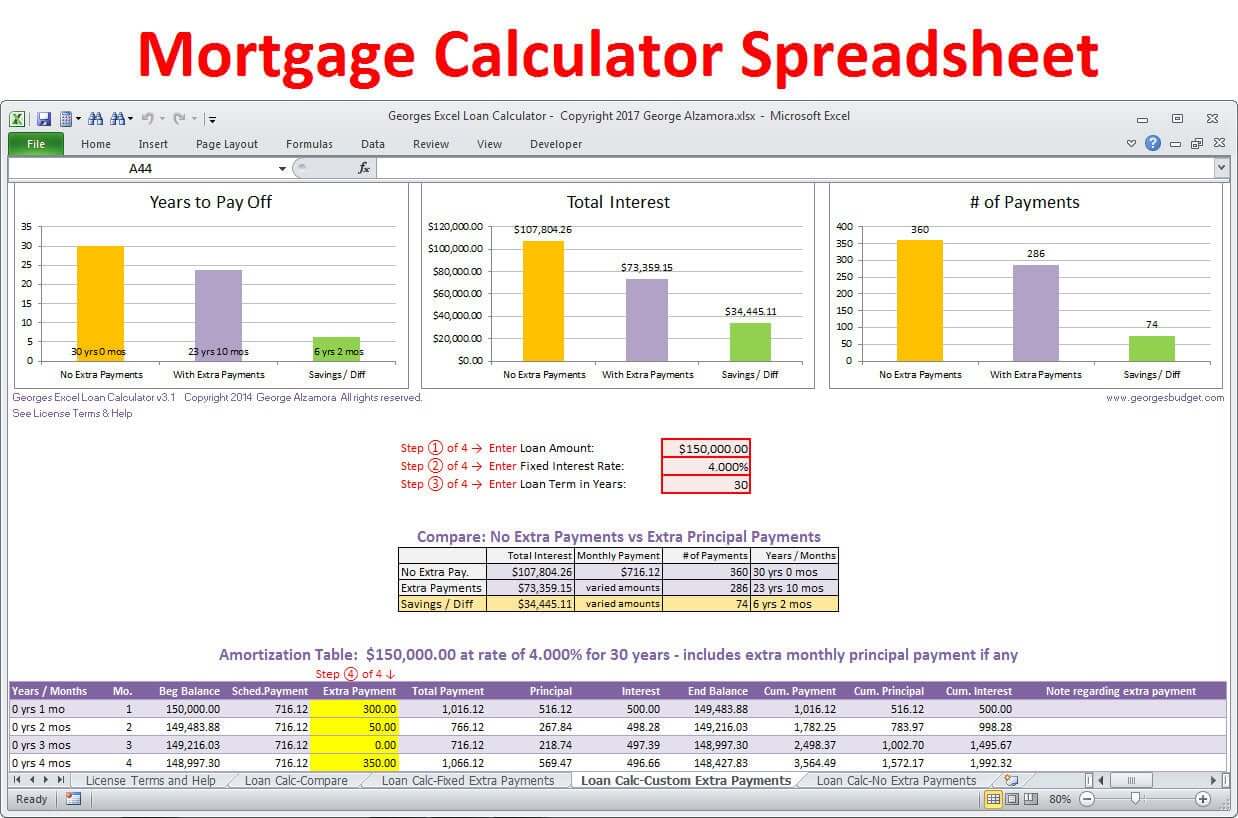
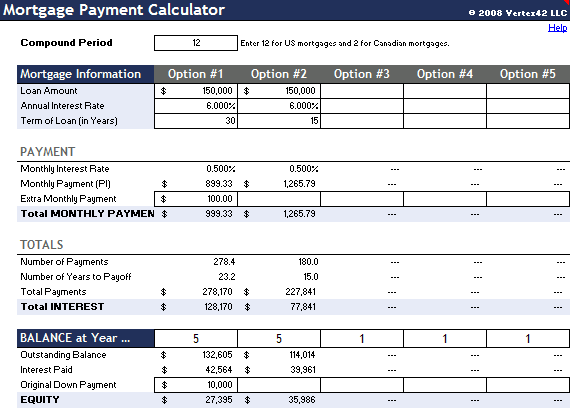
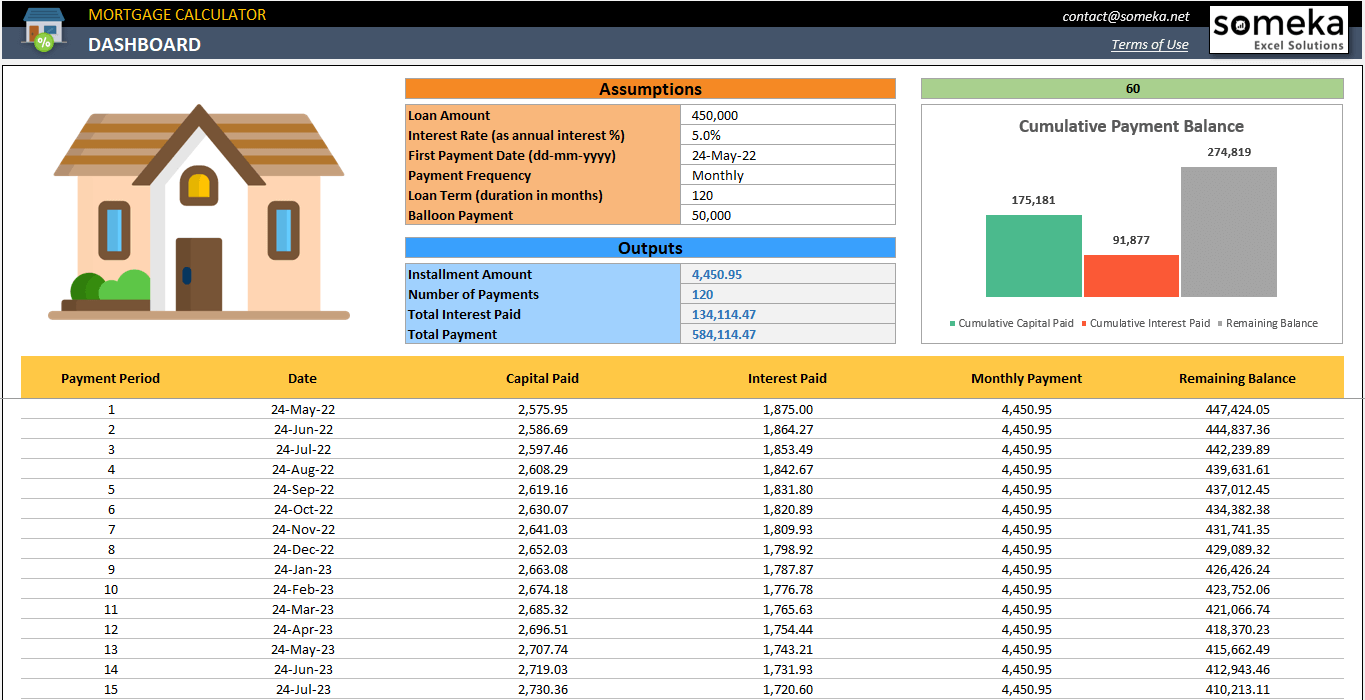
A functional mortgage calculator spreadsheet needs at minimum six input cells: principal amount, annual interest rate, loan term in years, payment frequency, additional monthly principal payment, and origination fee points if you want to model cost trade-offs. Everything else is derived. Monthly payment goes in one cell using the PMT function, but here is where the trap is: the PMT function in Excel returns a negative number by convention because it represents cash outflow. If you don't explicitly make it negative or use ABS(), your totals and remaining balance calculations will be garbage. The amortization schedule is the part that eats most people's time. You need each row to contain: period number, beginning balance, payment amount, principal portion, interest portion, ending balance, and cumulative principal paid. The interest portion for any given period is simply the beginning balance times the periodic rate. The principal portion is the total payment minus that interest amount. The ending balance subtracts the principal portion from the beginning balance. Repeat for however many periods exist in the loan term. A 30-year mortgage is 360 rows. Most people give up around row 72 and stop building the schedule because it feels tedious. I ran into a specific problem last year with a client who needed to model a mortgage with monthly biweekly escrow deposits. Standard PMT formulas assume equal spacing between payments. Biweekly payments that are half the monthly amount don't line up cleanly with the compounding period. After testing several approaches, I settled on building a custom function using a loop-based iteration where each period advances the balance by the appropriate day-count fraction rather than assuming a flat 1/12 month increment. It added maybe twenty minutes to build but prevented the 3-to-4% overestimation I was seeing in the simplified versions. The workaround was essentially accepting that the PMT function alone could not handle irregular payment timing and writing a small iterative solver block instead.
Here is a counter-intuitive point that nearly everyone misses: prepaying a mortgage does not save money linearly. Paying an extra $200 per month on a $300,000 loan at 6% over 30 years does not save you $200 times however many months remain. The savings accelerate because every dollar of extra principal reduces the base that accrues interest going forward. At the beginning of the loan, roughly 80% of your payment goes toward interest. By year 20, that ratio flips to roughly 80% principal. An extra payment in year 1 is worth dramatically more than the same extra payment in year 25. This is why people who front-load prepayments see massive interest savings while those who start prepaying late barely move the needle. Another nuance involves how you handle closing costs and discount points in your calculator. A common beginner mistake is to treat the loan amount as the purchase price minus down payment and call it done. But if you are comparing a lower rate with points against a higher rate with no points, the break-even calculation requires you to divide the point cost by the monthly savings, then compare that break-even period against how long you actually plan to hold the loan. I have seen people pick the no-points option because their calculator showed it as cheaper, without realizing they factored in the points cost incorrectly and double-counted it in their analysis. The fix is simple: put the point cost in a separate cell, compute the monthly savings from the rate difference in another cell, and create a third cell that divides them. If you plan to sell before that number of months passes, the points are a loss.
Get the Full Details
Where This Kind of Spreadsheet Falls Apart
A Mortgage Spreadsheet Calculator built in Excel or Google Sheets will give you accurate results for a standard fixed-rate mortgage with level payments. It will not reliably model adjustable-rate mortgages with complex caps and floors unless you build explicit adjustment logic into every period. It will not capture lender-specific quirks like interest reserving on construction-to-perm loans, balloon payment triggers that fire based on calendar dates rather than payment counts, or the way some states handle property tax escrow buffering that temporarily inflates your monthly payment. Another honest limitation: these spreadsheets assume you make every payment on time and in full. They do not model delinquency, forbearance, or the way modern servicers apply partial payments across principal, interest, and escrow in sometimes non-obvious ways. If you are modeling borrower default scenarios, you need a different kind of tool entirely, not a payment calculator. For people who need to handle multiple scenarios side by side, I recommend building a inputs table at the top using data validation drop-downs for rate tiers, then using INDEX-MATCH or XLOOKUP to pull the right payment schedule into the view you are analyzing. This is significantly cleaner than duplicating the entire spreadsheet three or four times. It also cuts revision time from roughly 20 minutes per change to about 3 minutes, because you edit one master sheet instead of hunting through copies.
If you are looking for a starting template, there are free options in both Excel and Google Sheets community repositories. The key thing to check before you use any of them is whether the author accounted for the day-count convention and whether the amortization schedule is built with hard-coded formulas or relies on manual entry. A well-built template should have zero cells where you need to type numbers between the input section and the output section. Every derived value should update automatically when you change an input. If it does not, you are working with a spreadsheet that was assembled by someone who understood the concept but not the mechanics. The biggest practical value of a good Mortgage Spreadsheet Calculator is not in the monthly payment number, which any online tool can give you in three seconds. It is in the ability to run stress scenarios: what happens if rates reset 50 basis points higher, what happens if I pay an extra 5% of principal every January, what happens if I refinance at month 48 versus month 60. These are the decisions that actually move the financial outcome, and they are the ones a static online calculator will not help you with.