Understanding the Moto Loan Calculator
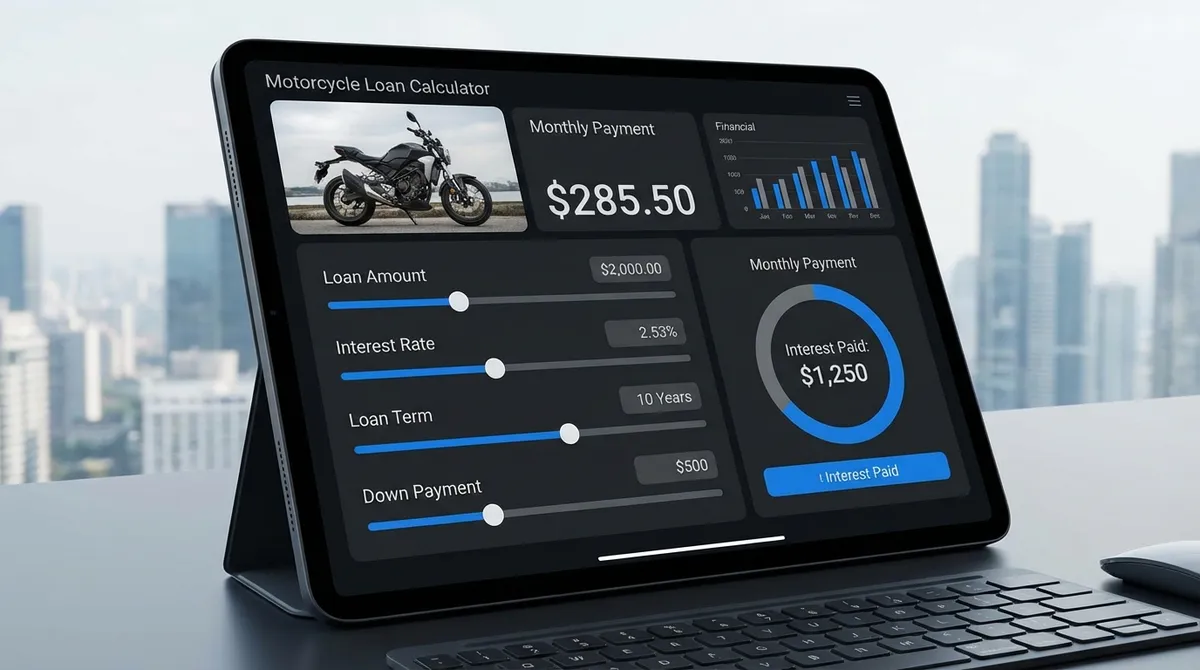
The Moto Loan Calculator is a straightforward tool used to estimate monthly payments, total interest, and overall cost for financing a motorcycle purchase. I've worked with dealerships, lenders, and customers who want to understand what they're actually signing up for before they commit. What most people don't realize is that these calculators vary significantly in accuracy depending on how they're built and what data they pull from. At its core, the calculator uses the standard amortization formula. You enter the loan amount, annual interest rate, and term length, and it spits out your monthly payment. That's the surface level. The real complexity shows up when you factor in taxes, registration fees, dealer markups, and whether the rate is fixed or variable. Most free online calculators ignore all of that, which is why the numbers they give you rarely match what you actually pay at closing. I ran into this issue recently with a customer who was comparing quotes from three different lenders. The online calculators showed monthly payments ranging from $210 to $245, but when he actually got the paperwork, his payment landed at $267. The discrepancy came from the fact that two of those lenders included pre-paid finance charges and an origination fee that the calculator never accounted for. Once we built a spreadsheet that included every line item on the Loan Estimate form, the real cost became obvious within about ten minutes.
What Makes a Good Moto Loan Calculator
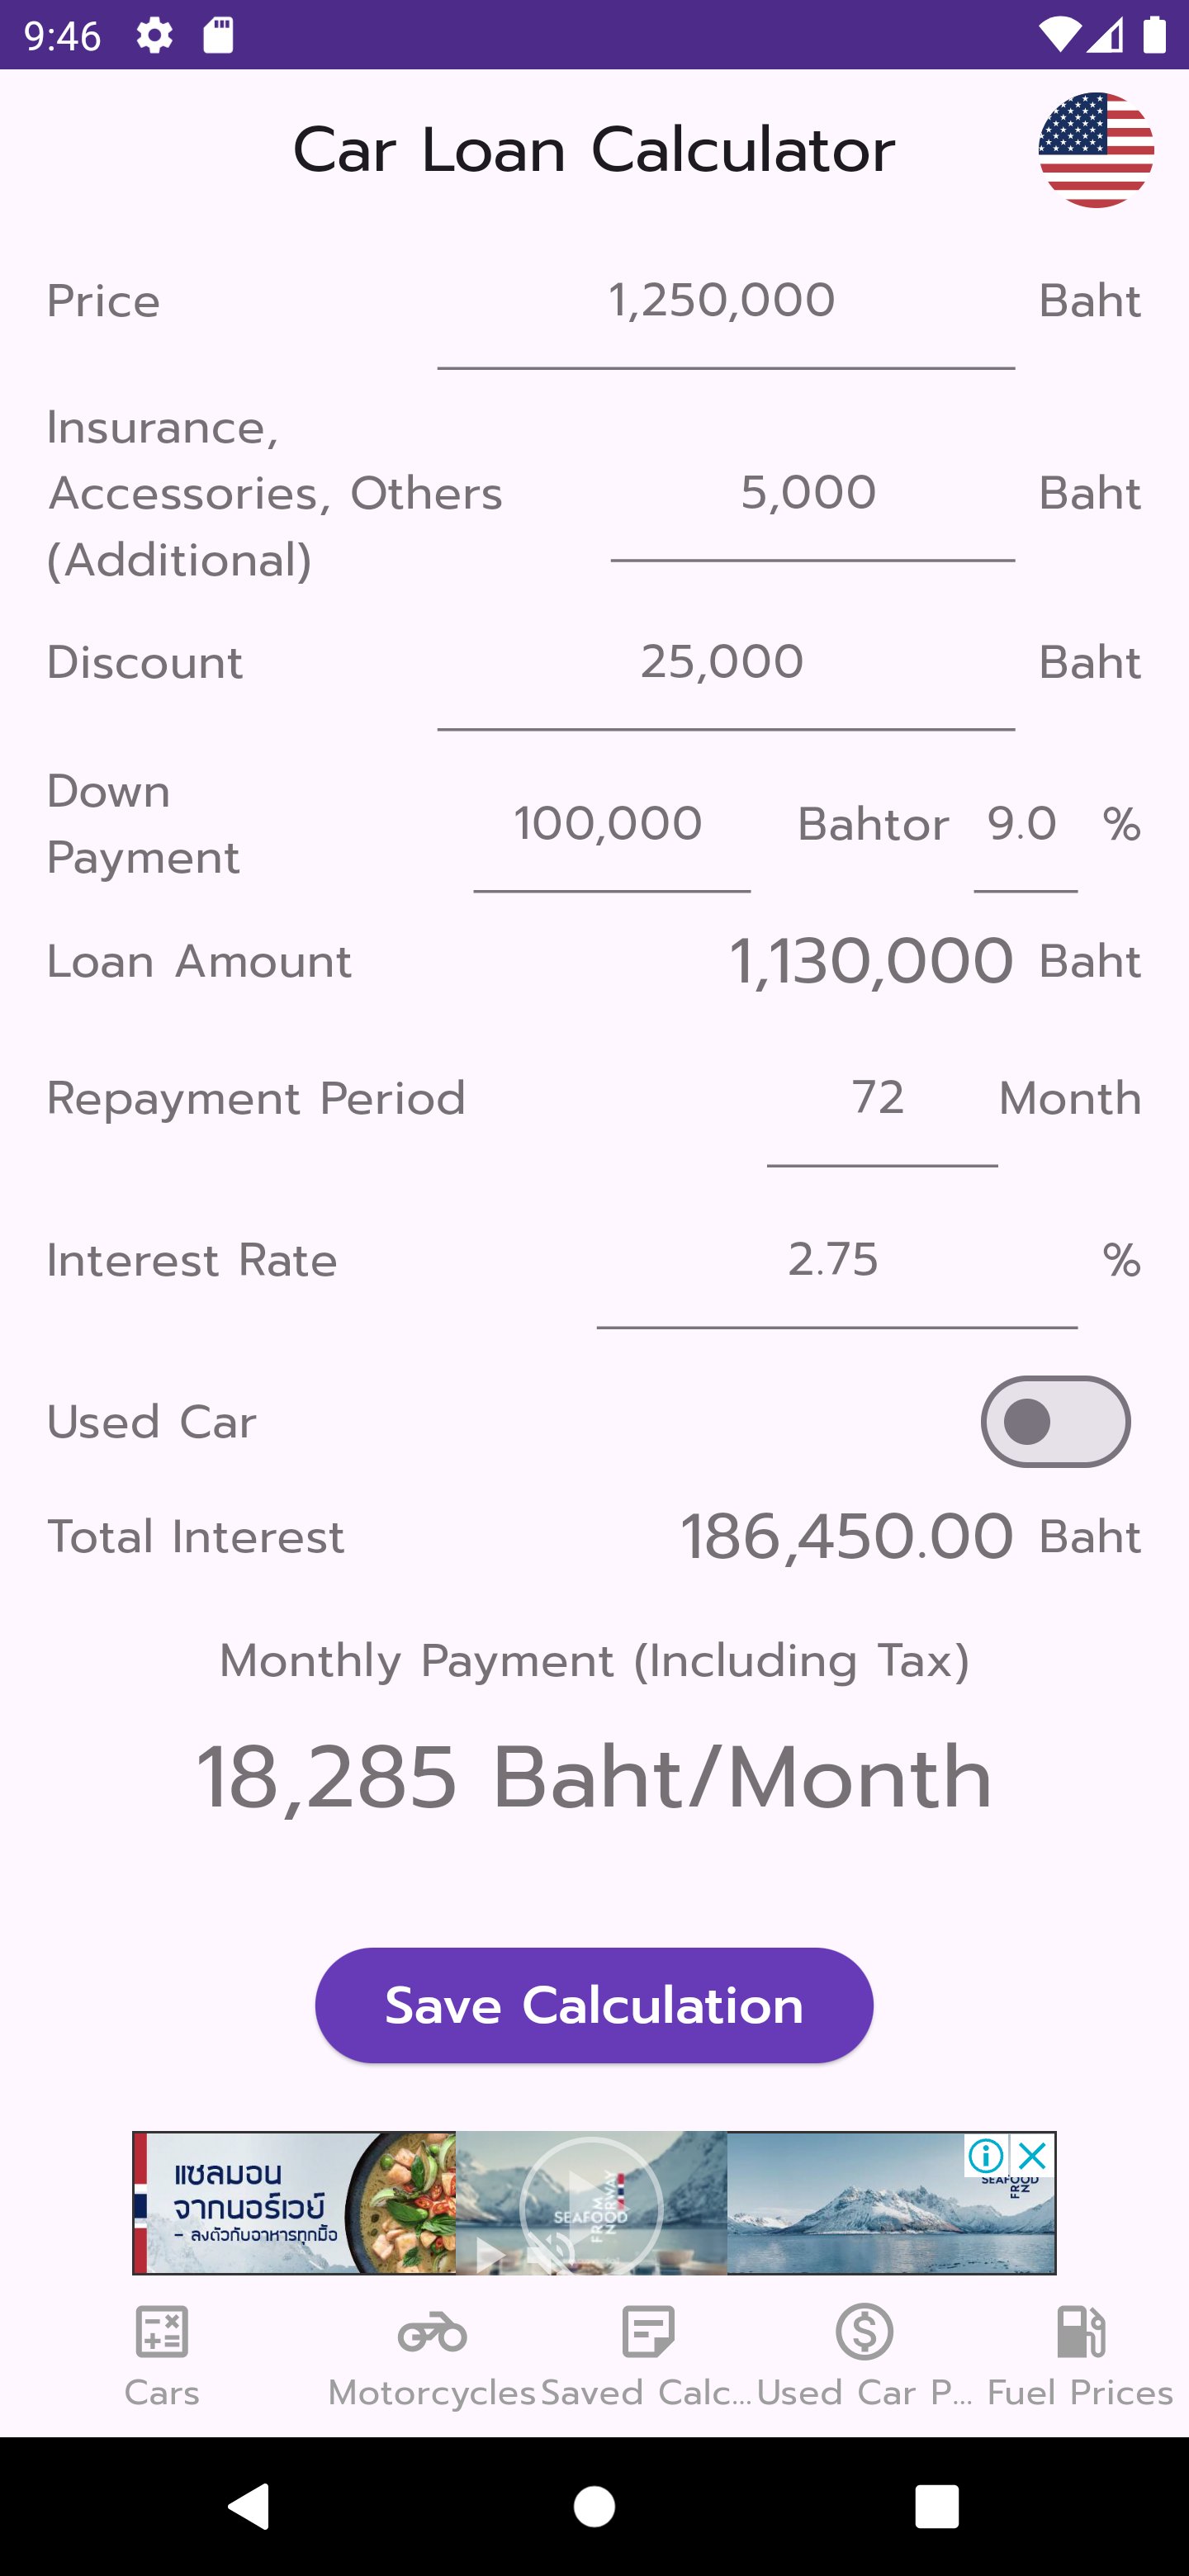
A proper calculator needs to handle more than just principal and interest. It should let you input the down payment as either a fixed dollar amount or a percentage of the motorcycle's price. It should factor in sales tax based on your state, since that directly increases the financed amount if you roll it into the loan. And it needs to show you the total interest paid over the life of the loan, not just the monthly number. That last part matters because most buyers fixate on the monthly payment and miss the fact that a longer term can cost thousands more in interest even though the payment looks comfortable. There's also a common misconception about how balloon payments work in motorcycle financing. Some lenders offer structured loans with a large final payment that's supposed to be refinanced. The calculator needs to account for that scenario explicitly, otherwise you're looking at a payment schedule that makes sense on paper but falls apart when you get to the payoff date and the balloon payment comes due with nothing to cover it. I've seen this trap cost people several hundred dollars in additional fees when they tried to extend instead of pay off.
Common Pitfalls When Using Any Moto Loan Calculator
The biggest issue I see is people entering the motorcycle's sticker price instead of the actual negotiated price. The calculator will work perfectly fine with whatever number you feed it, but if that number is inflated by add-ons like extended warranties, tire and wheel protection, or gap insurance that got bundled into the loan amount, your payment estimate will be way off from reality. These products can add anywhere from eight hundred to three thousand dollars to the financed balance depending on what the dealer pushes. Get the out-the-door price first, then run the numbers. Another problem is the assumption of a single interest rate throughout the loan term. Some promotional rates are only available for the first six to twelve months and then reset to a higher standard rate. A basic calculator won't catch this unless it supports tiered or adjustable rate inputs. If you're looking at a zero percent promotional offer, verify the reset rate before you assume the monthly payment stays low for the full term. The payment will jump significantly once the promotional period ends. There's also the question of whether the calculator handles prepayment correctly. If you plan to make extra payments toward principal, most standard calculators don't reflect how that changes your payoff timeline or total interest cost. I built a custom Excel model that lets you input irregular prepayment amounts and shows the recalculated schedule after each one. It took about an hour to set up initially, but it paid for itself within the first month of use when I could quickly show customers how an extra hundred dollars a month would cut two years off their loan term and save them over a thousand dollars in interest.
Get the Full Details
Limitations You Should Know About
No calculator, whether free or paid, can give you an exact quote. The numbers are always estimates. Actual approval depends on your credit score, debt-to-income ratio, employment history, and the lender's internal guidelines. A calculator might show you a payment of $195 per month at 5.9 percent APR, but your real rate could be seven percent or higher depending on your credit profile. That difference of eleven percentage points can change your monthly payment by more than thirty dollars and add over nine hundred dollars to the total cost of the loan. Additionally, some lenders include annual or monthly service fees that aren't reflected in standard calculators. A five-dollar monthly maintenance fee sounds negligible but adds sixty dollars a year to your cost. Over a four-year loan term, that's two hundred and forty dollars you never saw coming. Always ask the lender for the full fee schedule before relying on any calculation. If you're dealing with a complex situation like a subprime loan, a co-signer arrangement, or a trade-in with negative equity, a standard calculator won't give you useful numbers. In those cases, the best approach is to get pre-approved directly from a credit union or online lender and work from their actual quoted terms rather than running estimates through any generic tool.
Building Your Own Simple Moto Loan Calculator
If you want something more reliable than a random website calculator, a simple spreadsheet is all you need. Set up columns for the purchase price, down payment, sales tax, trade-in value, loan amount, annual interest rate, and loan term in months. Use the PMT function in Excel or Google Sheets to calculate the monthly payment, then add columns for total payments, total interest, and total cost. It takes about fifteen minutes to build and you'll have full control over what inputs you include. I've had customers who switched from online calculators to their own spreadsheets after realizing the websites were feeding them incomplete data, and the time savings from being able to run multiple scenarios quickly made it worthwhile. The important thing is to treat any calculator output as a starting point for negotiation and planning, not as a binding commitment. Get the actual numbers from the lender in writing before you sign anything. The calculator tells you what the loan should look like. The paperwork tells you what it actually is.