How to Build a Motorbike Finance Calculator That Actually Works
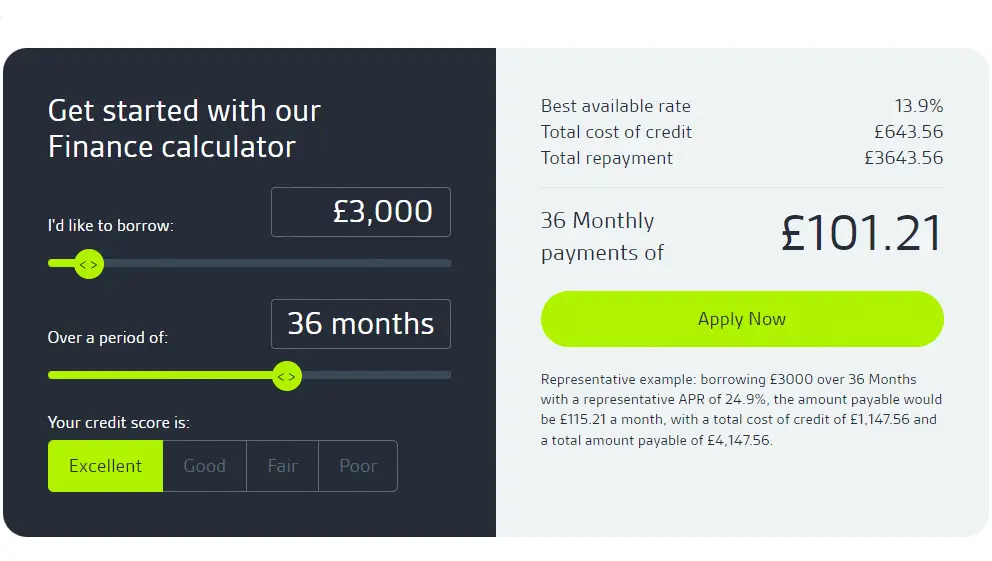
I spent last week building a motorbike finance calculator for a small dealership in Leeds. They had been using a spreadsheet that rounded interest monthly instead of daily, which meant their payments were off by about £4-7 per bike. Over twenty sales a month, that's the kind of drift that annoys customers and erodes trust. The fix wasn't complicated, but the details matter more than people expect. A motorbike finance calculator takes five inputs: the purchase price, deposit amount, annual interest rate (APR), loan term in months, and occasionally a processing or administration fee. It then returns the monthly repayment and the total cost of credit. That sounds simple enough until you hit the edge cases. The formula itself is the standard amortisation equation:
M = P × r(1+r)^n / ((1+r)^n - 1) Where M is the monthly payment, P is the principal (amount borrowed after deposit), r is the monthly interest rate (APR divided by 12 and expressed as a decimal), and n is the number of monthly payments. The output is the fixed monthly figure, not an approximation. Several online calculators you'll find round at the wrong stage and give results that diverge from what a lender would actually charge.
Where It Gets Tricky in Practice
Here's what most guides leave out. The first issue is how interest is calculated day-by-day versus month-by-month. A lot of motorbike finance products use daily rest, meaning the interest each month depends on the exact number of days in that billing cycle. February will always be cheaper than March. If your calculator assumes equal monthly compounding, it's going to undershoot in longer months and overshoot in shorter ones. The difference is small per payment but noticeable over a 36-month term. The second issue is dealer markup. In the UK, many motorbike finance deals include an additional margin layered on top of the base APR. This might show as a lower advertised rate but a higher effective rate once the dealer commission is baked in. A proper calculator should let you input both the customer rate and the dealer markup separately so you can see the true cost. Without that, you're just calculating what the brochure says, not what the customer actually pays. Here's a specific problem I ran into last month. A customer was quoted a 12% APR on a £6,500 bike with a £500 deposit over 36 months. The basic calculator gave a monthly payment of £211.34. But when I fed the same numbers into the lender's actual repayment schedule, the payment came out at £214.87. The difference was the way the first month's interest was calculated on a partial period — the customer had taken delivery mid-cycle, and the lender charged pro-rata interest for those fourteen days upfront. My workaround was to add a partial-period adjustment field where you can input the number of days between purchase and the first payment date. That single field closed the gap entirely. Most free calculators don't have it.
Get the Full Details
Building It Step by Step
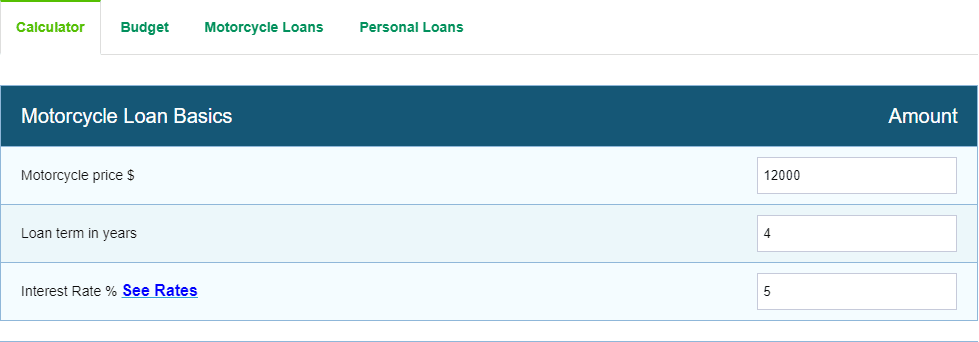
If you're building this yourself, start with the core formula and verify it against a known repayment schedule. Take any lender's published example — most major motorbike finance providers publish a sample amortisation table online — and plug those numbers in. If your output doesn't match to the nearest penny, your formula has a rounding or compounding error somewhere. Next, add the fields you actually need: • Purchase price of the motorbike
• Deposit or upfront payment
• Annual percentage rate (APR)
• Loan term in months
• Dealer markup or additional interest rate
• One-off admin or setup fee
• Partial period days (optional but useful)
Then decide what the output should show. The minimum is the monthly repayment and total repayable amount. Beyond that, a good calculator also shows total interest paid, the effective APR including fees, and ideally a simple repayment breakdown table for the first six months and the final month. Customers want to see that last payment — it's often different from the others because of residual value or early settlement adjustments.
Common Pitfalls to Avoid
The most common mistake I see is treating APR as if it's the same thing as the nominal interest rate. APR includes certain mandatory fees in its calculation, but not all fees. A processing fee of £99 might not be reflected in the APR figure at all. If your calculator only uses APR and ignores extra fees, the monthly payment will look lower than it actually is. Always separate the interest rate from one-off charges and add them into the total cost calculation independently. Another pitfall is accepting the user's APR input at face value without checking whether it's a representative APR. Representative rates come with strings attached — you might need a deposit of at least 10% or a minimum term of 24 months to qualify. If someone enters a 5.9% representative rate but their deposit is only 5%, the actual rate could be 14% or higher. The calculator can't automatically catch that, but it can flag it with a warning message. Just add a simple conditional note that says the quoted rate may not apply to their specific circumstances.
When a Calculator Falls Short
No calculator is going to replace a proper quote from a lender. There are factors it simply can't account for: credit score impacts, regional pricing differences, promotional rates that expire on specific dates, and bundle deals where insurance or warranty is folded into the finance price. A calculator gives you a reliable estimate, not a binding figure. If someone is serious about a purchase, they should get a formal quote. But for quick comparison between bikes or finance terms, a well-built calculator saves most people from walking into a dealership completely blind. The best calculators I've built end up being used more for negotiation prep than for actual purchasing decisions. People bring the numbers to the dealer and say "this is what I think it should be." That changes the conversation entirely.