Understanding how motorcycle financing actually works when you spread payments out
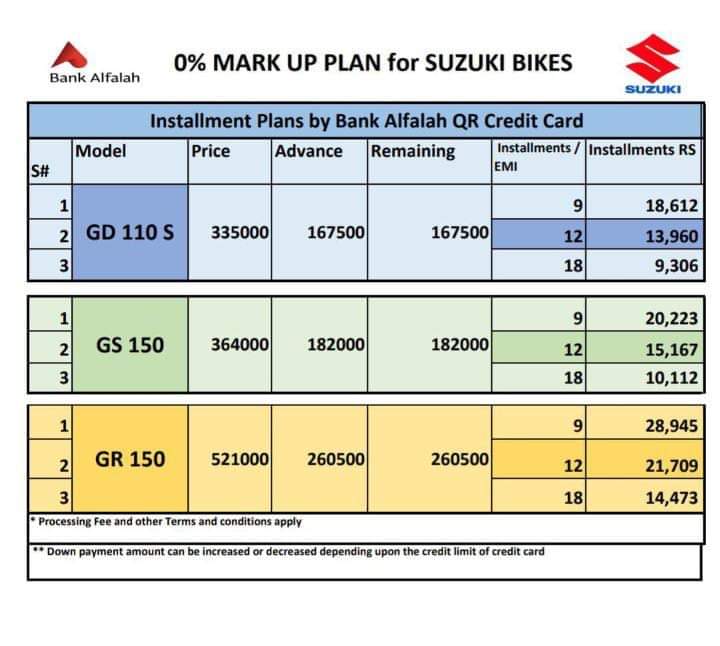
A lot of people browsing motorcycle financing options don't realize that monthly payment plans for bikes are not one single product. There are several structures that get lumped together under the same label, and they behave very differently depending on the lender, your credit profile, and what kind of bike you are buying. I have seen people walk into dealerships expecting one thing and sign for something entirely different. The term Motorcycle Pay Monthly typically refers to any structured financing arrangement where you repay a motorcycle purchase in fixed periodic installments rather than paying upfront. This includes dealer-arranged loans, credit union auto-style loans, secured personal loans, and increasingly, buy-now-pay-later platforms that have expanded into powersports. The payments themselves are usually calculated on a 36 to 72-month schedule, though some lenders offer terms as short as 12 months or as long as 84 months on larger purchases. What most people miss is that the monthly amount you see advertised is rarely the total cost of borrowing. It is the principal plus interest divided by the number of payments, but the interest rate applied depends entirely on your credit tier. A rider with a 720 FICO score might lock in 5.9 percent APR on a new sportbike loan, while someone at 620 could be looking at 14.9 percent on the same bike from the same dealer. That is not a typo. Dealer financing often applies rate tiering based on credit score at the point of sale, and the difference between those two rates on a $12,000 loan over 60 months is roughly $1,400 in total interest paid.
I ran into this exact issue a few years ago when I was helping a friend finalize his purchase. The dealer quoted him a monthly payment that looked reasonable at first glance, but when I asked to see the full amortization schedule before he signed, the APR came out to 18.2 percent because his credit had a recent collection account from four years ago that was still dragging his score down. We ended up skipping the dealer financing entirely and went straight to his local credit union instead. They offered him 8.4 percent APR on a 48-month term. The monthly payment was about $40 higher, but the total interest over the life of the loan was less than half of what the dealer was proposing. He saved roughly $1,800 without even realizing it at the time. The workaround was simple but not obvious to someone who had never financed a vehicle before: never let the dealer present the monthly payment as the primary talking point. Ask for the annual percentage rate and the total amount repaid at signing. If they hesitate or push back, that is your answer about whether the deal is actually favorable. Dealers know that monthly payment is more salient to buyers than APR, so they tend to lead with it deliberately. There are a few structural details that matter more than most buyers understand. Secured loans using the motorcycle as collateral will always carry a lower rate than unsecured personal loans, but they also mean the lender can repossess the bike if you default. Some financing products include gap coverage by default, which pays the difference between what you owe and what the bike is worth if it is totaled within the first year. Others charge extra for it. Check your contract line by line. One lender I worked with recently tacked on a $349 gap protection fee that was completely optional and could have been declined at signing without any impact on approval.
Another thing that catches people off guard is prepayment penalties. Most standard auto and motorcycle loans in the US do not have them, but a few subprime lenders still do, and they can charge up to 2 percent of the remaining balance if you pay off the loan early within the first 36 months. If you know you will be in a position to clear the debt ahead of schedule, either avoid those lenders outright or factor the penalty into your comparison math. A 7 percent rate with a prepayment penalty can end up costing more than a 9 percent rate without one if you pay off in year two. Down payment expectations also vary widely by lender tier. Prime lenders typically want 10 to 20 percent down. Subprime lenders may accept zero down but will inflate the interest rate to compensate. Cash-flow-conscious buyers sometimes prefer zero-down options even at higher rates because they need to preserve liquidity for registration, insurance, and maintenance costs that hit immediately after purchase. This is a valid strategy as long as the math works in your favor over the full term. The application process itself is straightforward if you come prepared. You will need a government-issued ID, proof of income for the last 30 days, your current address verification, and a list of existing debts. Online prequalification tools from major lenders can give you a soft credit pull estimate in about 10 minutes, which tells you your likely rate range without affecting your credit score. I recommend running prequalification through two or three lenders before visiting a dealership so you can walk in with leverage. A dealer has less room to offer favorable terms when you already know what the market is giving you.
Get the Full Details