How Motorcycle Payments Actually Work
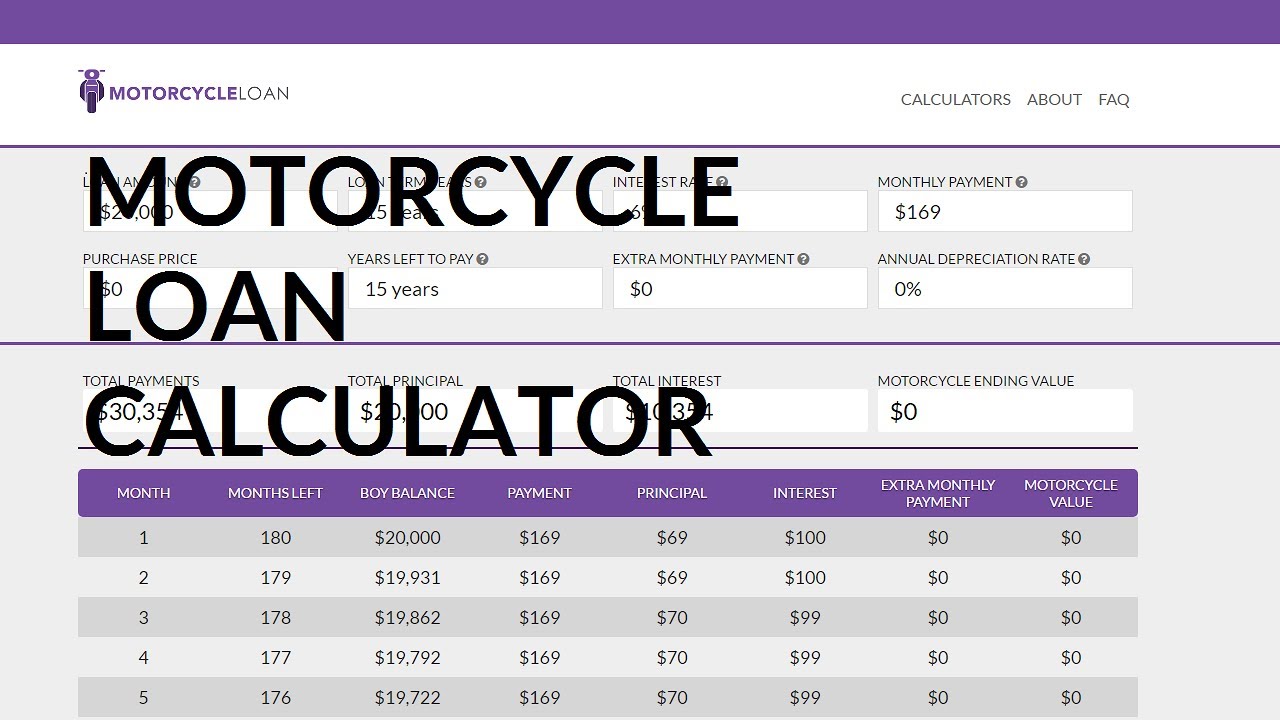
A motorcycle payment estimator is just a calculator that takes your price, down payment, interest rate, and loan term and spits out a monthly number. The math behind it is the standard amortization formula lenders use everywhere. Most free online calculators get the core result right, but they miss a bunch of small things that change your actual payment by fifty or a hundred dollars a month. I spent years working dealer floor finance, so I see people come in with numbers from these calculators and then get confused when their real payment doesn't match. It happens every single week. The gap is usually in fees, taxes, and the way the loan is structured, not in the calculator itself.
Using a Motorcycle Payment Estimator Correctly
The basic inputs you need are straightforward. You need the total price of the bike including any dealer fees you can't roll into the loan separately, your down payment amount, the annual interest rate the lender is offering, and the loan term in months. Enter those four things and hit calculate. That gives you the base principal and interest payment. Here is where most people cut corners. They leave out sales tax, title and registration fees, and any dealer documentation charges. Some calculators let you add those in as an optional field. If yours doesn't, add them manually to the loan amount before you run the numbers. A $12,000 bike with an 8 percent sales tax and $400 in fees isn't a $12,000 loan. It is closer to $13,360 if you roll everything in, and that changes the payment enough to matter. The interest rate is another area where people get tripped up. The rate you see advertised, say 5.9 percent, might be a promotional rate that only applies for the first twelve months. After that it jumps to 11.9 percent or higher. Most estimators don't handle tiered rates. If you are looking at a deferred interest or buy-here-pay-here deal, the calculator output is going to be wrong for half the loan. Pull the actual contract terms first and work from those numbers.
Loan term matters more than people think. A thirty-six-month loan and a sixty-month loan on the same bike with the same rate will give you very different total costs even though the monthly payment looks cheaper. The thirty-six-month loan on a $10,000 bike at 7 percent comes out to about $308 a month. The sixty-month version is around $198 a month. That feels like a huge relief every month, but you end up paying roughly $730 more in interest over the life of the loan. Longer terms also mean you stay underwater on the bike longer since motorcycles depreciate fast in the first two years.
Get the Full Details

What the Calculators Get Wrong
I ran into a specific issue last year that nobody seemed to address in any tool I could find. A customer came in wanting to estimate the payment on a used sportbike. He had a trade-in worth $2,500 and wanted to apply it toward the price. The problem was the dealer was advertising the bike at a price that already included the trade credit as a discount, so his actual out-the-door price was lower than the sticker. When he plugged the sticker price into an online estimator, the payment came out way higher than what he was actually quoted. The workaround was simple. I had him subtract the trade value from the out-the-door price first, then feed that net amount into the calculator along with the actual rate and term the lender quoted. Took about two minutes once you knew what was happening. Another common trap is the difference between add-on interest and true amortized interest. Some subprime lenders, especially the buy-here-pay-here shops, quote an "interest rate" that is actually a flat fee added to the principal and then divided evenly across the payment schedule. This makes the effective annual rate much higher than what they tell you. If a lender says they charge 18 percent add-on interest, the real APR is closer to 33 percent. A Motorcycle Payment Estimator using standard amortization math will show you a payment of maybe $450 a month, but the real cost is significantly worse. You have to ask the lender directly whether their rate is add-on or amortized. If they hesitate, that is your answer. GAP insurance is another thing these calculators ignore. If you total your bike in the first year, you owe the full remaining loan balance even though the bike is worth far less. GAP coverage costs extra each month or as a one-time fee added to the loan. It is not included in any payment estimate you will find online unless you specifically add it. Factor it in if you are putting a small down payment or rolling fees into the loan.
Pitfalls to Watch For
Pre-approval does not lock in the rate you see on a calculator. The estimated payment from any tool is just an estimate. The final number depends on your credit score at the time of application, the lender's current programs, and whether you qualify for any dealer incentives. I have seen people walk in with a payment estimate from home that was $40 lower than what they were actually offered because their credit had shifted in the meantime or because they did not qualify for the promotional rate that was used in the calculation. The biggest mistake I see is people focusing entirely on the monthly payment instead of the total cost. A $200-a-month payment looks great until you realize it is over sixty months with a high rate and a lot of rolled-in fees. The same bike on a shorter term with a better rate and a bigger down payment might cost $320 a month but save you over a thousand dollars in interest. Run both scenarios through the estimator and compare total cost, not just the monthly number. Some online tools also use the wrong day-count convention. Most auto loans use a 30/360 method, meaning they assume thirty days per month and three hundred sixty days per year. A few lenders use actual/365, which gives a slightly different daily interest amount. The difference is small but noticeable if you are paying close attention. It usually shows up as a few dollars variation in the first payment and a dollar or two per month over the life of the loan. Nothing catastrophic, but worth knowing if you are comparing offers from different lenders.
If you want something faster than clicking through multiple online forms, a simple spreadsheet with the PMT function in Excel or Google Sheets does the same thing and lets you adjust every variable on the fly. The formula is =PMT(rate/12, terms, -loan_amount). Plug in your numbers, change the term or rate, and see the payment update instantly. No sign-up, no pop-ups, no asking for your email address. There is no perfect free calculator out there that handles every edge case. They get the base payment right and that is useful for a quick sanity check. Beyond that, you need to understand what is missing and adjust the inputs yourself. Add the taxes and fees. Verify the rate type. Check the term. Compare total cost across scenarios. Do that and the numbers you walk into the dealership with are actually close to the numbers on the contract.