The mechanics of combining different asset classes into one workable portfolio
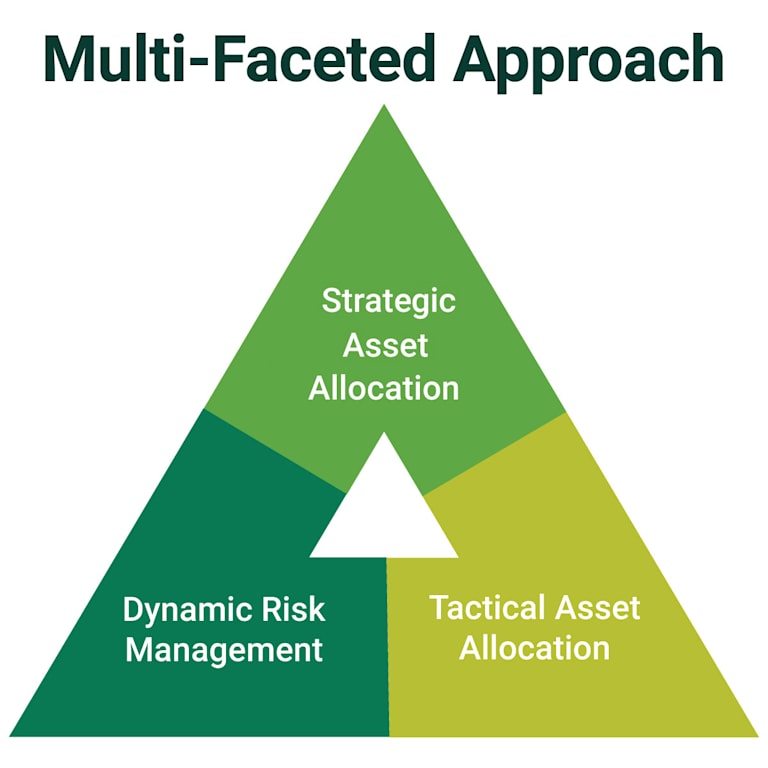
Picking individual assets is straightforward. The hard part is deciding how to weight them, rebalance them, and keep them from drifting into a configuration that contradicts your actual risk appetite. Most people treat multi-asset as a simple allocation exercise. It is not. It is a system of interacting constraints. At its core, a multi-asset strategy sits at the intersection of portfolio construction, risk management, and tactical execution. You are allocating capital across at least two uncorrelated or weakly correlated asset classes — equities, fixed income, commodities, real assets, sometimes private markets or derivatives overlays — and managing the portfolio as a single risk unit rather than a collection of siloed positions. The word "solutions" in the title usually signals that someone is packaging this into a service offering rather than building it from scratch. The actual setup involves three layers. First, a strategic base allocation that defines your long-term positioning. Second, a tactical overlay that adjusts exposure based on shorter-term signals or regime shifts. Third, a risk management framework that monitors correlation drift, concentration, and drawdown triggers across the entire portfolio simultaneously. Skip any one of those and the strategy develops blind spots.
How to build it from scratch
Start with your universe. Define what assets are actually available to you and under what conditions. This is where most retail and even mid-tier institutional approaches fail — they pick asset classes based on historical performance tables rather than liquidity, execution feasibility, and tax treatment. I built a multi-asset model once for a small fund that included EM debt, global equities, gold, and a managed futures CTA overlay. The backtest looked clean. The live execution was a mess because the EM debt positions required cross-border settlement structures I had not accounted for, and the rebalancing timeline got eaten by custody transfer delays. We lost about three weeks of positioning and entered the rally late. The workaround was building an execution schedule into the model itself rather than treating rebalancing as a separate manual step. We mapped every trade to a standard settlement window, added a buffer for custodial lag, and routed the more illiquid positions through a different broker altogether. The adjusted slippage estimate came in at about 12 basis points per rebalance instead of the 4 we had originally assumed. That changed the expected return profile significantly.
Rebalancing methodology matters more than most people think
A static calendar rebalance — say, quarterly — sounds simple but creates problems during volatile periods. When correlations spike upward, which they do in stress events, your risk contribution shifts dramatically within weeks, not quarters. A volatility-targeting rebalance adjusts more frequently but can generate excessive turnover. The middle ground most professionals land on is a hybrid: rebalance on a calendar schedule but trigger additional adjustments when any single asset class deviates beyond a predefined band from its target weight. I typically use a 5 percentage point band for major allocations and 3 points for satellite positions. This keeps turnover reasonable without letting the portfolio drift too far from its intended risk profile. You also need to decide whether rebalancing is symmetric or asymmetric. Symmetric means you rebalance regardless of direction. Asymmetric means you only rebalance toward your target when conditions justify it — which basically means you hold onto outperforming assets longer and cut underperformers sooner. Asymmetric rebalancing tends to improve risk-adjusted returns in trending markets but can leave you overexposed during mean-reversion regimes.
Get the Full Details
Correlation is the hidden variable everyone underestimates
Multi-asset strategies are sold on the promise of diversification. The problem is that diversification benefits collapse during market stress. Correlations between asset classes tend to converge toward one when you need them most. I saw this clearly during the March 2020 sell-off. A portfolio I was monitoring had been allocated 60 percent equities, 30 percent bonds, and 10 percent commodities with the expectation that bonds would cushion equity declines. Instead, everything sold off simultaneously. The correlation matrix flattened to nearly 0.9 across all three buckets. The only thing that didn't drop was the short volatility overlay, which made money precisely because the entire rest of the portfolio was collapsing together. This means you cannot rely on historical correlation matrices to construct a multi-asset portfolio that will behave as expected. You need to stress-test it against periods of correlation breakdown and build in explicit contingency allocations — typically cash or direct short hedges — that activate only when correlation thresholds are breached.
Factor overlays add real edge when done correctly
The advanced multi-asset approach layers factor exposures on top of the base allocation. Instead of asking "how much equity?" you ask "which equity factors?" and "which fixed income factors?" This lets you express views through factor tilts rather than broad asset-class bets. Momentum, value, carry, quality, low volatility — these are the standard ones. The trick is understanding which factors are priced and which are free. In developed market equities, most obvious factor premiums are well known and partially arbitraged away. Emerging market credit, on the other hand, still offers genuine carry and value signals that have not been fully explored by the broader market. A practical implementation might look like this: your base allocation stays at 50/30/10/10 across the four major buckets. Within equities, you tilt toward quality and low volatility when the yield curve is flat or inverted. Within fixed income, you shift duration and credit exposure based on term premium signals and credit spread trends. The commodity sleeve gets a carry bias regardless of macro conditions. The alternative sleeve — typically managed futures or macro hedge funds — acts as the crisis alpha component. I use the macro-regime framework from AQR and similar firms as a starting point but simplify it considerably. Their original model uses six distinct regimes with specific weightings. I compress it into four: risk-on, risk-off, disinflation, and inflation. The four-regime model has slightly lower predictive accuracy but requires far less data maintenance and is easier to communicate to clients who otherwise tune out at the third regime definition.
Where this approach breaks down
Multi-asset strategies have real limitations. The first is data dependency. You need reliable historical data across all your asset classes, adjusted for survivorship bias and current market structure. Many free or low-cost data sources omit delisted securities or adjust past prices for index changes, which means your backtest is systematically overstating what the strategy would have actually delivered. I spent a week once fixing a backtest where the original author had not accounted for the 2016 UK gilt futures contract roll, which created a phantom return spike that disappeared entirely once the roll cost was properly modeled. The second limitation is complexity drag. Every additional asset class, factor overlay, and rebalancing rule adds operational overhead. A well-constructed multi-asset portfolio requires ongoing monitoring of correlations, rebalancing triggers, factor exposures, and liquidity conditions. This is not a set-it-and-forget-it strategy. It requires active management that most investors underestimate when they first build one. The third and most important limitation is behavioral. Multi-asset strategies tend to underperform concentrated bets during strong trending markets. When equities run for three years straight, your 20 percent bond allocation will feel like dead weight. Clients and portfolio managers face real pressure to shift toward the outperforming asset class, which defeats the purpose of the multi-asset approach in the first place. The strategy works because it smooths outcomes, not because it maximizes peak returns. Accept that trade-off upfront or you will abandon it at the worst possible moment.
Practical tools for implementation
For anyone building a multi-asset model from scratch, Python is the standard environment. The main packages you need are pandas for data handling, numpy for calculations, and statsmodels or scikit-learn for the regression and factor work. For portfolio optimization, the PyPortfolioOpt library covers mean-variance, risk parity, and Black-Litterman approaches. If you are doing factor work, the ff package or custom factor regression frameworks are the typical route. A basic workflow runs like this: pull historical returns for your chosen universe, compute covariance matrices on rolling windows, run a mean-variance or risk-parity optimizer to generate target weights, apply your factor tilts as constraints on the optimizer, backtest the resulting allocations against transaction costs, and then monitor live performance against the rebalancing thresholds you defined. A complete backtest with realistic slippage and commission assumptions typically takes one to two days of development time for a well-defined four-asset strategy. Adding private markets or derivatives overlays can extend that to a week or more depending on data availability. The most common mistake I see in production implementations is underestimating rebalancing costs. A quarterly rebalance on a multi-asset portfolio with five or six asset classes and three factor tilts each can generate twelve to twenty individual trades per quarter. At an average slippage of 5 to 15 basis points depending on asset class liquidity, you are looking at roughly 20 to 80 basis points of annual drag from rebalancing alone. That is not trivial. Factor in bid-ask spreads, market impact for larger positions, and tax consequences if you are working in a taxable account, and the effective cost can exceed 100 basis points per year.
The workaround I recommend is batching trades. Instead of rebalancing all positions simultaneously, sequence them by priority: adjust the largest deviations first, let smaller positions drift within their bands, and only trigger the marginal adjustments when a secondary rebalancing event coincides with favorable market conditions. This can cut transaction costs by roughly 30 to 40 percent with negligible impact on portfolio risk characteristics.
Bottom line
Multi-asset strategies are a legitimate approach to portfolio construction when executed with proper attention to correlation dynamics, rebalancing costs, and factor implementation. They are not a magic solution that produces smooth returns with low effort. The friction is real and operational. But for investors who understand the mechanics and accept the behavioral constraints, they remain one of the more reliable frameworks for managing risk across changing market environments.