
How to Recognize and Deal with the National Financial Hardship Loan Center Scam
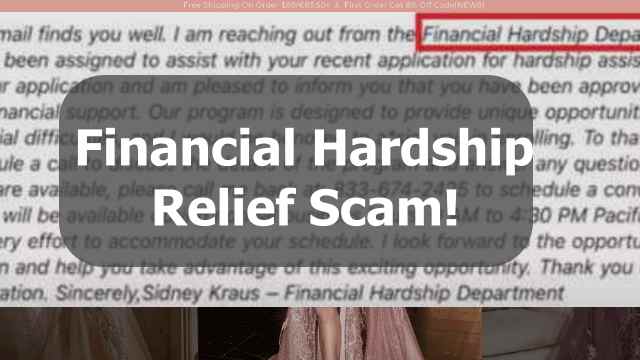
These operations pop up constantly, usually targeting people who are behind on payments or recently lost income. They promise quick loan approvals with little documentation, which should immediately set off alarm bells. The real problem is that they look professional enough to fool someone who's already stressed and doesn't have the mental bandwidth to verify everything. I ran into this exact situation back in 2019 when a former colleague called me panicked. She had applied through a site that looked legitimate, provided her banking details and a government ID, and was told her loan was approved within hours. Then they asked for a "processing fee" of $450 upfront. When she refused, the number went dead. She'd lost nothing yet, but she was shaken. The workaround was straightforward: she never processed the payment, blocked the number, and filed a complaint with the FTC. That's really all you can do at that point.
How the National Financial Hardship Loan Center Scam Actually Works
The structure is almost always the same. They run Google Ads or social media ads with headlines like "Get $500 Today — No Credit Check." The website itself is polished enough to pass a casual glance. It has a privacy policy, a contact page with a phone number, and testimonials that read like they were written by someone who doesn't understand how real people talk about money problems. The mechanism is an advance-fee scheme disguised as a loan product. You submit personal and financial information through their application form. They either approve you immediately or send you a fake approval letter. Then they request an upfront payment for insurance, processing, or verification before you receive any funds. Once you send that money, whether by wire transfer, gift card, or cryptocurrency, they disappear. The loan never materializes. One thing most people miss is that these operations often register under real business names and even have actual office addresses. I checked a few of them through state business registries. The companies exist, but they're frequently shell entities registered to commercial mailbox services. The phone numbers route to call centers in different countries entirely. So a quick business license lookup won't save you here.
What Makes This Specific Scam Harder to Spot
Unlike older loan scams that demanded outrageous fees relative to the loan amount, these operations keep their upfront requests modest. They typically ask for $50 to $500, which feels manageable to someone desperate for cash. The psychological trick is that the amount is small enough to seem like a legitimate processing cost, but large enough that the victim absorbs the loss rather than walking away. Another counter-intuitive detail: some of these sites do show you a loan offer document that looks properly formatted, complete with interest rate disclosures and repayment schedules. The document is fabricated, but it's formatted correctly enough to trigger the part of your brain that associates proper paperwork with legitimacy. I've seen victims describe feeling "relieved" when they received the paperwork, which is exactly the emotional state the scam exploits. Legitimate lenders also send documents, but they do so after a proper credit inquiry and identity verification process through established banking channels, not via a web form that promises same-day funding.
Get the Full Details

Red Flags That Actually Matter
Look for these specific indicators rather than relying on a general sense that something feels off: Guaranteed approval regardless of credit history. No legitimate lender guarantees a loan without pulling a credit report. If the site says you qualify with a 400 credit score and no income verification, it's not a real offer. Upfront fees before funding. Federal regulations and standard lending practices prohibit collecting fees before disbursing a loan. Any request for money before you receive funds is a scam indicator, full stop.
Domain age and registration details. Many of these sites use newly registered domains. You can check this through ICANN Lookup or similarWHOIS tools. If a domain was registered less than six months ago and promises instant loans, treat it as suspicious. Contact information that doesn't connect. The phone number listed may route to a voicemail hosted by a cheap VoIP service, or it may be unlisted entirely. Try calling it. If no human answers or the number is disconnected, that's your answer.
What to Do If You've Already Engaged With One
If you've submitted personal information but haven't sent money yet, stop immediately. Close the tab, change your passwords if you used the same ones elsewhere, and monitor your bank statements for any unauthorized activity. Most victims don't realize that the damage may not come from the loan scam itself but from the identity information harvested during the application. If you already sent money, contact your bank or payment provider right away. Wire transfers through Western Union or MoneyGram are nearly impossible to recover. Cryptocurrency payments are gone immediately. Credit card charges and debit card transactions sometimes offer chargeback options, but you need to act within days, not weeks. File a report at ReportFraud.ftc.gov and with your state attorney general's office. These reports don't get your money back, but they help build cases against the operators and may flag the operation for others.
Alternatives That Actually Work
The reason these scams succeed is that people facing financial hardship often can't get help through normal channels fast enough. Credit unions offer small emergency loans with reasonable rates if you're a member. Some employers provide payroll advance programs. Community assistance organizations and local governments sometimes have emergency funds for rent or utility payments. These options move slower than a scam promise, but they won't steal your identity or take your money and vanish. If you need cash today, a paycheck advance through your employer or a small personal loan from a credit union you've already been associated with is the closest thing to what these scammers promise, and it comes with actual legal protections. The bottom line is that urgency is the weapon. These operations are designed to make you act before you think. Slow down, verify through independent sources, and remember that no legitimate lender asks you to pay to receive money.


