What Actually Works for Nebraska Insurance Exam Prep
The pre-licensing course is a formality. It checks a box so you're allowed to sit for the exam, but it won't really prepare you. The actual exam is a separate beast with its own question bank, its own pacing demands, and its own quirks that most prep materials don't cover. I spent years watching people blow this exam after breezing through their pre-licensing course with no real problem. They'd answer the practice questions fine, then show up and get hit with scenario-based questions they'd never seen. The gap between what the course teaches and what the test asks is where people fail. Not from lack of studying, but from studying the wrong thing.
Nebraska Insurance Exam Prep
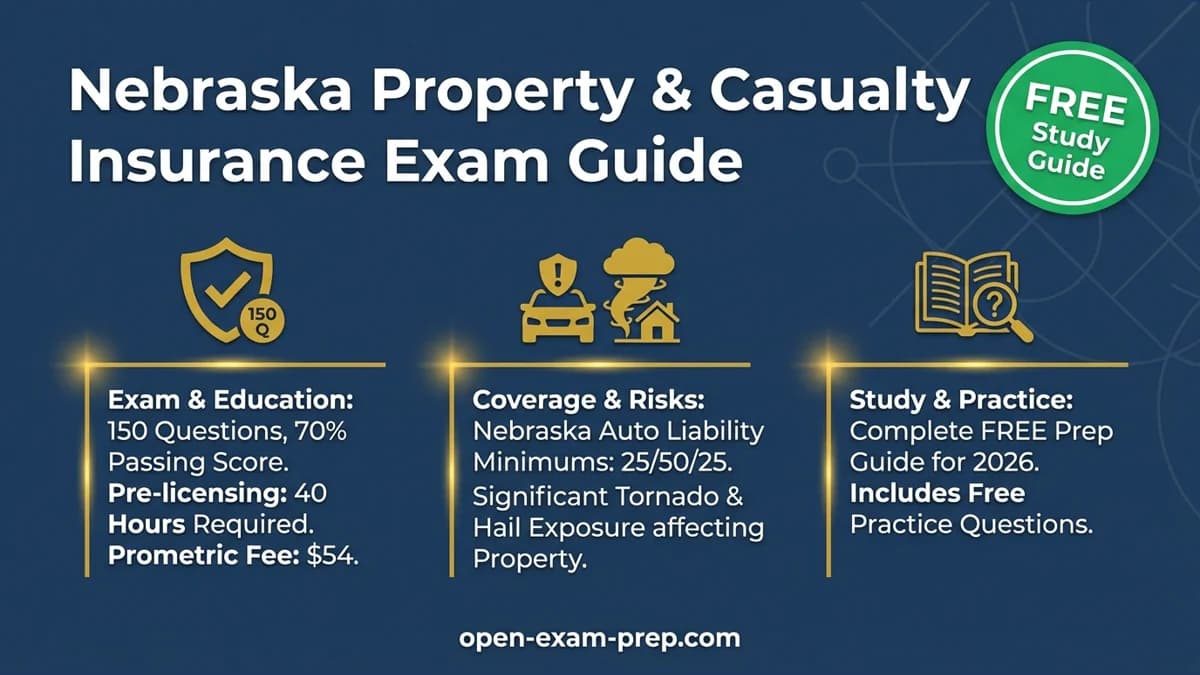
Here's the practical breakdown of how to actually pass it. The Nebraska Office of Insurance is the state regulatory body that administers licensing exams through Pearson VUE. You'll need to complete a state-approved pre-licensing education course before you're even eligible to schedule. For life and health, that's typically around 40 hours of coursework. Property and casualty runs similar. You'll get a certificate upon completion, and you'll need that certificate number when you register for the exam through Pearson VUE. From there, the actual exam structure is standardized. You're looking at roughly 100 to 150 multiple-choice questions depending on the line of authority. You have about two hours. The passing score is 75 percent. The questions are mostly straightforward recall, but a meaningful chunk—easily a quarter of the exam—presents scenarios where you have to apply the law rather than just recite it.
This is where most prep materials fall apart. They give you flashcards and fact drills. What you actually need is applied reasoning practice. I can't stress this enough. The state exam tests your ability to make the right call in a situation, not your ability to define a term. When I was helping people prepare, I ran into a consistent problem. Someone would study hard, take a practice test, score 80 or 85 percent, and then walk into the real exam and barely pass. The issue was always the same: their practice tests used different wording than the actual exam. The concepts were the same, but the way the question was framed threw them off. A concept tested as "What is the free look period?" is fundamentally different from "A policyholder signed their contract on March 3rd and called the insurer on March 12th requesting cancellation. Do they have the right to return it?" Same rule, completely different presentation. My workaround was brutal but effective. I had people take every practice test they could find, then re-read every single question and answer and try to reverse-engineer how it could be reworded into a scenario. If a question said "The grace period is 30 days," force yourself to come up with five different scenario setups that test the same fact. Do this for every major topic area. It takes time, but it closes the gap between knowing the material and being able to recognize it under exam conditions.
Get the Full Details
Here are the specific topic areas that carry the most weight and trip people up: Policy provisions are huge. You need to know every standard provision by name and function, but more importantly, you need to know which provision applies when two provisions could reasonably overlap. The incontestability clause and the misstatement of age provision both deal with incorrect information on an application, but they trigger at different times and produce different results. I've seen people lose points on both because they couldn't tell the difference under pressure. Nebraska-specific law is another trap. The state has its own variations on some national standards. The prompt payment of claims statute, for instance, has specific timeframes that differ from the NAIC model. Unfair claims practices, the right to examine provisions, something as basic as what constitutes a valid notice of loss—all of these have state-specific answers. If your prep material is purely national in scope, you will miss these.
For property and casualty specifically, the insurance services office ratings and the mechanism of the Nebraska FAIR Plan come up more often than you'd expect from a general prep course. These are state-level constructs that national providers gloss over. The FAIR Plan handles insurable risk in designated areas when standard market insurers won't touch it. Knowing how it interfaces with standard policies, and what triggers participation, comes up on the exam with regularity. One counter-intuitive thing most people miss: the exam penalizes absolute language. Answers containing words like "always," "never," or "must" are frequently wrong. Insurance law is full of exceptions and conditional application. The correct answer is almost always the one that acknowledges nuance rather than making a sweeping statement. This isn't a guaranteed rule, but it's reliable enough that you should factor it in when you're stuck between two choices. Another thing beginners overlook is the ethics and professional conduct section. It's smaller than most people expect, but the questions are straightforward once you know the framework. The key is understanding that the duty to the insured generally trumps other considerations in the exam's logic. If a question pits the agent's convenience against the client's best interest, the exam wants you to pick the client's interest every time. It's not necessarily how real life works, but it's how the test is written.
For your study plan, I'd recommend this sequence. Start with the pre-licensing course, but don't just passively absorb it. Take notes in your own words and flag anything that seems ambiguous. After you finish the course, move immediately to practice exams. Not flashcards. Not review books. Actual timed practice exams. This tells you where you stand before you waste time studying things you already know. Then build your study around your weaknesses. If you're scoring well on life insurance but bombing property and casualty, spend proportionally more time on P&C. The exam weights each line separately, so your overall score doesn't protect you from failing a specific section. There are some solid resources out there. The state approves certain education providers, and their practice materials align closest to the actual exam. Third-party exam prep companies like Kaplan or Preplexity also produce study guides specifically for Nebraska. Their question banks tend to be harder than the actual exam, which is actually useful because it builds confidence when you see the real test.
A legitimate concern with some of these third-party materials is that they sometimes include outdated information. Nebraska updates its statutes periodically, and if a prep book hasn't been revised in a few years, it could have incorrect timeframes or referenced procedures that no longer apply. Always cross-reference with the current Nebraska Insurance Department website, especially for any numerical values—grace periods, prompt payment deadlines, renewal notice requirements. These numbers change and the exam will test the current version. Another limitation worth noting: cramming doesn't work for this exam, but it also doesn't help to study too far in advance. The ideal window is about two to four weeks of focused preparation. Study too early and you forget the details. Study too late and you haven't built enough pattern recognition to handle the scenario questions. I'd recommend scheduling the exam for roughly three weeks out, then using that time for active practice rather than passive reading. If you're struggling with a specific topic area, the Nebraska Insurance Department publishes study guides and sample questions. They're not comprehensive, but they reflect the style and difficulty of the actual exam better than anything else. Use them as a baseline for what to expect, then supplement with broader practice materials.
One final practical note about the testing environment. Pearson VUE centers vary, and some are older facilities with less comfortable conditions. Bring identification, arrive 15 minutes early, and expect a check-in process that includes a photo and signature. The exam itself is computer-delivered, and you can flag questions and return to them later. This is worth knowing because it changes how you approach the test—don't get stuck on a hard question when you can come back to it. Move through, answer what you can, and circle back. Most people who fail do so because they ran out of time on questions they couldn't immediately solve, not because they didn't know the material. The whole process from start to finish, assuming you schedule everything efficiently, takes about six to eight weeks. Pre-licensing course, certificate processing, exam registration, and your study period. There's no shortcut around the course requirement, and rushing through it will hurt you more than it helps. Take the time to actually learn the material, practice with scenario-based questions, and you'll clear the exam on the first attempt.