What Most People Get Wrong About Buying a Small Business
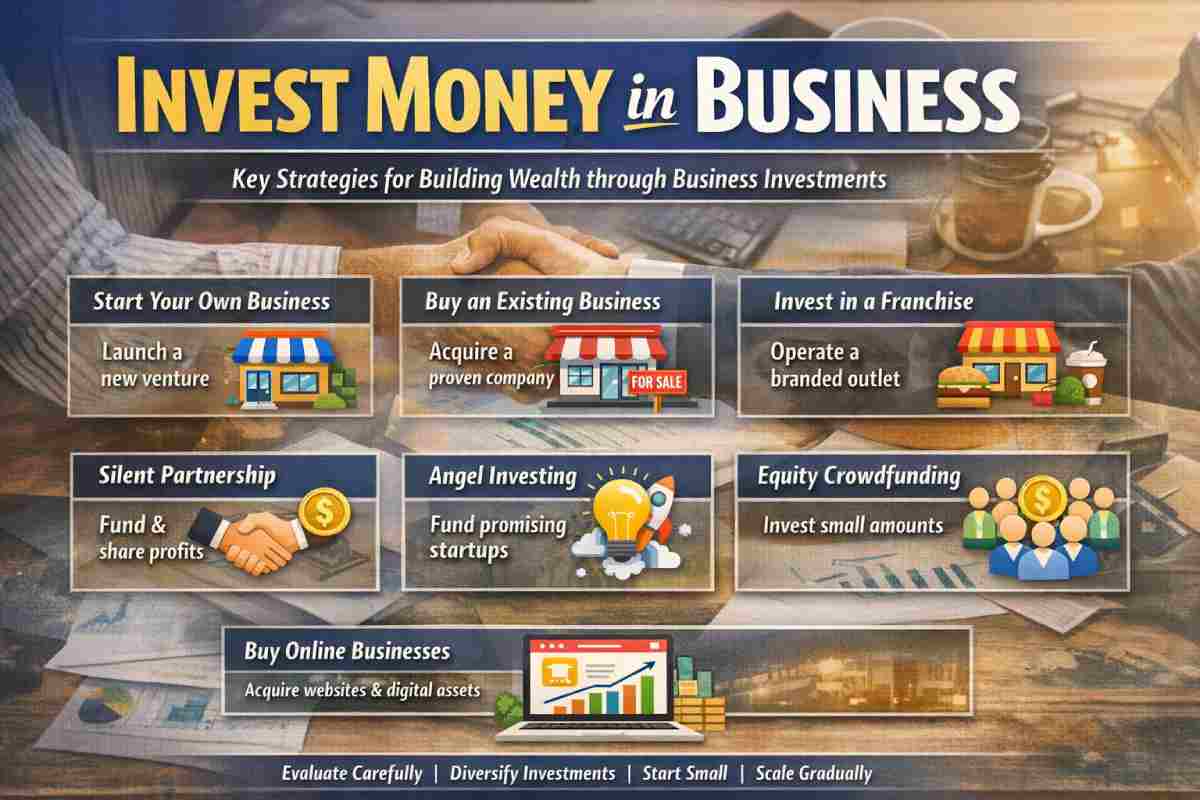
The internet is full of recommendations for a New Business To Invest In, and most of them are marketing material dressed up as advice. I've spent years sitting across tables from brokers, sellers, and buyers, watching deals go sideways over things that had nothing to do with the numbers on paper. The actual process is messier than anyone admits. When you're shopping for a business acquisition, you'll encounter a lot of categories: SBA-backed acquisitions, search funds, franchise opportunities, online businesses sold through brokerages like Empire Flippers or FE International, and the much larger universe of Main Street businesses—plumbing companies, laundromats, vending route portfolios, independent auto shops. Each has real trade-offs. The SBA angle gets the most attention because the 7(a) program lets you put as little as ten percent down, but that debt service requirement means you're personally guaranteeating a loan that can suffocate cash flow in year one if revenue dips even slightly. I've seen buyers who made excellent operational decisions get crushed by payment schedules they hadn't modeled conservatively enough. The unglamorous sectors usually outperform the trendy ones for first-time buyers. Waste management, HVAC service, commercial cleaning, self-storage, equipment rentals. These are boring, operationally intensive businesses with customer relationships that don't disappear when Instagram updates its algorithm. They're also the exact reason most brokers can't help you—they require boots-on-the-ground knowledge to evaluate properly.
New Business To Invest In: Where the Real Opportunities Actually Are
Here's the counter-intuitive part nobody talks about enough. The best acquisition targets often look like bad deals on the surface. A business with stagnant revenue but high owner discretion—that's where the margin expansion lives. You're not buying growth; you're buying the gap between what the current operator extracts and what a competent manager could extract from the same customer base and asset base. A plumber who works sixty hours a week doing every job himself might pull $120,000 in owner earnings from a $400,000 revenue operation. Install a dispatch system, hire two technicians, and raise prices fifteen percent, and that $400,000 suddenly produces $180,000 in discretionary cash flow. The math works whether revenue grows at all. I encountered a specific problem in 2019 when evaluating a commercial janitorial contract portfolio. The seller provided three years of P&L statements that showed steady growth, clean numbers, everything you'd want. But during site visits—a step roughly half of buyers skip entirely—I noticed the actual service hours on the floor didn't match what the contract specified. Three of twelve accounts were being under-serviced by an average of four hours per week, which meant the reported profit margins were inflated by roughly eighteen percent. The contracts had renewal clauses kicking in within six months that would have corrected the hours and compressed margins to something closer to twelve percent instead of the twenty-two percent shown. I adjusted my offer accordingly and walked away from two other deals in the same search where I caught similar discrepancies. The workaround was straightforward: visit every single account location, pull the actual service logs, and compare them line by line against what's written in the contract. It takes about four to six hours for a small portfolio and saves you from overpaying by thirty to forty percent.
Practical Criteria That Actually Predict Success
Rather than following the typical checklist, focus on these signals: Customer concentration matters far more than revenue size. If one client represents more than twenty-five percent of revenue, you own a vulnerability, not a business. Even diversified customer bases hide concentration risk—in software businesses this shows up as dependency on one platform's API, in service businesses as one commercial lease holding twenty percent of recurring income. Owner involvement is the single best proxy for improvement potential, but it's dangerous in both directions. An owner who does everything is a risk because the business dies without them. An owner who has systematically removed themselves from operations is a risk because there's no margin left to capture. Look for the middle ground: the business runs without the owner handling daily work, but there are obvious operational gaps—poor scheduling, reactive maintenance, manual processes that a tech-savvy owner could automate.
Get the Full Details
Regulatory and licensing environments determine your exit options. A beauty salon, a massage therapy practice, a licensed contractor—these require transferring credentials that may not survive a change in ownership. I once watched a buyer lose an entire deposit on a dental practice because the equipment leases had change-of-control clauses that triggered immediate full payment upon transfer. The seller's broker had mentioned the leases in passing but didn't explain the financial consequence. Always pull every lease, license, and permit and review them with a lawyer who handles business transfers, not general practice. The financing reality deserves more honest discussion. SBA loans currently run somewhere between eight and nine point five percent for well-qualified buyers, with terms of ten to twenty-five years depending on asset composition. That's not cheap money. If you're putting ten percent down on a $500,000 business, you're looking at monthly payments in the $4,000 to $5,000 range before you've earned a single dollar from the operation. The businesses that fail under SBA financing are almost always the ones where the buyer assumed debt service could be covered by a portion of revenue that turns out to be non-recurring—seasonal peaks, one-time government contracts, discontinued product lines still showing in trailing twelve-month financials.
What Happens When You Actually Buy Something
The first ninety days will feel like a series of minor crises. Customers complain about changes that haven't happened yet. Employees resist new procedures that seem arbitrary. Vendors raise prices because you took over the account and they can. This is normal. The businesses I've seen succeed are the ones where the buyer documented every decision, communicated it once clearly, and enforced it without apology. The ones that fail are the ones where the new owner soft-pedals because they're afraid of losing stability on day three. Integration timelines vary wildly by industry. A software company might transfer in two weeks with the right technical audit. A manufacturing business with custom tooling and supplier relationships often needs six to eight months before the buyer understands what they actually own. Budget six months of personal runway even if the financial model says you'll be cash-flow positive by month three. The model is always wrong about the first quarter. There's also the tax structure question that most first-time buyers handle poorly. Asset purchases versus stock purchases create dramatically different liability exposures and depreciation schedules. In a typical Main Street acquisition, an asset purchase lets you step up the basis on equipment, inventory, and intangible assets, which generates depreciation deductions that can shield income for several years. A stock purchase preserves historical basis and everything attached to it, including hidden liabilities. The choice depends on the seller's tax situation and your risk tolerance. I once advised a buyer to insist on an asset purchase for a flooring installation business because the seller had unresolved worker's compensation claims from two years prior that a stock purchase would have transferred directly. The seller pushed back hard, called it unnecessary, and offered a price reduction instead. It wasn't about the price reduction. It was about not inheriting a lawsuit.
When Buying Doesn't Make Sense
Some situations are simply bad bets regardless of the opportunity cost. If the industry is facing regulatory headwinds—think cannabis retail in states without clear pathways, or any business dependent on a single government program about to be reauthorized or eliminated—buying into it is speculation, not investing. If the seller is emotionally attached and won't cooperate during transition, you've bought a furniture rental with employees who dislike you. If the competitive landscape is changing rapidly due to technology or consumer behavior shifts, your acquisition premium disappears faster than your debt service obligation. The alternative to buying is building, and most people dismiss that path too quickly. A specialized B2B service business—IT managed services for healthcare providers, compliance consulting for mid-market manufacturers, niche logistics brokerage—can reach the same cash flow targets in three to five years with zero acquisition debt and full control over process design. The trade-off is time. Buying fast-tracks revenue but inherits problems. Building slowly creates revenue but gives you architectural freedom. Neither approach is universally better. They're just different risk profiles. Most acquisitions happen through broker networks, online marketplaces, or direct outreach to owners approaching retirement. The brokers who are worth working with specialize in one vertical and understand the operational realities well enough to flag problems before you see them. The ones who list everything from lasertag arenas to SaaS companies aren't evaluating anything. They're facilitating transactions. Learning the difference takes time but prevents a lot of wasted due diligence.
The businesses I'm still most confident in are the ones with recurring revenue, minimal technology dependence, and owners who built systems rather than dependency on their own labor. Those properties don't generate headlines, but they generate cash, and cash is what pays the debt service while you figure out the rest.