How New Construction Loan Calculators Actually Work in Practice
Most people treat a New Construction Loan Calculator as a magic box where you punch in numbers and get a payment. It is not that. It is a rough estimation tool that works okay for ballpark figures but will mislead you if you are anything close to making a real decision. I have sat across from builders and borrowers who trusted these calculators to within three hundred dollars on a quarter-million loan, which sounds fine until you realize the actual closing costs were six thousand dollars apart because the calculator did not account for builder incentives, rate buydowns, or the way construction draws work.
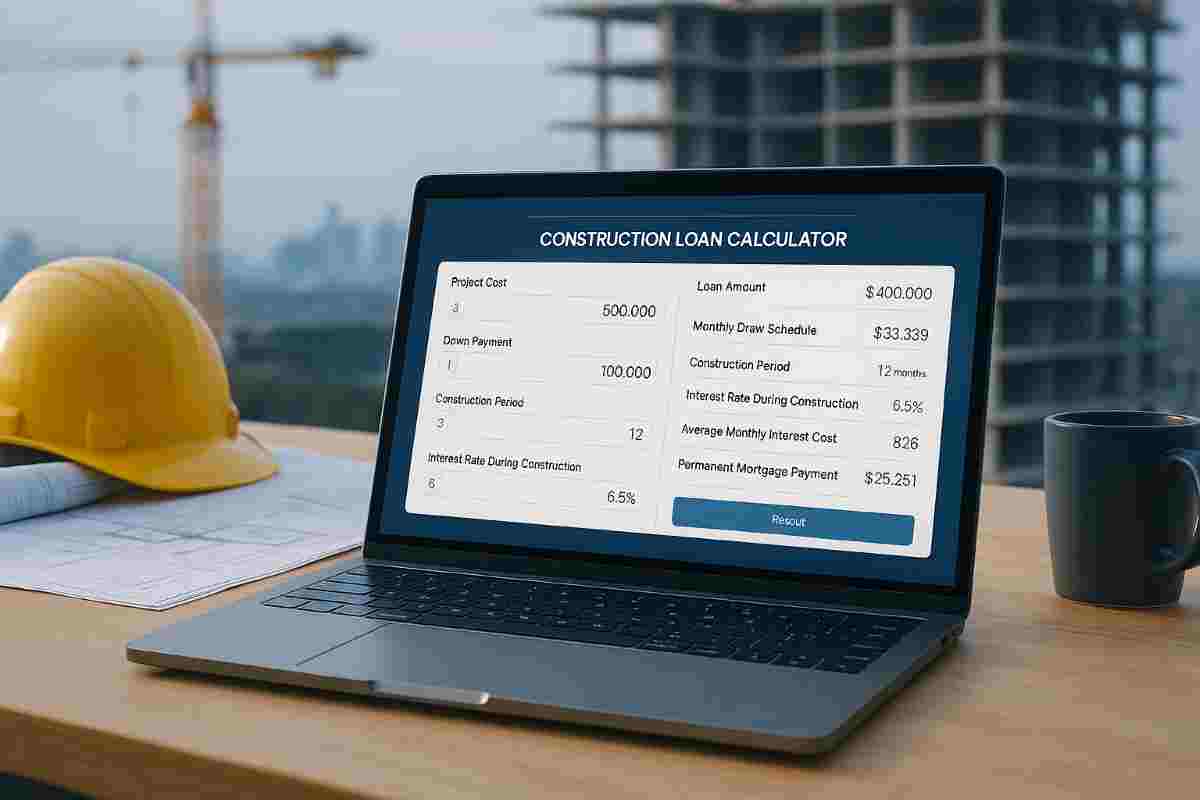
The basic mechanism is straightforward. You enter the land value, the construction cost, the loan-to-value ratio the lender allows, the interest rate, and the term. The tool calculates your monthly principal and interest. Some add property taxes and insurance into a blended payment. That is the extent of most free online calculators. They do not know about draw schedules. They do not know about rate locks expiring mid-build. They do not know that your lender might finance twenty-five percent of the lot cost but ninety percent of the improvement cost, creating a hybrid number that a simple calculator cannot represent.
Using a New Construction Loan Calculator Without Getting Burned
Start by finding your local lenders' actual LTV policies before you open any calculator. This matters more than the calculator itself. In my experience, the biggest mistake borrowers make is entering a single construction cost figure when the project has two distinct components: the land and the build. A lot valued at eighty thousand and a house costing three hundred thousand does not produce the same loan terms as a stick-built home at the same total price. The underwriting is different. The disbursement schedule is different. Run the numbers through both scenarios if you can.
I ran into this exact problem last fall working with a borrower who wanted to put up a rental cabin on inherited land. The New Construction Loan Calculator spit out a clean monthly payment based on three hundred thousand in total project cost at eighty percent LTV. But the land was valued at zero by the county assessor, which meant the lender saw it as a ninety-two percent LTV situation on the improvement side alone. The rate jumped forty basis points and the mortgage insurance kicked in for the entire draw period. I had to rebuild the scenario with a separate land acquisition line layered under the construction note. The actual payment was nearly four hundred dollars higher per month than the calculator showed. That gap cost us three weeks of re-underwriting.
Another thing most calculators ignore: interest reserves. Construction loans are typically interest-only during the build phase, which can last anywhere from six to eighteen months. Some lenders require you to set aside a portion of the loan proceeds to cover those interest payments. A basic calculator will show you the minimum monthly payment but never the reserve requirement. Factor in roughly two to four months of interest as a reserve if you are doing this for real, and then some lenders will require three. The numbers stack up differently depending on whether you are rolling the interest into the loan or paying it out of pocket each month.
Here is a nuance nobody puts in writing: your rate lock timing relative to your draw schedule can change your effective rate by half a point. If you lock at forty-five days and construction is delayed sixty days due to a supply issue, you either extend the lock for a fee or you float and risk a rate increase. The calculator does not model this. I had a client who saved about one thousand eight hundred dollars in rate lock extension fees simply by coordinating their closing date with their material delivery window instead of locking as soon as they got pre-approved. The loan amount stayed the same. The timing mattered.
What These Calculators Miss Every Time
Permitting and impact fees. These vary wildly by municipality and are rarely included in any online calculator I have seen. A county might charge fifteen thousand in impact fees on a new build that a city nearby charges zero for. Builder fees for overhead and profit typically run ten to fifteen percent of the hard construction cost and are financed into the loan, but the calculator will not separate them out. Survey costs, architectural fees, utility connection fees, impact fees again, soil testing, and environmental reviews all add up before you break ground.
Change orders are the silent killer. When a borrower sees a calculator number and signs a contract, they think that number is fixed. It is not. The construction loan gets modified every time there is a change order. Your final loan amount could easily be five to eight percent higher than the original estimate. I once watched a project go from a two-point-one-million loan to a two-point-four-million loan because the buyer upgraded granite to quartz, moved two load-bearing walls, and added a second-story balcony after the initial draw was approved. The calculator never knew about any of that.
There is also the matter of cost-per-square-foot assumptions. Most calculators accept a single total construction cost, which means you have to derive it yourself. The industry average in 2025 sits somewhere between one hundred forty and two hundred twenty dollars per square foot depending on market, but finish levels shift this dramatically. A custom home with premium finishes can hit three hundred fifty or four hundred per square foot without unusual circumstances. If your calculator input is based on a national average but your local market is twenty percent above that average, your payment estimate is off by the same twenty percent.
When to Skip the Calculator and Call a Lender Directly
If your project involves vacant land acquisition combined with construction, composite lots, or a site that requires significant grading or septic work, the calculator becomes less useful the moment you introduce any of those variables. Get a pre-approval from a local construction lender who understands phased disbursements before you do anything else. A good lender will give you a real number within twenty minutes that a free calculator cannot match.
For standard builds on owned clear lots with conventional terms, a New Construction Loan Calculator is adequate for early-stage budgeting. Use it to figure out whether a project is even in your ballpark before you waste a weekend touring model homes. Do not use it to sign a purchase contract. Do not use it to decide between lenders. Do not use it to determine how much house you can actually afford once all the hidden costs materialize.
The honest assessment is that these tools serve a narrow purpose. They give you a starting range, usually within ten to fifteen percent of reality for straightforward projects. Beyond that, they become obstacles because they create a false sense of precision. The construction lending process is messy enough without letting a web form convince you that the numbers are cleaner than they actually are.
Gallery New Construction Loan Calculator
Construction Loan & Mortgage Calculator - Financial Projection Tool
Construction Loan Calculator for Dream Homes
Construction Loan Calculator Calculate Your Costs With Ease Excel ...
VA Construction Loan Calculator | Build Your Dream Home
VA Construction Loan Calculator | Build Your Dream Home