How the New Hampshire Business Enterprise Tax Actually Works
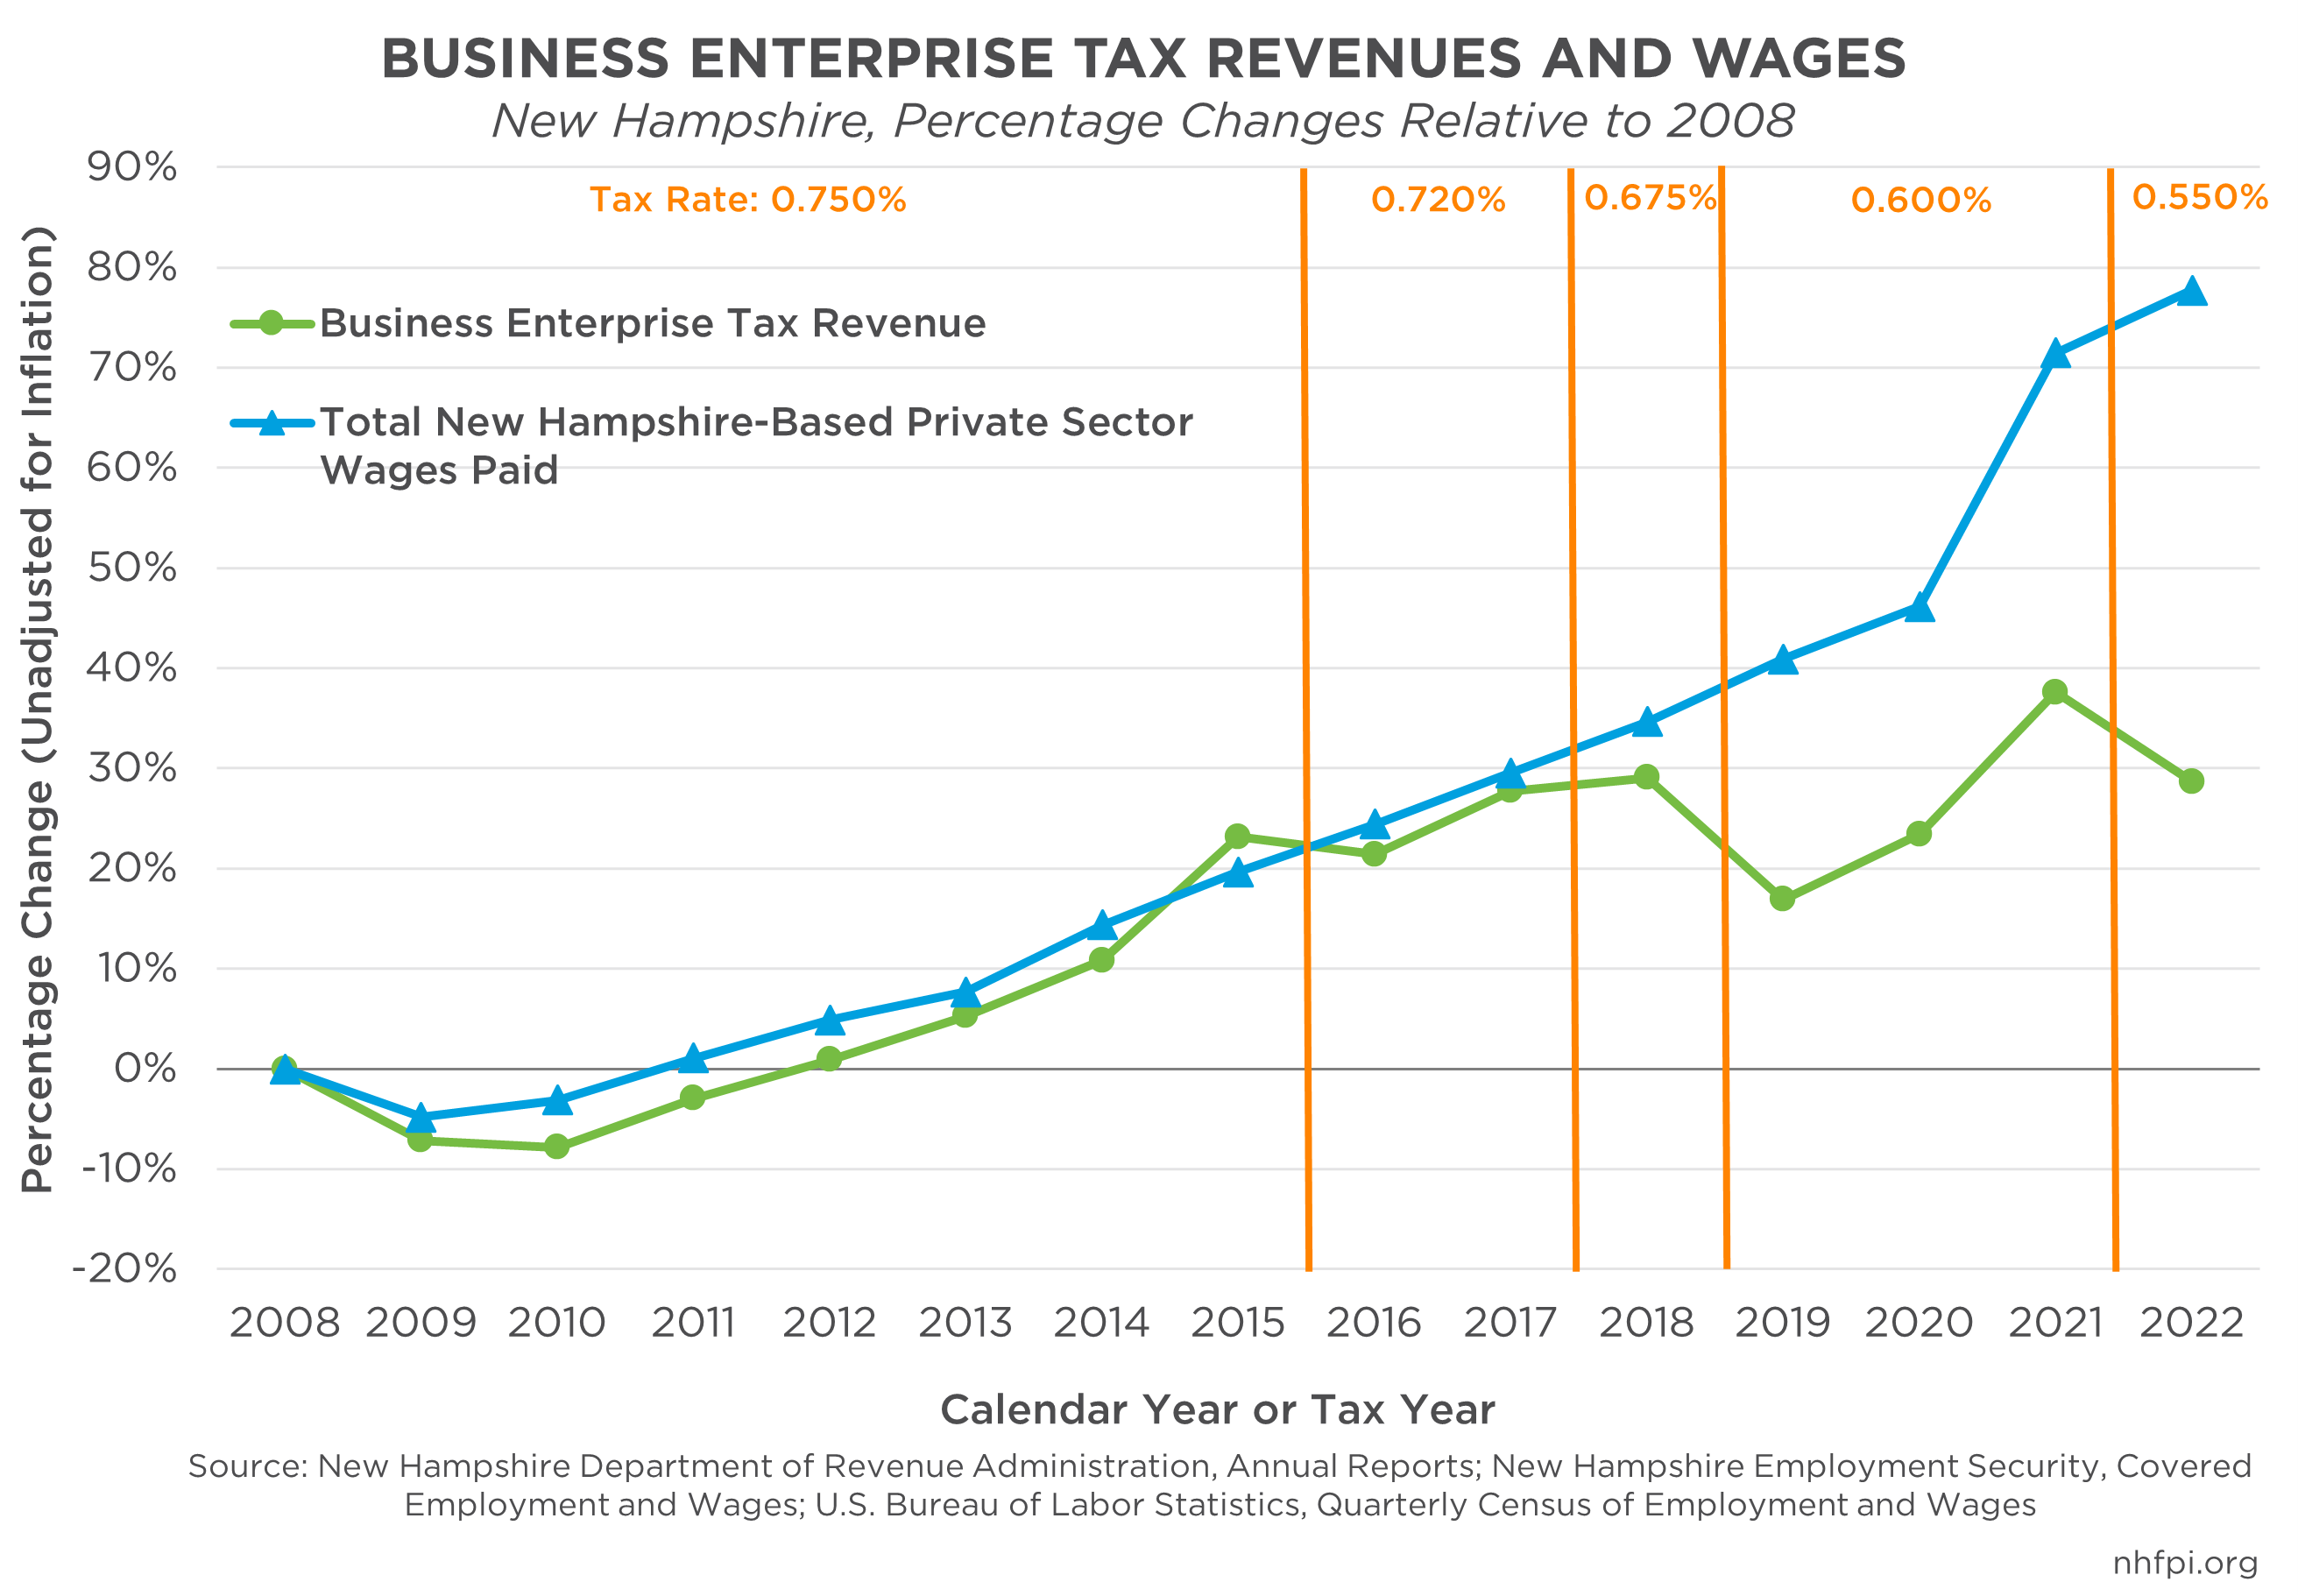
The New Hampshire Business Enterprise Tax is the closest thing the state has to a corporate income tax. New Hampshire doesn't have a broad-based income tax or a general sales tax, so the BET fills that gap for businesses earning income from within the state. It applies to corporations, LLCs taxed as corporations, and certain partnerships that elect corporate treatment. The tax is calculated on what they call "business enterprise" — which is net earnings plus interest and dividend income, with a few adjustments you need to understand before you file. I've dealt with this form enough times to know where people trip up. The rate structure alone is confusing because it's graduated based on your net earnings. Here's the current bracket breakdown: if your net earnings are under $3,000, the tax is $0. Between $3,001 and $15,000, you pay 0.48%. From $15,001 to $50,000 it jumps to 0.72%, $50,001 to $100,000 is 0.96%, $100,001 to $250,000 is 1.20%, $250,001 to $500,000 is 1.44%, $500,001 to $1,000,000 is 1.68%, and above $1,000,000 it's 2.10%. You read that correctly — the marginal rates compound, and most small businesses land somewhere between 0.72% and 1.44% of their net earnings.
Who Actually Owes the New Hampshire Business Enterprise Tax
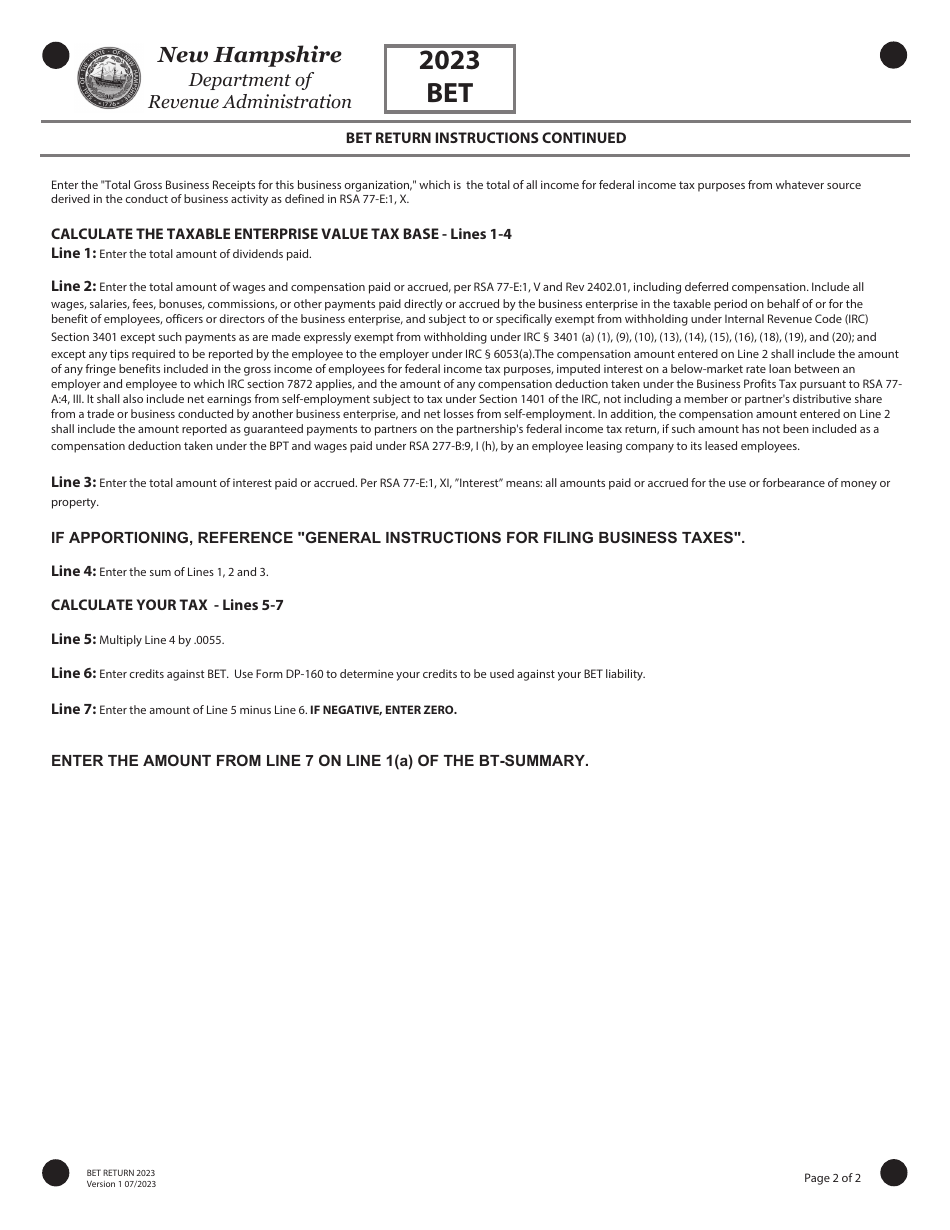
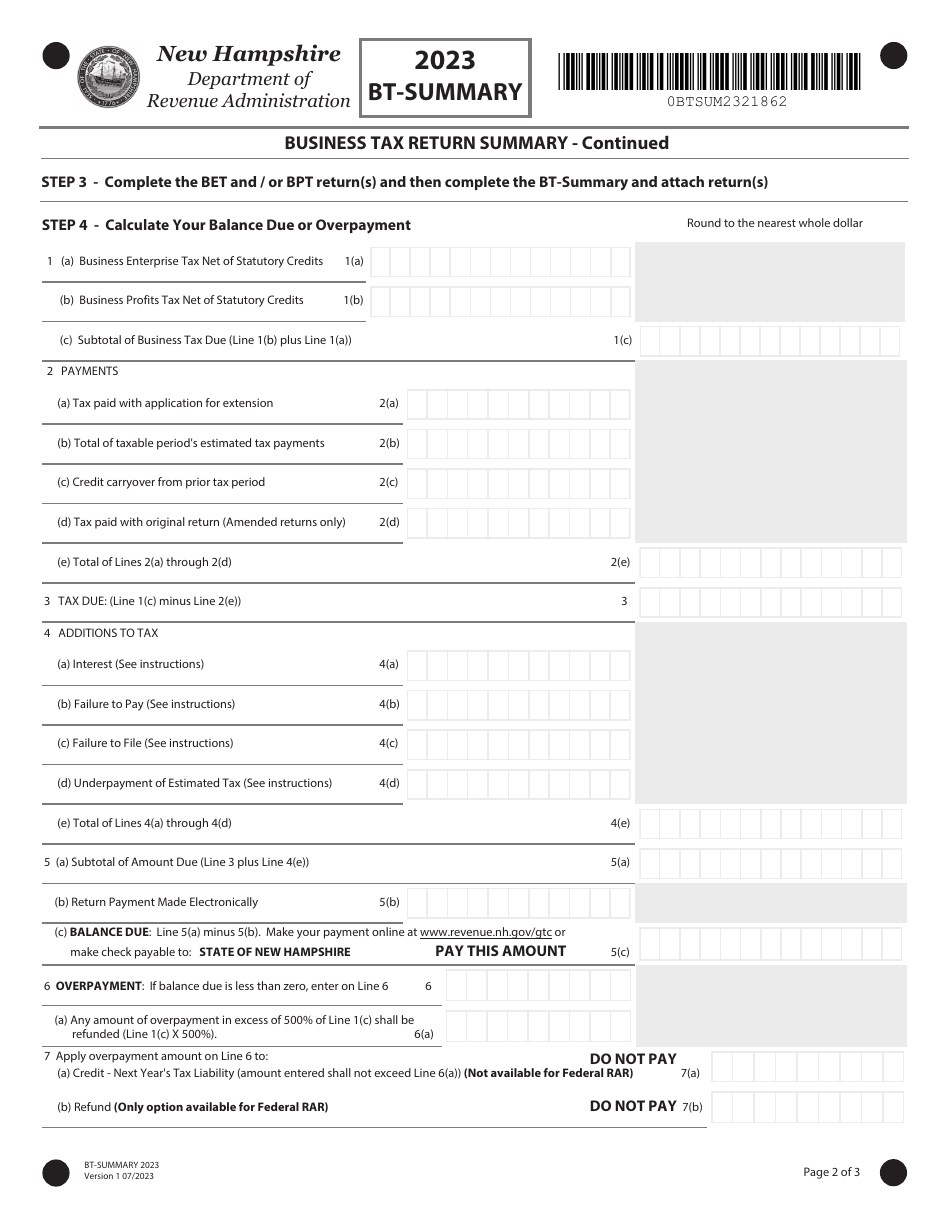
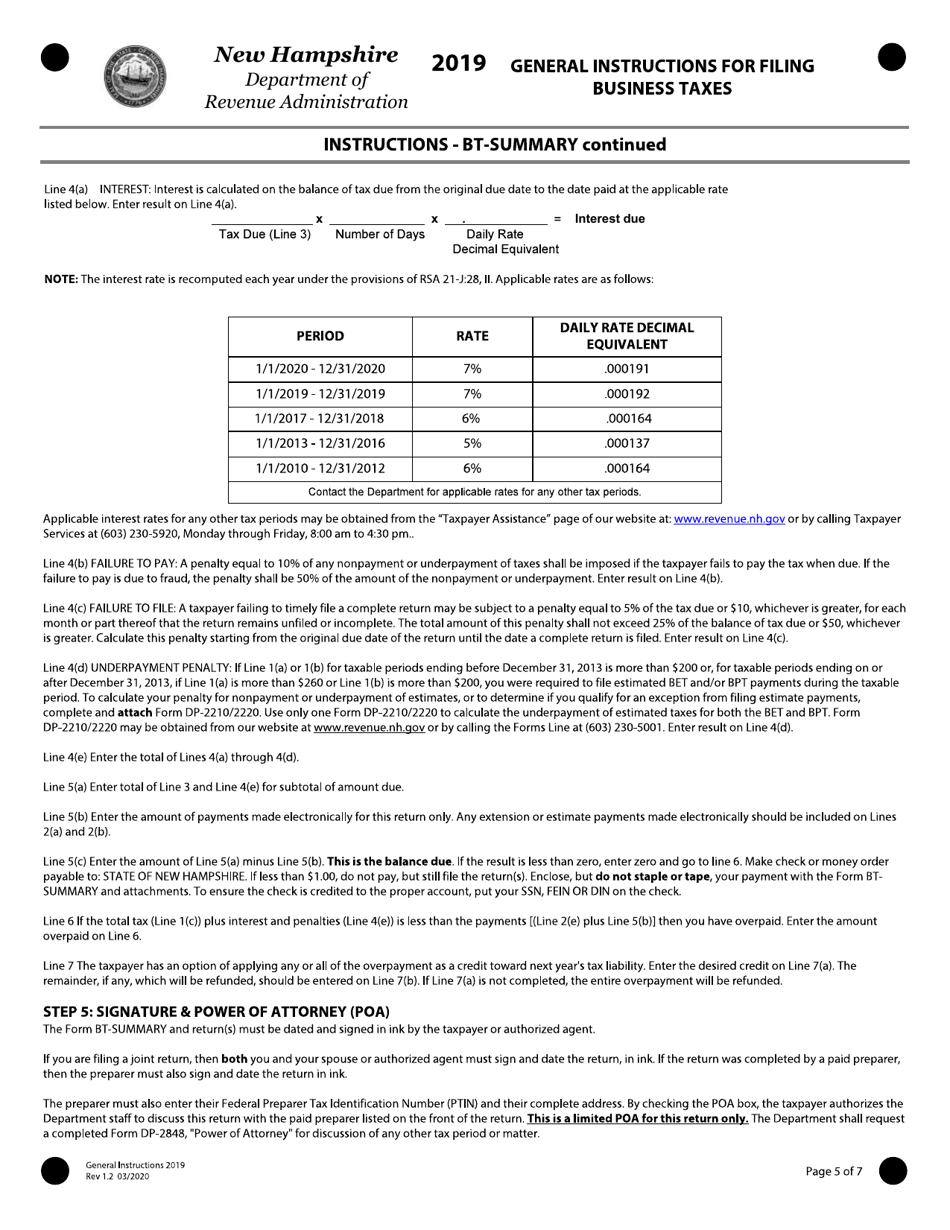
If you operate in New Hampshire and meet any one of these thresholds, you're likely subject to the tax: your gross receipts from business in the state exceed $1,000, you have $10,000 or more in property in New Hampshire, you have $100,000 or more of capital employed in the state, or you have employees working here. This last one catches a lot of remote workers off guard. If your employee lives in New Hampshire but works remotely for an out-of-state company, that person may still count as employment within the state for BET purposes. The form you'll file is Form CT-3, and you can find it at https://revenue.nh.gov/forms/taxes/ct3.pdf. The filing deadline is generally the 15th day of the fourth month after your taxable year ends — so April 15 for calendar-year filers. Extensions are available but cost extra. If you think you owe nothing, you still need to check the box on the form that confirms your ineligibility rather than just ignoring the filing entirely. Here's something most people miss about the calculation: you don't just take your federal taxable income and slap a rate on it. The BET starts with net earnings from all sources, then adds back interest and dividends, then subtracts certain deductions. The line-by-line adjustments matter more than the headline rate. I've seen people underestimate their liability by $4,000 to $8,000 because they forgot to add back the interest income from their business checking account or the dividends from their investment portfolio that the state counts toward the enterprise base.
The Practical Problems No One Talks About
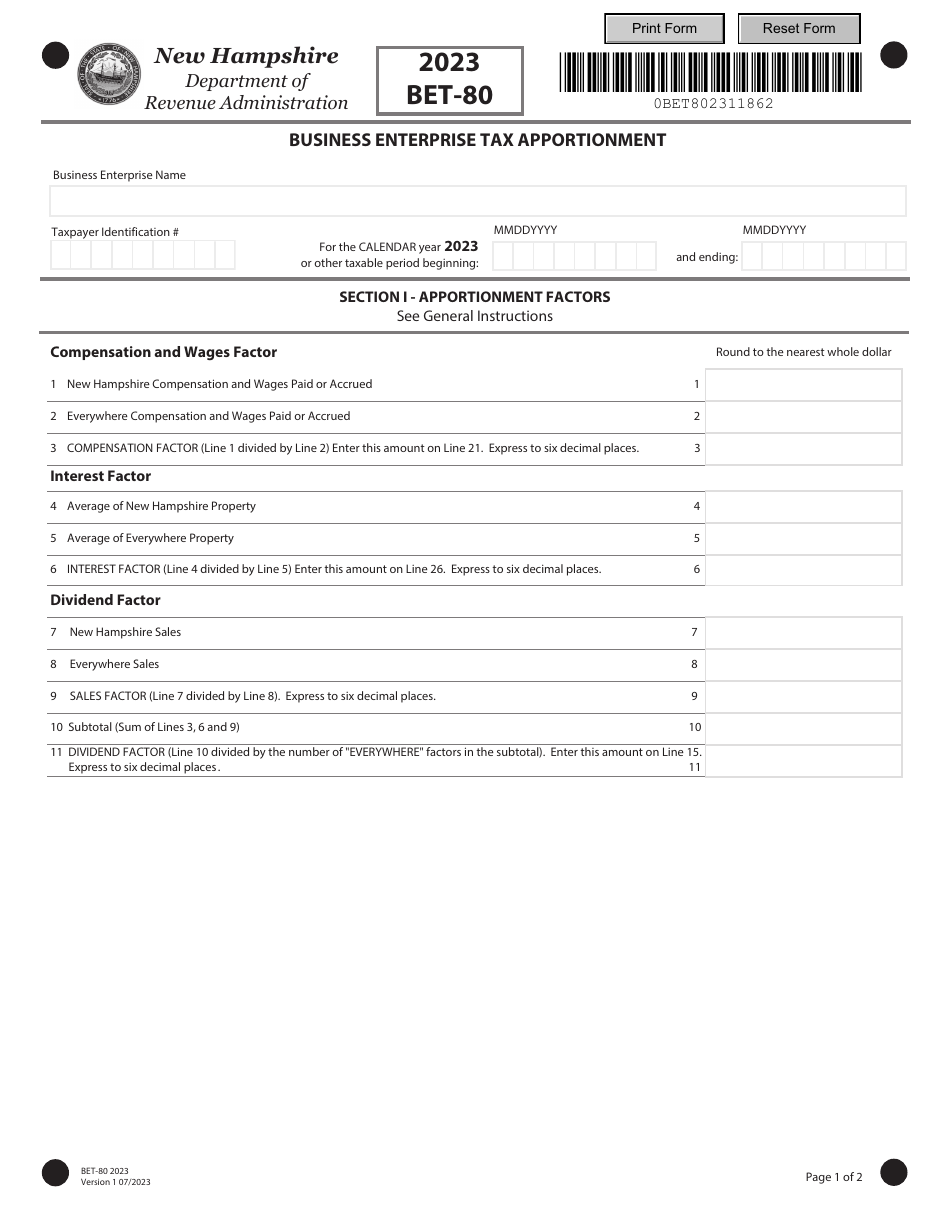
During my first year handling BET filings for clients, I ran into a situation with a multi-state LLC that had income apportionment issues. The business operated primarily in Massachusetts but had a small warehouse in New Hampshire. The question was whether the NH portion of their revenue warranted a BET filing, and more importantly, how to calculate the apportionment factor correctly. The standard formula divides in-state receipts by total receipts, but when your warehouse generates minimal revenue and mostly serves as storage, you can easily overstate or understate your New Hampshire nexus. The workaround I ended up using was filing a full CT-3 anyway, even though the tax due was negligible, and carefully documenting the apportionment factors with a separate worksheet. It turned out the warehouse location itself created sufficient nexus to trigger the tax obligation, and not filing would have exposed the business to penalties that far exceeded whatever they owed in tax. The lesson was straightforward: nexus in New Hampshire can be established purely through property or employee presence, regardless of how small the revenue attributable to that presence might be. Another issue that comes up regularly involves the definition of "net earnings." The state's interpretation includes items that most business owners wouldn't expect. Capital gains, rental income earned through your business entity, and even certain partnership distributions can fold into the net earnings figure. I've had clients who set up their entire strategy around the idea that their business only had "small" earnings, only to discover that an overlooked rental property held inside the LLC pushed them into a significantly higher tax bracket for BET purposes.
Get the Full Details
Common Pitfalls and Where People Lose Money
The biggest mistake I see is treating the BET the same as a standard corporate income tax filing. It isn't. The apportionment rules, the deductions allowed, and the thresholds are all different. If you prepare this form using only your federal Form 1120 as a reference point without cross-referencing the New Hampshire instructions, you'll almost certainly get the wrong answer. The New Hampshire Department of Revenue Administration publishes instruction sheets for CT-3, and those instructions are where the real complexity lives. They're dense but necessary to read. Here's another thing worth noting: the BET interacts with New Hampshire's other business taxes in ways that compound your exposure. If you have employees, you're likely also dealing with the New Hampshire Withholding Tax and the Unemployment Insurance Tax. These are separate obligations, but they share the same nexus triggers. A mistake on one often signals a mistake on the others. I recommend running a nexus analysis for all three simultaneously rather than treating them as independent problems. For pass-through entities, the BET can create double taxation concerns if you're not careful. An LLC electing to be taxed as a corporation pays the BET at the entity level, and then the owners also report their share of income on their personal returns. Some states have throwback provisions or credit mechanisms that prevent this double taxation, but New Hampshire's treatment of pass-through entities under the BET isn't always clean. If your entity is structured as an S-corporation or partnership, you should verify with a professional whether the BET still applies before assuming it doesn't.
What the Form Actually Looks Like in Practice
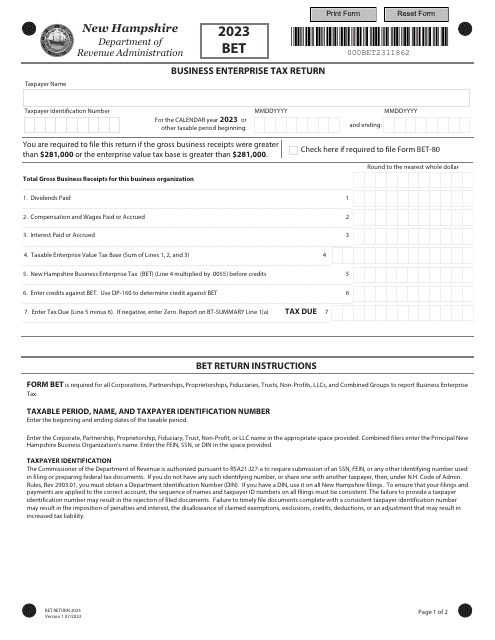
Filling out the CT-3 takes longer than most people expect. A typical small business with straightforward operations and no apportionment complications will spend somewhere between 45 minutes and two hours on the form, depending on how organized their records are. If you have multi-state operations, it can easily double from there. The form asks for your federal EIN, your principal business code, your total assets, and a breakdown of your receipts by source and location. Each of those sections has sub-items that require supporting documentation from your financial statements. The most time-consuming part is usually the apportionment schedule. If your business operates in multiple states, you need to break down your receipts by destination, your payroll by state, and your property by location. Most businesses use a standard three-factor apportionment formula, but New Hampshire allows single-factor sales apportionment in some cases, and choosing the right method can meaningfully change your tax liability. I've seen a $3,000 difference in tax due simply by switching between the two apportionment methods for the same set of numbers. One final thing that matters more than people realize: keep excellent records of your tax payments and filing history. New Hampshire doesn't automatically send you a notice if you miss a filing, and the statute of limitations for assessments runs for six years. If you're ever audited and can't produce your prior-year CT-3 forms along with the supporting schedules, the department can assess taxes based on their own reconstructions of your figures, which are rarely favorable to the taxpayer. This isn't meant to scare you. It's just the reality of doing business here.
If your situation is simple — single-state operations, no apportionment questions, straightforward receipts — you can reasonably handle the BET filing yourself using the CT-3 form and its instructions. If you have multi-state operations, pass-through entities, or any ambiguity around nexus, it's worth spending the money on a competent CPA who understands New Hampshire's specific requirements. The filing fee savings from doing it yourself pale in comparison to the cost of correcting an error later.