Why Most Mortgage Calculators Fail You in New Jersey
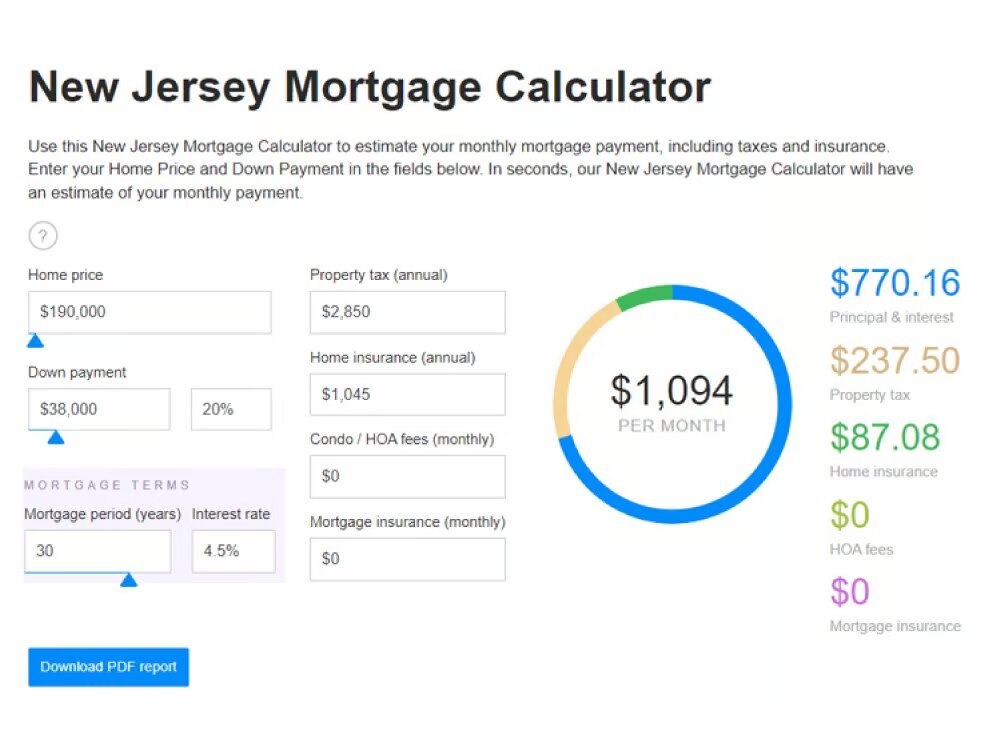
If you plug your numbers into a generic mortgage calculator, you'll get a payment that looks reasonable until you actually open your monthly statement. I've seen this dozens of times in closing rooms across Bergen and Somerset counties. The standard calculators all assume a simple PI + escrow setup, but New Jersey throws in enough variables to completely wreck those estimates. Here's the thing nobody tells you about running a New Jersey Mortgage Calculator: property taxes aren't just "another line item." In some municipalities, your annual property tax alone can exceed the principal and interest payment on a conforming loan. A calculator that doesn't let you input municipal-level tax data or properly handle the split between tax and insurance escrow will give you numbers that are off by $300 to $800 per month. That difference changes whether you qualify for the loan entirely.
How to Use a New Jersey Mortgage Calculator Correctly
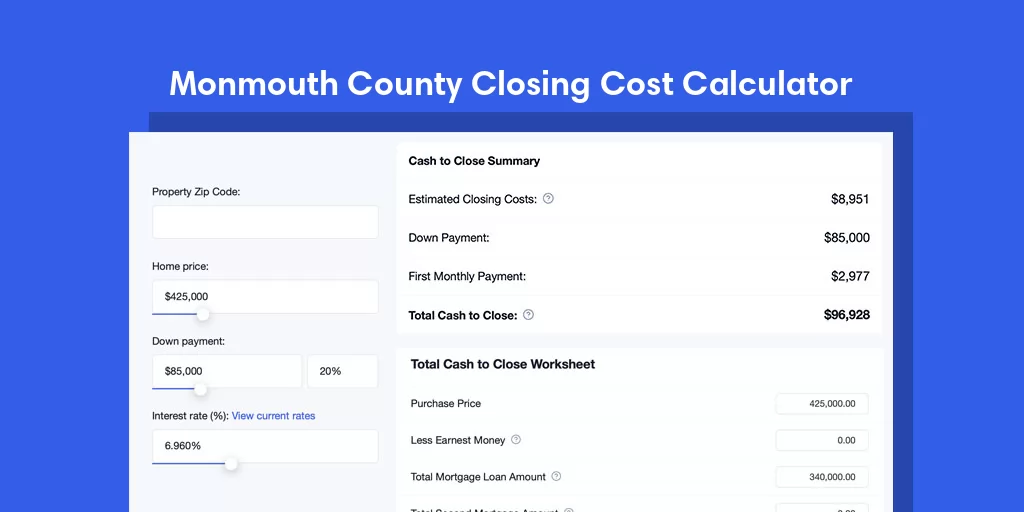
Start by gathering your actual property tax amount from the last full-year statement, not the assessed value divided by 100 or whatever shortcut the listing agent gave you. Property tax assessments in New Jersey don't match actual levied amounts, especially in towns that have gone through revaluation. Use the real number your tax bill shows. Next, enter your interest rate. For a 30-year fixed refinance right now, you're looking at roughly 6.5% to 7.25% depending on credit tier and points. A 15-year sits about 5.75% to 6.5%. These move weekly, so check the current week's pricing before running your calc. I had a borrower last fall who ran his numbers on a rate from three weeks prior and came in $120 short on his monthly qualifying income. The underwriter caught it, and he had to either adjust the loan amount or bring extra cash to close. For the down payment, remember that New Jersey does not have a state-level mortgage recording tax that most people realize, but many municipalities do have their own transfer fees layered on top. That doesn't change your monthly payment calculation, but it absolutely changes your cash-to-close number. A $400,000 home in a township like Wayne or Montclair can cost you an extra $1,500 to $3,000 in municipal transfer fees that a basic calculator will never show you.
When you're inputting homeowner's insurance, use an actual quote, not the generic $1,200 per year that most calculators default to. Wildfire and windstorm coverage in parts of northern New Jersey can push that to $2,500 or more, and flood insurance is a separate line item in many zip codes near the Passaic River or the coast. One client in Jersey City needed a separate flood policy because his condo was in a modified X zone, and the calculator I'd been using had completely buried that cost.
Get the Full Details

The Specific Edge Case Nobody Talks About
Here's a scenario I ran into last spring that completely broke a standard calculator for a client: a property in Essex County with a partial tax abatement. The seller had received a green construction certification under NJ's Green Build Program, which reduced the taxable assessed value by a percentage for a set number of years. The MLS listing showed the abated assessment, but the actual tax bill still reflected the full assessment with a credit line item at the bottom. When I plugged the abated number into the calculator, the monthly payment came out $180 too low. When I used the full assessment, it came out $90 too high because the credit wasn't accounted for. The workaround was to take the actual annual tax amount from the most recent bill, divide by 12, and enter that as a custom monthly tax figure rather than letting the calculator derive it from the assessment. It's not elegant, but it's accurate. Most free online calculators don't let you override the derived tax amount, which is why I stopped trusting them entirely for NJ transactions. Another issue is the Homestead Credit. If the property qualifies and the owner is over 65 or disabled, the credit reduces the actual tax bill by a flat amount each year. This isn't reflected in any standard calculator's assumptions, and it can shave $30 to $100 off your monthly payment depending on the municipality's credit structure. First-time buyers won't see this benefit, but anyone buying a previously occupied home should verify whether a homestead exemption is in place before relying on the calculator output.
Common Pitfalls That Waste Time
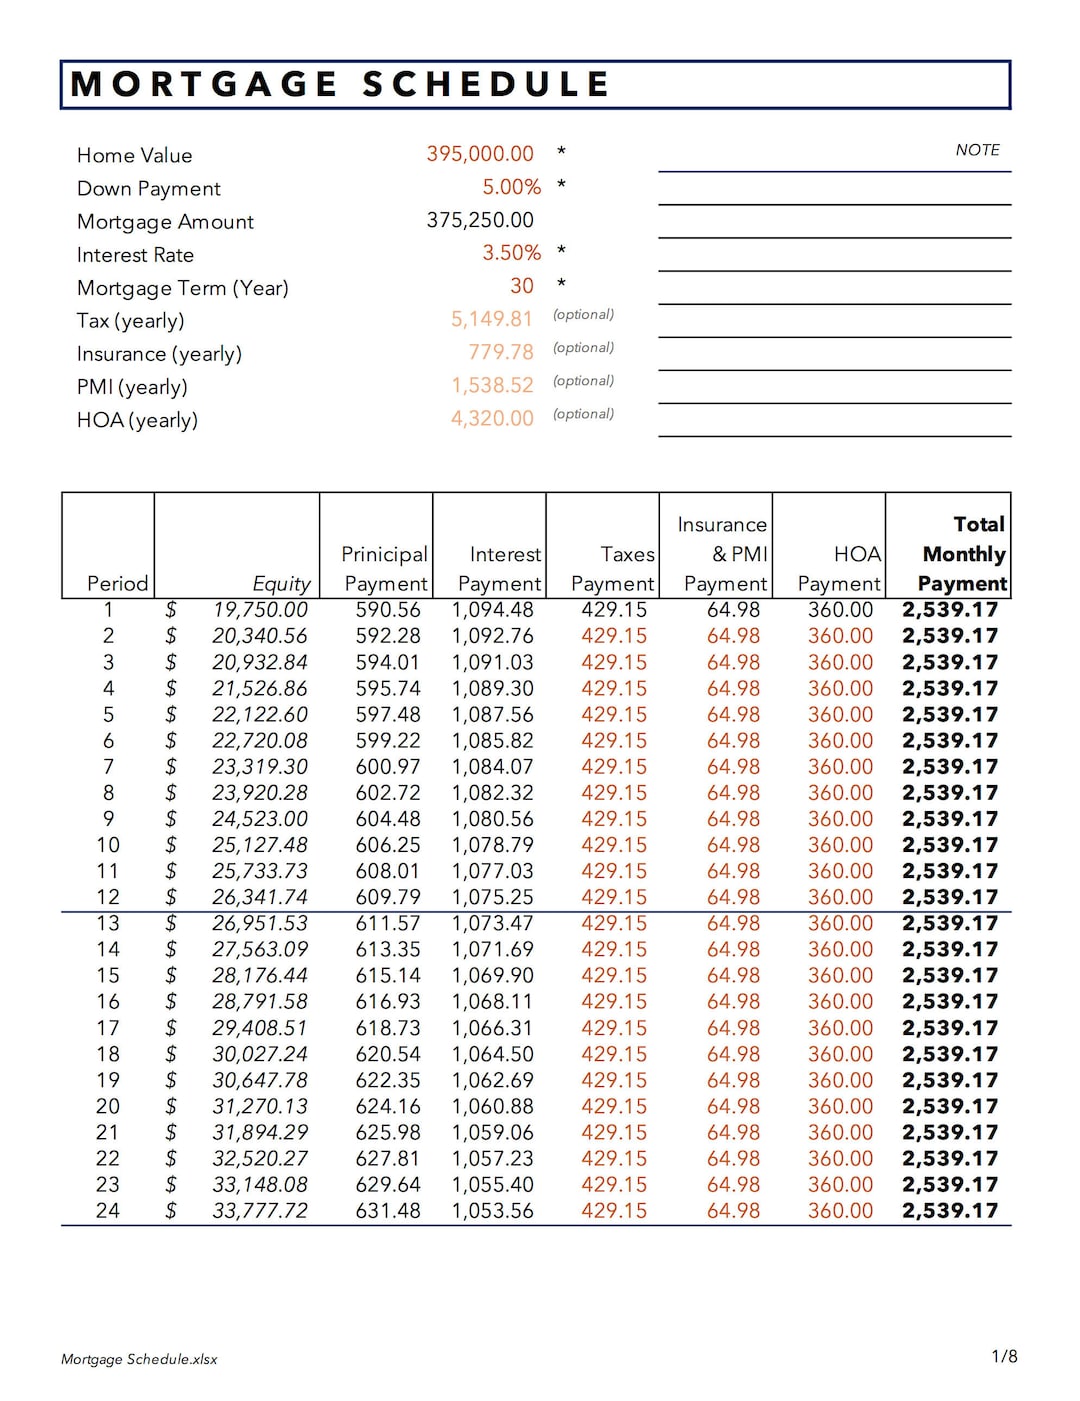
Pitfall number one: using the list price instead of the purchase contract price. If the home sells for $20,000 under asking, your loan amount drops, your rate might shift slightly, and your monthly payment changes. Run the calculator with the actual contract number, not the Zestimate. Pitfall number two: ignoring PMI thresholds. In New Jersey, like everywhere else, if your down payment is under 20%, you'll pay private mortgage insurance. But the calculation of when PMI drops off isn't automatic in most calculators. You need to know that under current rules, PMI automatically terminates at 78% loan-to-value based on the original amortization schedule, but you can request cancellation at 80% LTV. If you're closing at 95% and the calculator assumes no PMI, your real payment could be $150 to $250 higher per month. Pitfall number three: treating HOA fees as optional. In condos and co-ops, especially in Newark, Jersey City, and Hoboken, the monthly HOA can range from $400 to over $1,200. Some calculators have a field for this, many don't. If you skip it, you're looking at a payment that's completely wrong for the product type you're actually considering.
What the Calculator Won't Tell You
A mortgage calculator gives you a monthly payment estimate. It does not tell you whether the rate is locked, whether points are negotiable, or whether your specific credit profile qualifies for the rate you're seeing. I've had borrowers who saw a 6.75% rate on a calculator page, showed up to with 680 credit, and got quoted 7.375%. The calculator wasn't wrong, but it wasn't personalized either. It showed the base rate for a prime borrower with 740+ credit and zero derogatory items. The bigger limitation is that calculators don't factor in closing cost negotiation. In New Jersey, seller concessions can cover up to 3% of the purchase price for conventional loans and up to 6% for FHA. If you're a first-time buyer using a $25,000 grant or assistance program, that changes your loan amount and therefore your payment. No standard calculator asks about grant eligibility or seller contributions unless you manually adjust the loan figure yourself. One more thing worth noting: property tax escrow in New Jersey is handled differently depending on the lender. Some require a full year of reserves upfront, meaning you deposit 12 months of taxes and insurance at closing on top of your down payment. A calculator showing your monthly payment won't capture this cash requirement. If you're budgeting for move-in costs, add roughly 18 to 24 months of combined taxes and insurance to your cash-to-close estimate, not just the monthly figure the calculator spits out.

The bottom line is that a New Jersey Mortgage Calculator is useful as a starting point, but it's not the final word. Take the output, then verify it against actual tax bills, real insurance quotes, and current rate sheets from at least two lenders. The gap between what the calculator says and what your closing disclosure shows is usually where the surprises live, and in New Jersey, those surprises tend to be expensive.