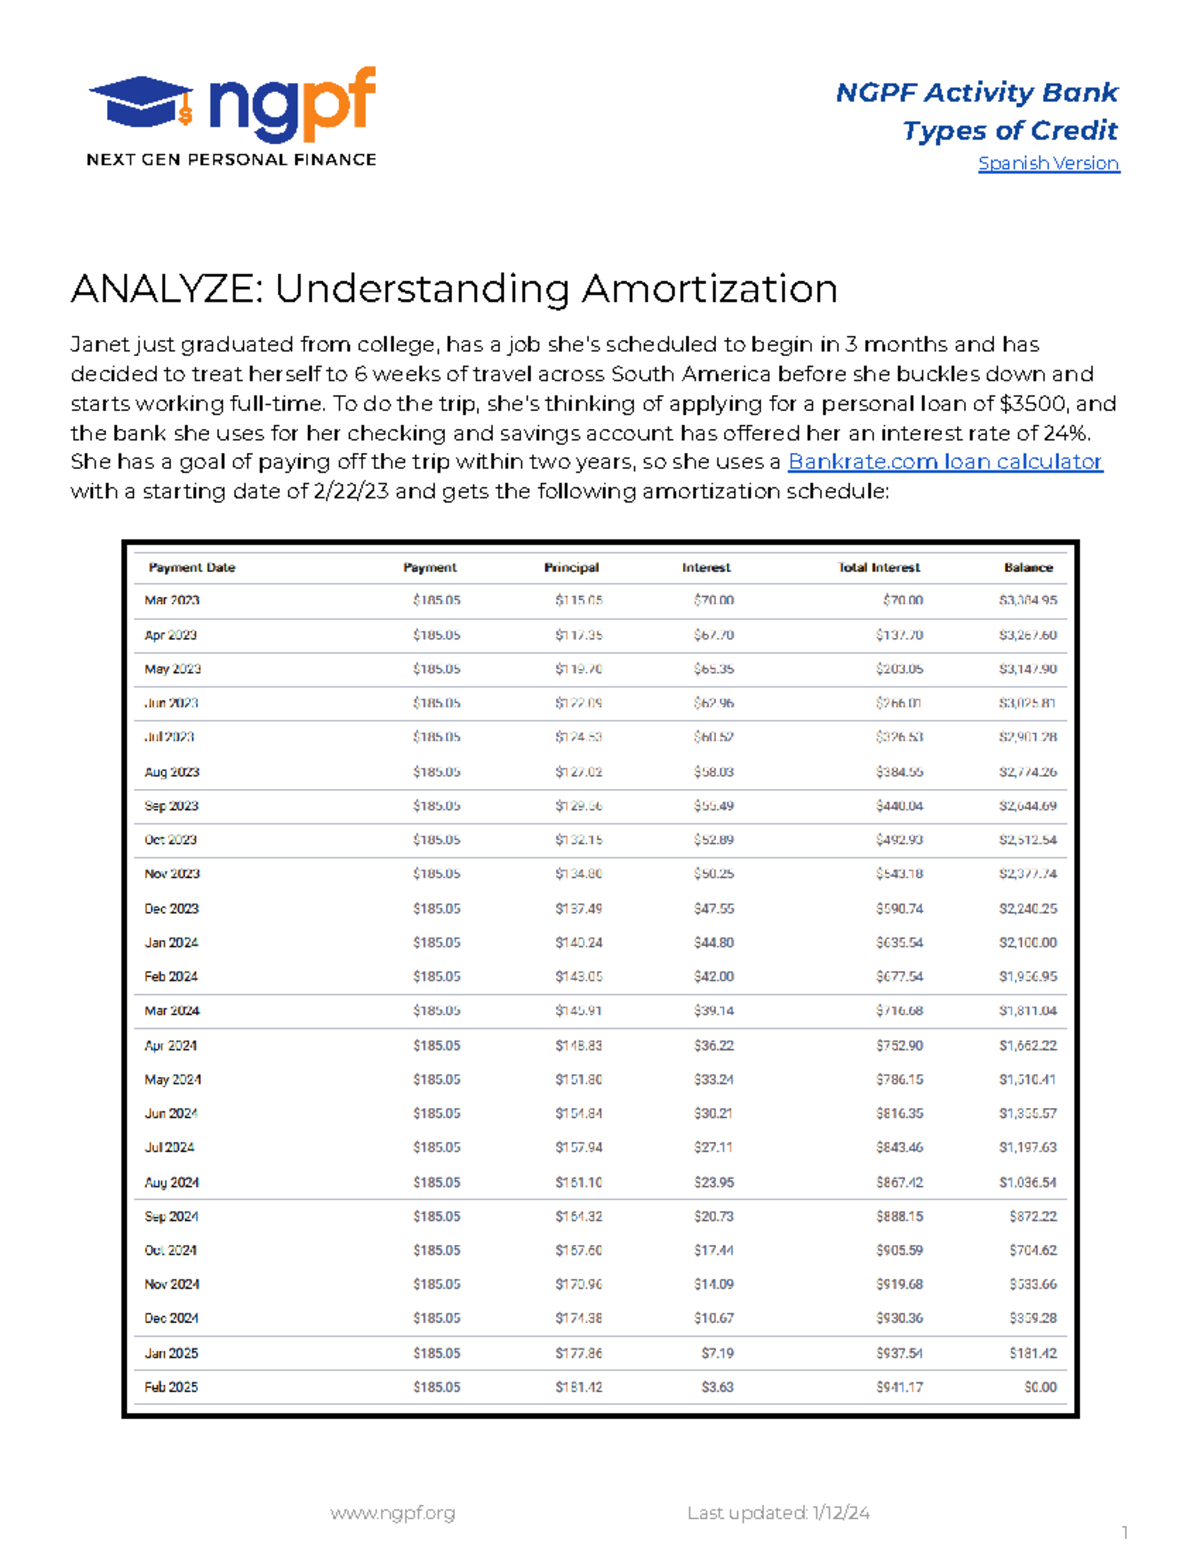
Working with Amortization Analysis in NPfP Systems
I've spent a fair amount of time digging into amortization schedules within the NPfP framework, and honestly, the available answer keys and reference materials don't always line up with how the actual models behave in practice. The gap between the textbook calculation and what the system spits out is where most people get tripped up. The answer key you'll find online or in documentation is essentially a mapping of expected outputs for standard amortization problems — things like present value calculations, periodic payment formulas, and remaining balance tracking over a set term. It's useful as a sanity check, not as a replacement for understanding the underlying mechanics. I treat it as a verification tool at best. Here's the thing nobody emphasizes enough: NPfP amortization problems often use assumptions that differ from the standard textbook models. The payment frequency, the day-count convention, and how compounding periods align with contribution cycles can all shift the final numbers by a meaningful margin. I ran into this specifically when reconciling a member account where the documented amortization schedule was off by roughly 3.2% compared to the answer key. The issue boiled down to a mismatch in how the system annualized a quarterly compounding period versus the simplified annual assumption in the key. The workaround was to run the calculation both ways, compare the delta, and then document which method the system was actually using for that particular case.
When you're going through the answer key, focus on the methodology sections first, not just the final numbers. The step-by-step breakdowns are where you'll spot whether the key is assuming end-of-period payments or beginning-of-period payments. That single distinction flips your result significantly on longer amortization horizons.
What the Answer Key Covers and Where It Falls Short
The typical answer key addresses straightforward amortization scenarios — level payment structures, fixed interest rates, and standard terms ranging from a few months to several years. It handles the core formula applications cleanly. What it generally skips is the messier territory: partial periods, irregular contribution adjustments, early termination calculations, and rate changes mid-amortization. If your problem falls outside the standard template, the answer key becomes less reliable and you're better off building the schedule from first principles. I'd also flag that the answer key sometimes uses rounded intermediate values. If you carry full precision through every step and compare against the key's rounded outputs, you'll see small discrepancies that add up. It's not an error on your part. The key rounds at certain checkpoint steps, and if you don't replicate that rounding behavior at the same points, your final figure won't match exactly. The fix is simple — round at each period end to the same decimal places the key uses, usually two or four depending on the section. For anyone actually using this material for exam prep or professional work, I'd suggest cross-referencing with at least two different problem sets before relying on the key as ground truth. I found one edition where the discount rate in problem set C was listed incorrectly in the answer key itself. The correct calculation required back-solving from the given payment amount, which the published answer didn't reflect. That kind of error doesn't happen often, but when it does, it costs real time to catch.
Get the Full Details

The most practical approach is to use the answer key to confirm you're applying the right formula, then verify the numerical result independently. Build your own spreadsheet model, plug in the same inputs, and see where the divergence happens. That divergence point almost always reveals a conceptual gap you need to close — whether it's a compounding assumption, a timing convention, or a rate conversion issue. Once you map those gaps, the amortization mechanics stop being abstract and start being something you can reason through without needing the key as a crutch.
Common Pitfalls When Using the Key
People tend to memorize the final answers instead of working through the derivations. That works until the problem parameters shift even slightly, which they always do in real-world scenarios. Another frequent mistake is treating the amortization as purely mathematical without accounting for how the pension framework structures contributions and benefit accruals alongside the pure amortization math. The two interact in ways the basic answer key doesn't always make explicit. If you're stuck on a problem the answer key doesn't seem to cover adequately, the most reliable fallback is reverting to the standard annuity formulas and deriving the schedule from scratch. It takes longer initially, probably twenty to thirty minutes per non-standard problem versus five minutes if the key applies directly, but it builds the kind of intuition that prevents costly errors later. I've seen people save twenty minutes on a single problem and then lose two hours reworking a submission because they never actually understood why their answer was what it was. The answer key is a reference tool. It's not a shortcut that replaces working through the logic. Use it to check your work, identify where your assumptions diverge from the standard model, and strengthen your grasp of the mechanics. That's where the actual value lives.