How to Actually Use the Ngpf Managing Credit Answer Key
I deal with this every semester. The NGPF Managing Credit unit is one of those modules where students tend to gloss over the harder parts because they assume the content will be straightforward. It isn't. You need the answer key, but you also need to understand what it's actually telling you when you get something wrong. Here is the practical breakdown.
Ngpf Managing Credit Answer Key
The answer key for the Managing Credit unit covers every activity from the credit card simulation through the debt payoff calculations. Students complete interactive modules on the NGPF platform, and the answer key allows instructors to verify responses quickly. I keep a printed copy in my grade binder alongside the digital version because sometimes the platform glitches during grading periods. The file is typically distributed through official NGPF channels after instructor verification. Make sure you are accessing it from the proper route. There are scattered copies on file-sharing sites that are years out of date, and NGPF updates their curriculum periodically. Using an old key will cost you points on items that have been revised.
What the Answer Key Actually Covers
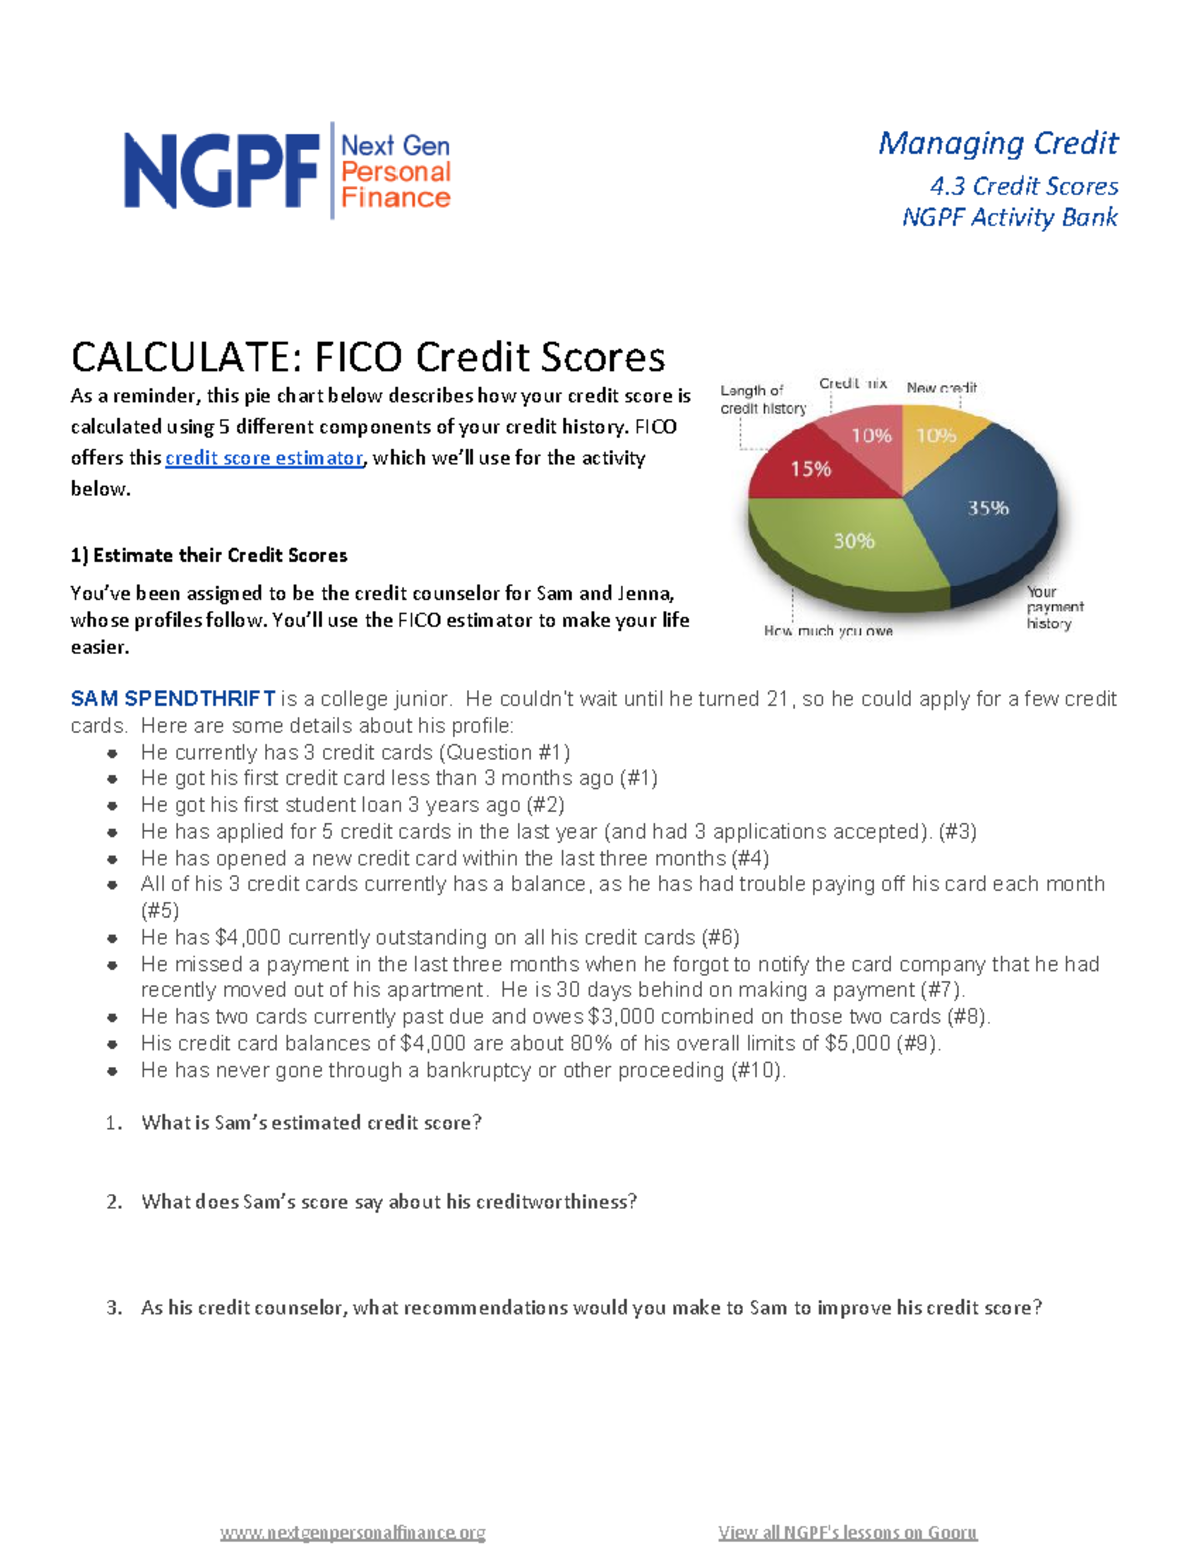
The Managing Credit unit runs through several distinct topics, and the answer key maps to each one. Students work through credit score components, including payment history at thirty-five percent, utilization ratio at thirty percent, length of credit history at fifteen percent, new credit inquiries at ten percent, and credit mix at ten percent. The answer key lists the correct weightings and explains common student misconceptions. One thing I see constantly: students mix up credit utilization and credit mix, and they lose points on questions that seem obvious after the fact. The answer key flags these errors so you can address them directly in discussion. Then there is the APR calculation section. Students are asked to compute total finance charges across multiple billing cycles using the average daily balance method. This is where things get messy. The answer key walks through each step, showing the daily balance adjustments and the precise interest accumulation. I usually project the worked example from the key during class rather than having students figure it out solo. They need to see the mechanics laid out before they attempt the practice problems.
Get the Full Details
The minimum payment trap module comes next. This is a simulation where students watch their balance grow despite making consistent payments. The answer key includes the projected outcome for various payment scenarios, and it highlights the specific moment when emotional reactions usually set in. Students do not expect balances to increase while they are paying. The key gives you the numbers to prove it.
How I Use It in Practice
I do not hand out the answer key and walk away. That approach creates more problems than it solves. Instead, I use it as a diagnostic tool after students complete each activity set. After the credit score activity, I have students score themselves. Then we review the answer key together. Most students put their age as a major factor, which it is not. They also think closing an old card helps their score, which is backwards. Each of these gets caught quickly when we compare against the key. For the APR math section, I assign the problems first, then reveal the answer key step by step. Students work individually, then we go through each calculation stage. The average daily balance method trips people up most often because they forget to account for purchases made mid-cycle. I keep a running whiteboard example open while the key is displayed so they can follow along in real time.
There is a specific edge case I run into every year with the debt payoff calculator. A student once entered a monthly payment that was exactly equal to the interest charge. The simulation showed zero principal reduction, which confused them entirely. They thought the model was broken. It wasn't. The answer key notes this scenario explicitly, but only if you know where to look. I now flag this in advance so students do not waste time thinking the platform is malfunctioning. The workaround is simply recognizing that a payment below the minimum triggers a different calculation path, and the key reflects both paths separately.
Common Pitfalls to Watch For
The biggest issue I see is students treating the answer key as a shortcut instead of a learning tool. They look up answers without completing the activities. This works until the quiz hits a variation they have not seen. NGPF designs questions that test understanding, not memorization. The answer key tells you what is correct, but it does not prepare you for rephrased versions. Another problem is the utilization ratio calculation. Students often divide by the original limit instead of the current available credit after purchases. The answer key uses the correct denominator, but if you are grading independently, you need to notice this discrepancy before it becomes an argument. The key also does not always account for round-to-nearest-cent variations that occur during multi-cycle interest calculations. I have had students dispute a two-cent difference on a practice problem. The math is correct. The rounding is standard. The key will note the exact figure, but the platform may display a slightly adjusted value depending on how it rounds intermediate steps. Accept the two-cent variance and move on.
Where to Access It
Official access goes through the NGPF instructor portal at ngpf.org. You will need an active educator account. The Managing Credit unit materials are organized under the broader Personal Finance course, and the answer key is bundled with the teacher resources section. Download the most recent version and check the revision date. If it does not match the current school year release, something is off. If you cannot access the portal through official means, reach out to your department head or curriculum coordinator. They usually have access codes. Distributing answer keys through unofficial channels is not worth the risk of outdated content or security issues. I learned that the hard way one semester when a shared PDF contained a modified version with incorrect APR figures. Two students came to me convinced their answers were wrong. The key was wrong. Fixing that took an entire class period to undo the confusion.
Bottom Line
The Ngpf Managing Credit Answer Key is useful when you treat it as a reference document rather than an answer sheet. It shows correct responses, explains common mistakes, and provides calculated examples that clarify the more tedious math sections. Use it after students have engaged with the material, not before. The two-cent rounding issue and the utilization denominator trap are the kinds of things that quietly destroy student confidence if you do not spot them early.