Figuring Out the NJ Resident Return Without Losing Your Mind
The New Jersey 1040 is the standard resident income tax form for the Garden State, and the 2022 version follows the same basic skeleton you'd expect from most state returns. You start with federal adjusted gross income and work your way through a series of additions, subtractions, and exemptions to land on your New Jersey taxable income. The instructions document walks you through each line, but reading it cover to cover is about as entertaining as watching paint dry. You can download the form and the full instruction booklet directly from the New Jersey Division of Taxation website at nj.gov/taxation. The PDF is usually available under the individual income tax section. I'd recommend grabbing both the fillable PDF and the separate instruction guide, since the form itself doesn't explain what goes on each line. The instructions run roughly 80 pages and are organized to mirror the form's structure, which helps if you're working through it methodically. Getting the right version matters. Make sure you're pulling the 2022 package and not something current. Tax forms get updated every year, and using an outdated or wrong-year version will cause problems at filing time. The website usually keeps the prior year's materials archived, but they sometimes shift things around between November and March, so bookmark the page if you're working on a late filing.
How the Return Actually Works in Practice
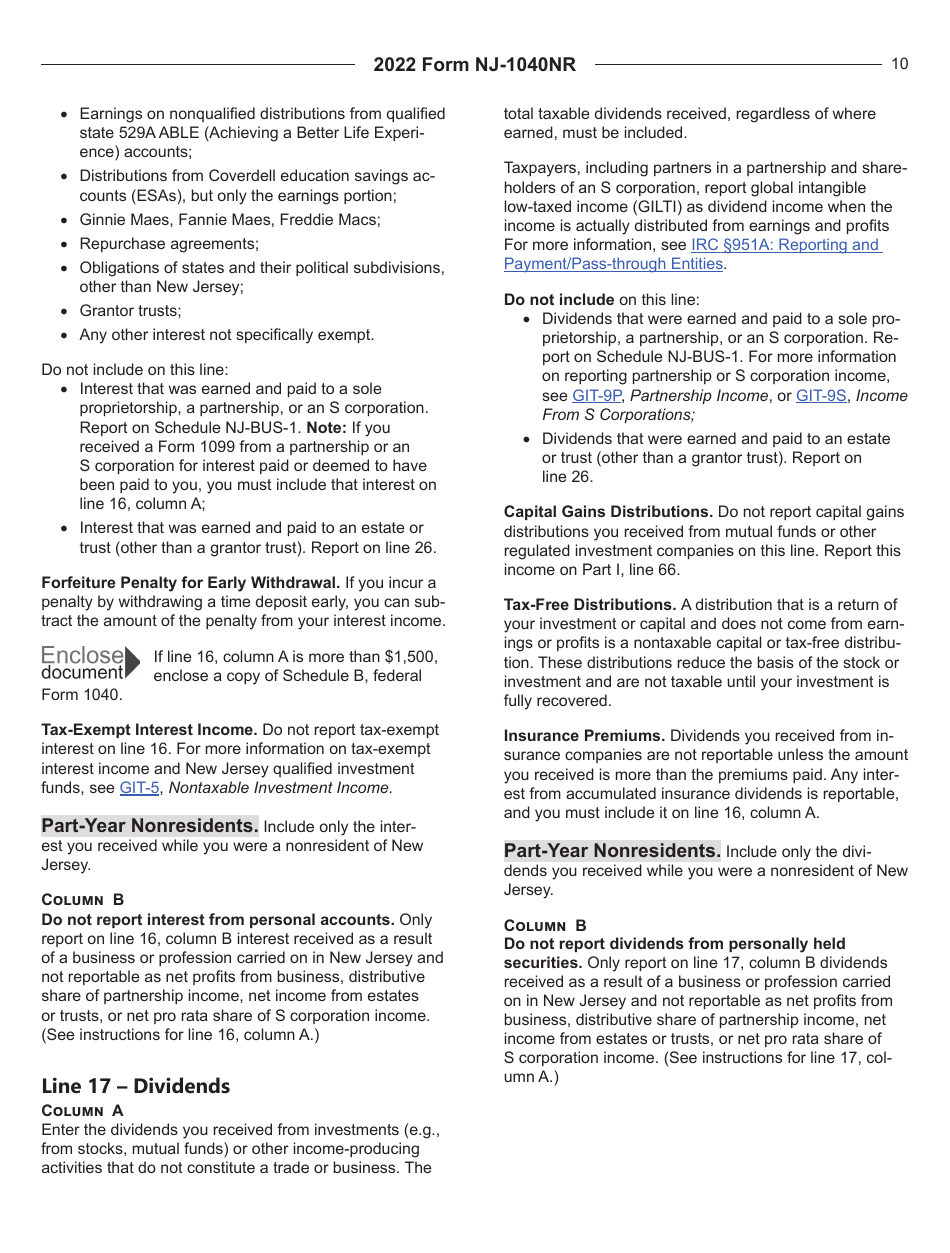
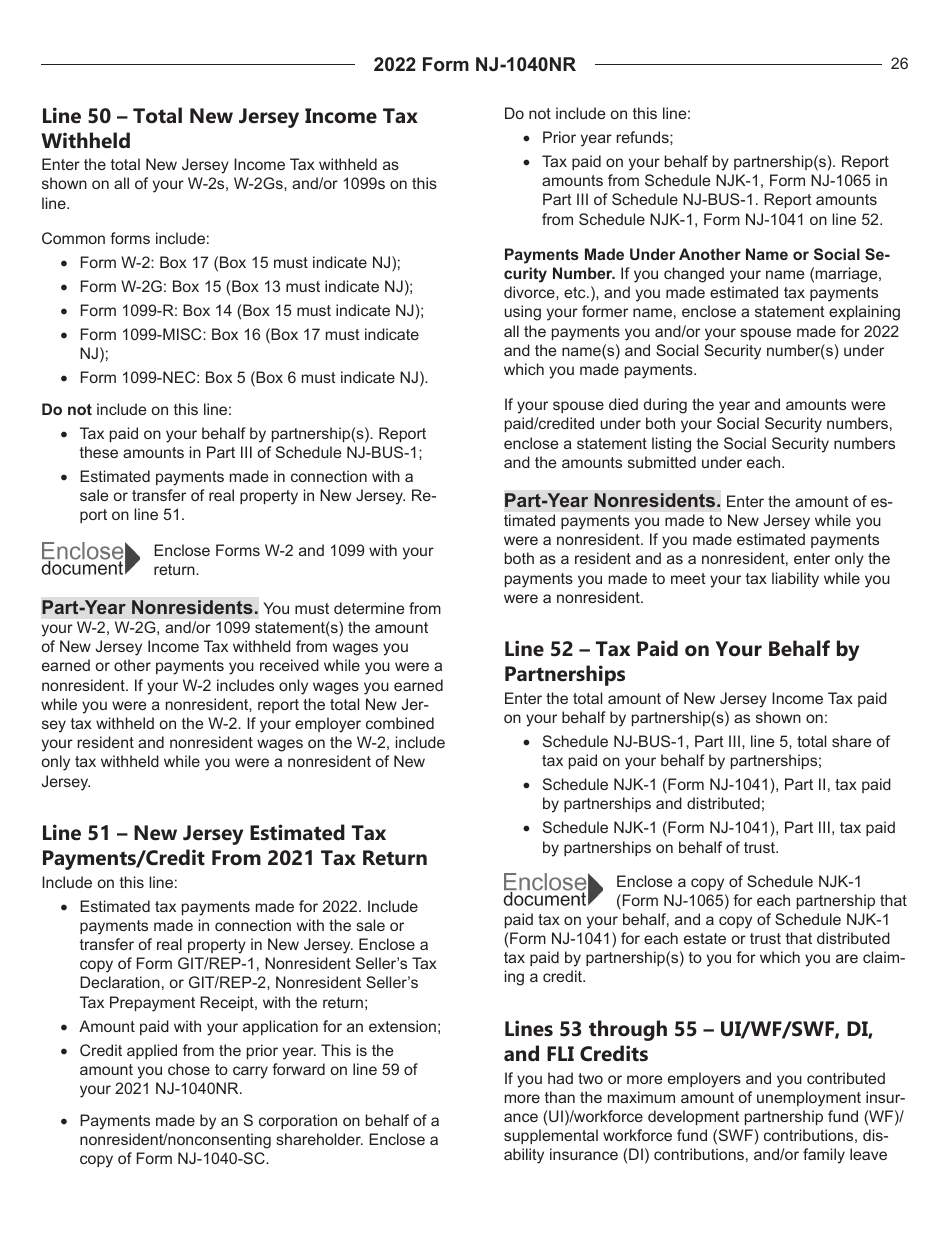
Line 16 is where most people land after starting with their federal AGI. You then go through Schedule A for itemized deductions or take the standard deduction on Schedule J, which is where New Jersey gets interesting because its standard deduction structure doesn't match the federal one. New Jersey allows a higher standard deduction for dependents in certain cases, and the amounts changed slightly for the 2022 tax year. I remember one file where a taxpayer had two college-age kids listed as dependents and the standard deduction calculation on Schedule J ended up being noticeably different from what you'd get if you just applied the federal logic across the board. That discrepancy added a few hundred dollars to their taxable income, which felt unfair until I worked through the actual schedule and saw how the brackets layer together. Line 43 is another trouble spot. This is where you report New Jersey pension exclusion, and the rules here have some quirks. If you're over 62, you can exclude up to a certain amount of pension income, but only the portion that was also excluded on your federal return counts toward that limit. People often overlook that coordination requirement and claim more on the state line than they should. I had a client once who tried to stack the full pension exclusion from both the federal and state sides without realizing the federal exclusion reduces the amount available for New Jersey. It cost him a correction and a small penalty, but the fix was straightforward once we went back through Schedule B. Social Security benefits follow the same pattern as federal treatment, meaning if they're not taxable on your federal return, they generally aren't taxable in New Jersey either. That's one part that stays simple. The more complex pieces involve out-of-state income adjustments, local service taxes if you live and work in different jurisdictions, and the Earned Income Tax Credit pass-through, which New Jersey handles separately from the federal credit.
Common Pitfalls and Where People Go Wrong
The most frequent error I see is misinterpreting the pass-through entity tax. New Jersey introduced a state and local tax passthrough election that lets certain entities pay tax at the entity level, and the deduction works differently than a standard SALT deduction. It shows up on Schedule NJ-1040-ET and flows to your return in a way that doesn't always align with how the instructions describe it. A lot of taxpayers and even some preparers get tripped up by the timing of when the election needs to be filed versus when the deduction is claimed on the individual return. Another area where the 2022 instructions have a quirk is the casualty loss deduction. New Jersey generally disallows casualty losses that are covered by insurance, but the rules around when a loss is considered covered versus not covered can be unclear depending on your policy terms. I ran into a situation last year where a homeowner had a water damage claim that was partially denied by the insurer. The instructions didn't spell out how to handle a partial denial, so I reached out to the division's taxpayer assistance line and got a response that said the deductible amount could still be claimed as long as the insurance didn't cover it. That wasn't obvious from reading the form alone. Don't skip the residency determination section if you moved during the year. New Jersey has a specific rule about domiciles and statutory residence that catches people who split time between states. If you maintained a permanent place of abode in New Jersey and spent more than 184 days elsewhere, you might still be considered a statutory resident depending on how your home office situation is set up. This came up with a contractor I worked with who kept a New Jersey apartment but spent most of the year on projects in Pennsylvania. The residency test initially flagged him as a full-year resident, and we had to dig through the statutory residence rules to establish his proper filing status.
Get the Full Details
Electronic Filing and Payment Logistics
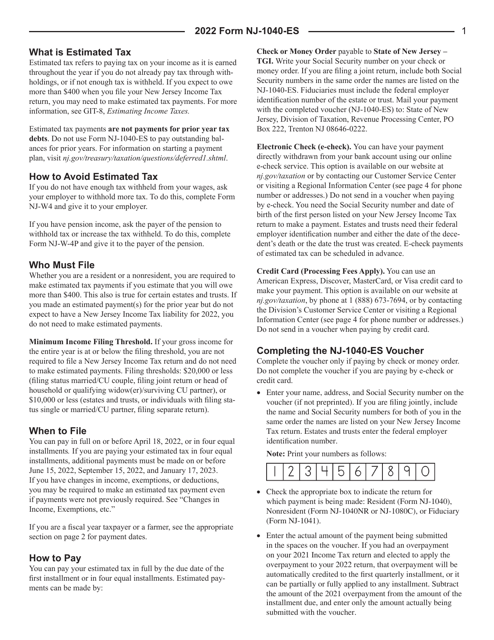
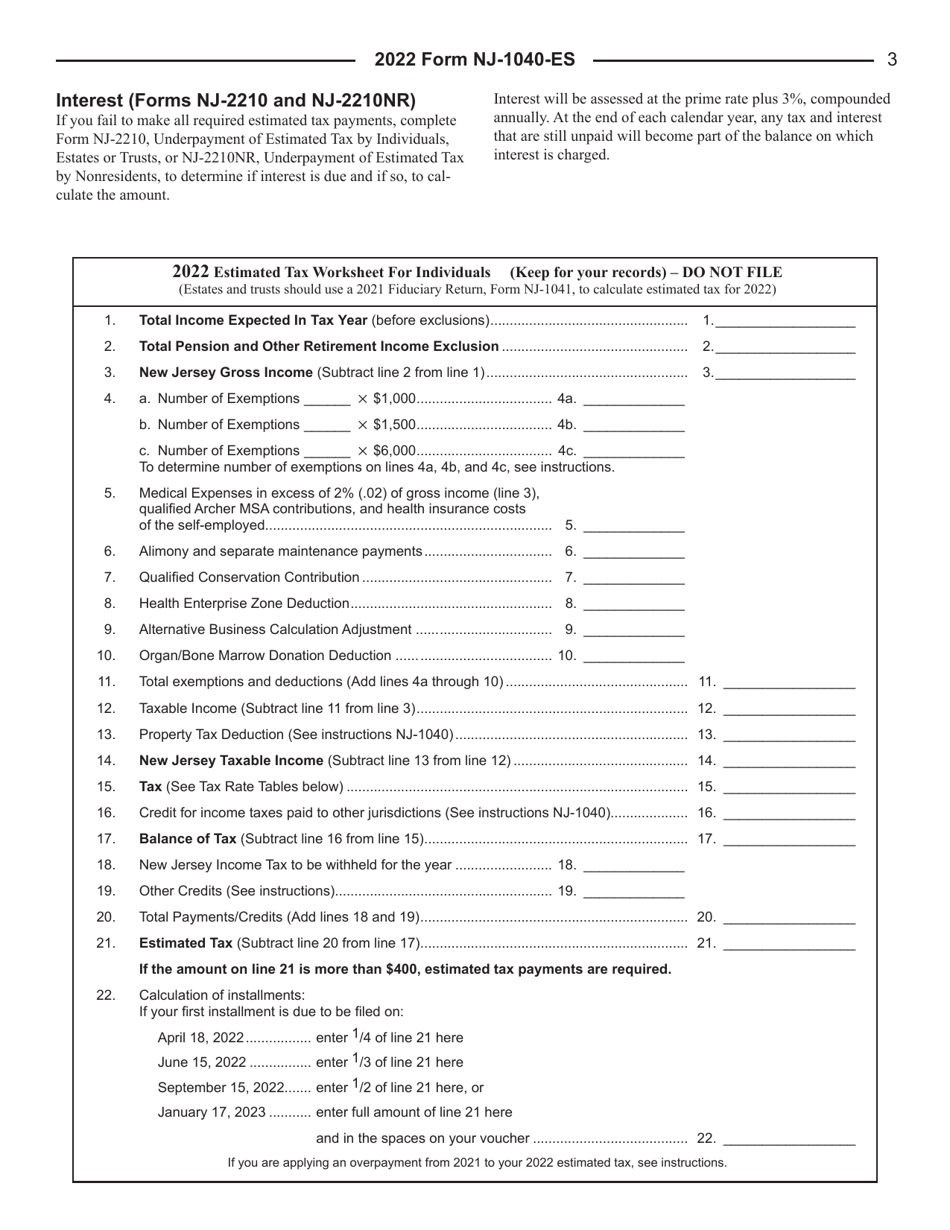
New Jersey pushes electronic filing hard, and the Free File program is available for qualifying taxpayers through the state's partnered platforms. If your adjusted gross income is below a certain threshold, you can file and pay through those platforms at no cost. Above that, you'll need commercial software or a preparer. Payment options include Electronic Funds Withdrawal, debit or credit card through an approved processor, and electronic check. The EFW option is the cheapest route since it avoids processing fees entirely. Extension filing follows the same timeline as federal, which means April 18th for 2022 returns unless the deadline shifts due to holidays or emergencies. New Jersey does offer an automatic extension if you file Form EXT-1040, and payment estimates should still be made to avoid the underpayment penalty. The penalty rate for 2022 was set at 1.5 percent per month, compounded monthly, up to a maximum of 18 percent. That's lower than some states but not trivial if you're looking at a large balance.
When the Instructions Fall Short
The biggest limitation of relying solely on the instruction booklet is that it doesn't always address edge cases that come up in real life. New Jersey updates its guidance through notices and bulletins throughout the year, and those don't always make it into the printed PDF you download. If you're dealing with something unusual like a multi-state apportionment issue, a complex trust distribution, or a disaster-related deduction, the form alone won't give you the full picture. Checking the division's notice archive for the relevant tax year usually fills those gaps. The instructions also assume you have your federal return already finalized, which works fine for most people but creates a bottleneck if you're amending. You can't finalize your New Jersey return until your federal return is locked in, and there's no provision for estimated state filings without a federal anchor. This is a structural limitation that applies to almost every state tax system, not just New Jersey, but it's worth keeping in mind if you're working on a tight timeline.