Understanding the gap between quoted rates and what you actually pay
I spent three years in corporate treasury managing working capital for a mid-market manufacturer. One of the first things I learned the hard way is that the interest rate on your loan isn't the rate you're really paying. The bank quotes one number. Inflation eats another chunk. The difference between those two numbers is where most business owners lose money without realizing it. This isn't theoretical. I saw a plant manager take out a six-month working capital line at 8.5% nominal rate, feel good about having liquidity, and then watch their real cost climb to 11% when inflation ran hot. That's the Nominal Vs Real Interest Rate question in plain English.
What the terms actually mean
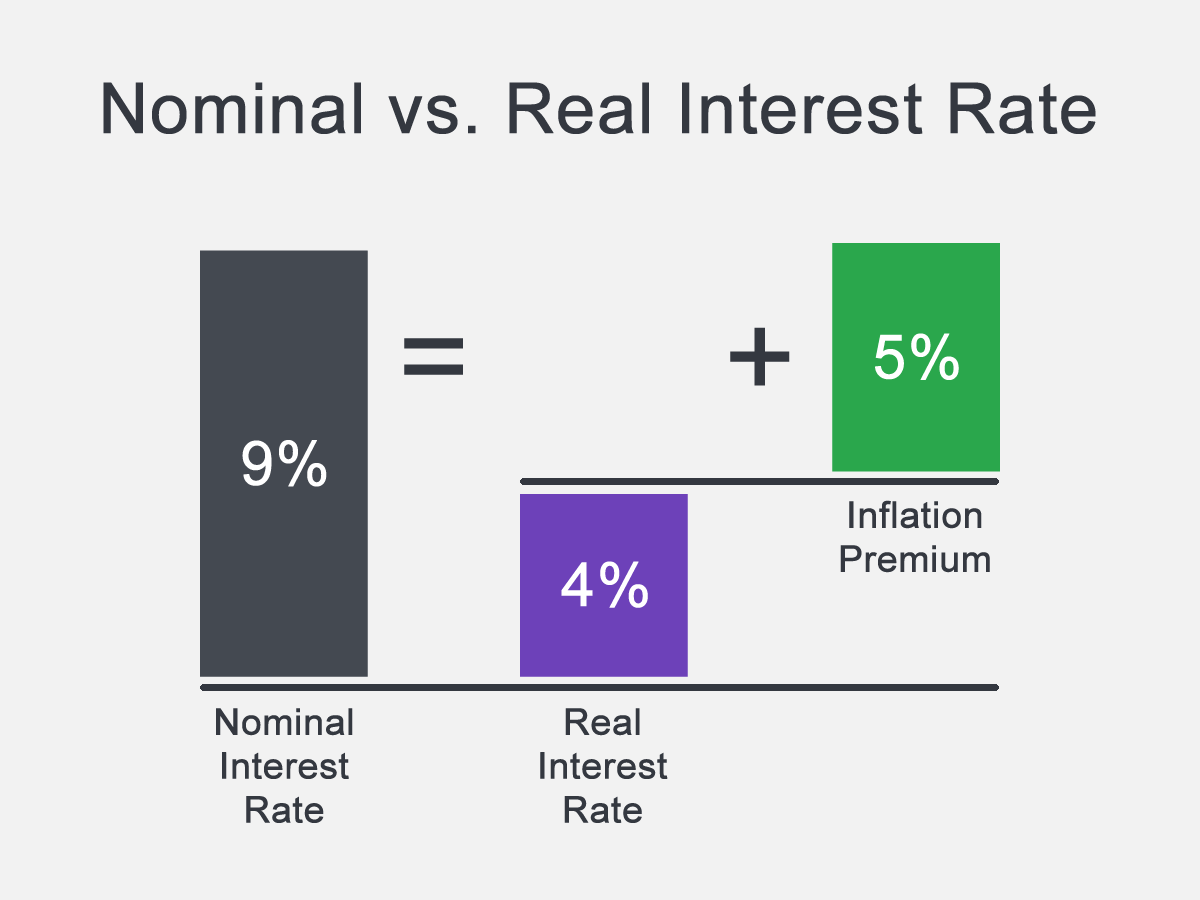
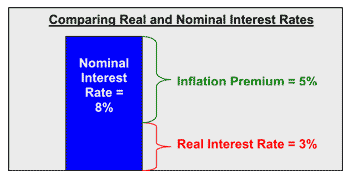
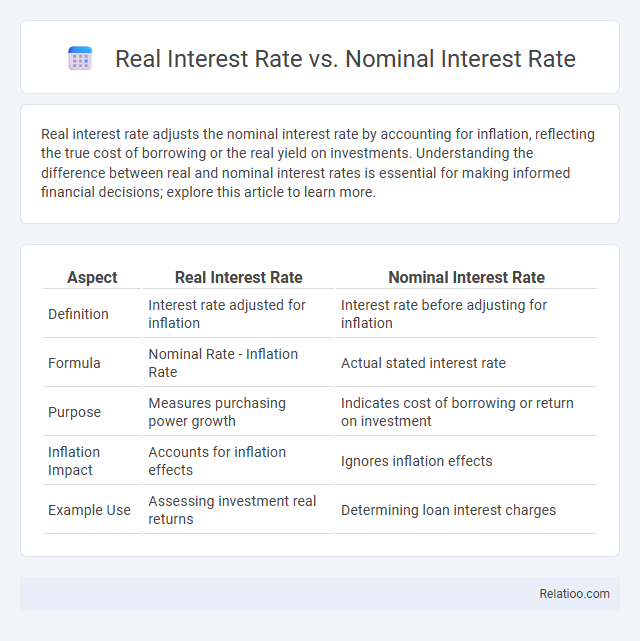
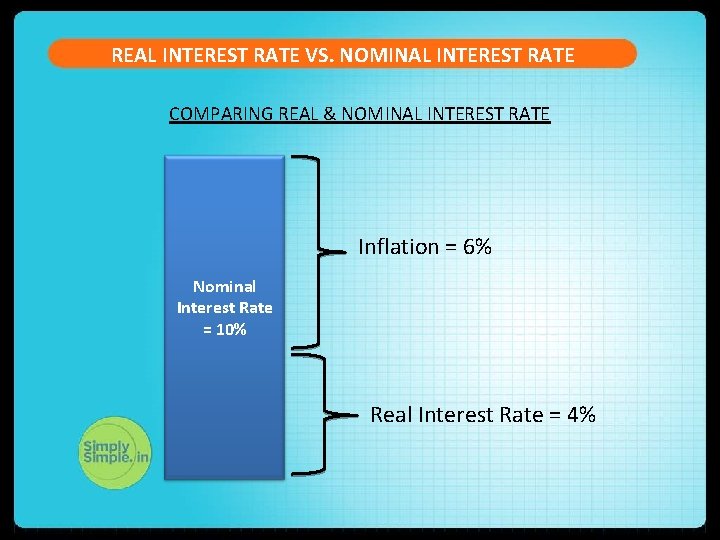
The nominal interest rate is the number printed on your contract. It's the percentage the lender charges you before adjusting for anything else. A car loan at 6.9%, a savings account yielding 4.2%, a corporate bond paying 5%—those are all nominal rates. They're straightforward. They're also incomplete. The real interest rate adjusts the nominal figure for inflation. It tells you what you're actually gaining or losing in purchasing power. The Fisher equation connects them: Real Rate Nominal Rate Inflation Rate
That approximation works fine for low inflation. At 3% inflation and a 6% nominal rate, your real return is roughly 3%. But when inflation runs above 10%, the approximation breaks down. The exact formula divides by one plus inflation: (1 + Nominal) = (1 + Real)(1 + Inflation) Solving for real rate means subtracting one from the product. At 15% inflation and 20% nominal, the exact real rate is about 4.3%, not the 5% the approximation would give you. That gap matters when you're locking in long-term debt.
Get the Full Details

Where this shows up in practice
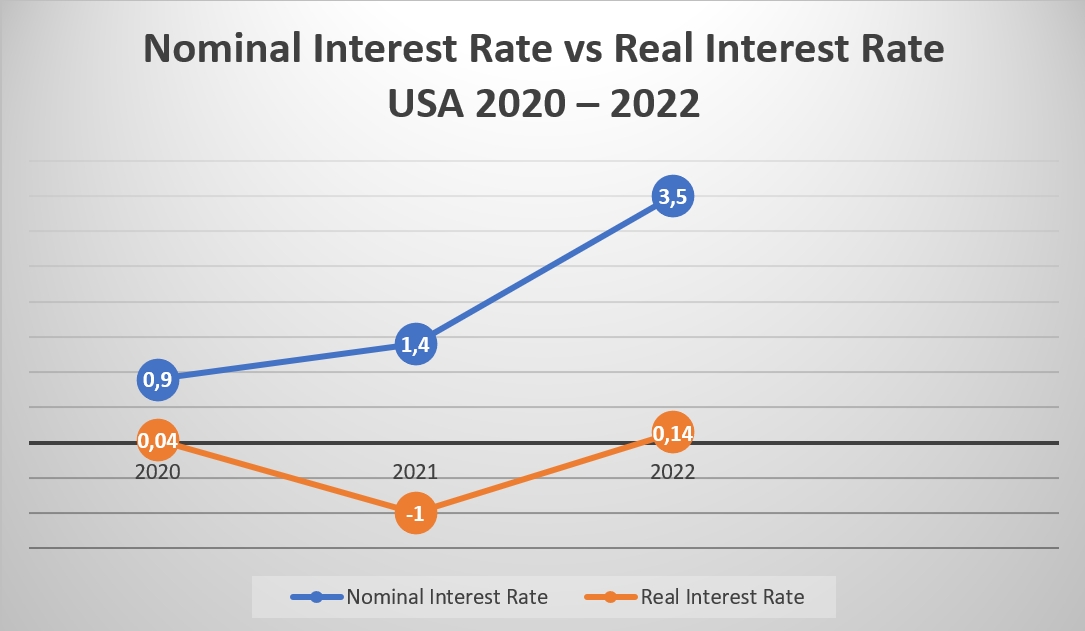
You encounter real rates everywhere. Mortgage borrowers care about them because their income is nominal. If your salary rises 5% a year but inflation runs 8%, your real purchasing power drops even though you're earning more dollars. That's why economists track real wage growth separately from nominal figures. Lenders face the opposite problem. A 7% bond sounds attractive until inflation hits 9%. The lender is losing purchasing power every year. That's why real yields on Treasury Inflation-Protected Securities (TIPS) exist—those adjust the principal for inflation so the real rate stays stable. Central banks set policy based on real rates, not nominal ones. The Federal Reserve's federal funds rate is a nominal target, but they adjust their stance when real rates turn too restrictive or too loose. When inflation runs at 6% and the Fed holds rates at 5%, the real rate is negative. That stimulus effect slows markets down less effectively than a rising nominal rate alone would suggest.
The edge case I wish I'd understood earlier
Here's a practical problem that burned me. Our company had a variable-rate credit facility tied to the prime rate. Prime moved quickly. We borrowed at 9.5% when prime hit 9%. Six months later, inflation spiked to 8.5%, and the real cost of that borrowing climbed to nearly 1%. That's dangerously close to free money, except we still had to make payments in nominal dollars. The workaround was simple but easy to miss. We renegotiated a portion into a fixed-rate note when inflation expectations rose. We locked in 7.5% for two years, knowing inflation might run higher, but the real rate would stay positive for us. It saved maybe $40,000 over the facility term on a $2 million line. Not dramatic, but it prevented cash flow squeezes that nearly caused us to delay payroll.
Advanced nuance: real rates can stay negative for extended periods
Most beginners think negative real rates are abnormal. They're not. Japan ran negative real rates for over a decade. Europe stayed there for years. When central banks suppress nominal rates below inflation to stimulate growth, savers absorb the loss quietly. That redistribution from creditors to debtors is the hidden function of monetary policy. Another counter-intuitive point: real rates don't predict nominal rates one-to-one. If investors expect higher inflation, they demand higher nominal rates, but the real rate might not move much. That's the Lucas critique at work—people adjust expectations, and models that ignore that fail. Always separate the expectation channel from the policy channel when analyzing real yields.
When the concept completely fails
Real rates become unreliable in hyperinflation. Zimbabwe, Venezuela, Argentina—the math still works, but the signal noise ratio destroys any practical use. When prices change daily, tracking inflation accurately requires indexation mechanisms that most emerging markets lack. In those cases, dollarization or foreign currency borrowing becomes the rational choice, even at higher nominal cost. Real rates also mislead when comparing different currencies. A 5% real rate in the US dollar isn't comparable to a 5% real rate in Turkish lira. Currency risk dominates. Always convert to a common purchasing power base using PPP exchange rates if you're comparing across borders.
How to calculate it yourself
Grab the nominal rate from your loan documents, savings statement, or bond prospectus. Then find the inflation rate using the CPI-U or your country's official consumer price index. Subtract inflation from nominal for a quick approximation. For precision, use the exact Fisher formula. Spreadsheet time: about 90 seconds per calculation. For TIPS, the real yield appears directly in financial data feeds. Bloomberg prints it as "TYKS." Reuters calls it "real yield." Your brokerage app may show it differently. Look for the inflation-adjusted yield, not the coupon rate. For mortgages, the real rate requires estimating future inflation, which is notoriously difficult. Most homeowners never calculate it. That's fine if you're locked in for 30 years and plan to hold. It's a mistake if you're refinancing and comparing jumbo vs conforming products—real cost differences swing the decision more than nominal rates suggest.
Download link for the reference sheet
I maintain a simple calculator that converts nominal rates to real rates using both approximation and exact methods. It includes a historical inflation table for major currencies back to 1960. You can download it here: nominal-real-interest-rate-calculator.xlsx. There's also a one-page reference card for the key formulas and common pitfalls. Download that here: nominal-vs-real-interest-rate-reference.pdf. Both files are open source. Fork them if you need adjustments for your specific market or currency pair.
Bottom line without the bottom line
Nominal rates tell you what you pay in dollars. Real rates tell you what you pay in purchasing power. The gap between them is inflation. Track both when borrowing, saving, or investing. Ignore the real rate at your peril, especially when inflation runs above 4% or when you're making multi-year financial commitments. The Fisher equation is basic macroeconomics. Every finance professional should have it memorized. If you can only remember one thing, remember that real rates drive long-term capital allocation decisions far more than nominal rates do. The market prices in nominal figures, but economic reality moves with real ones.