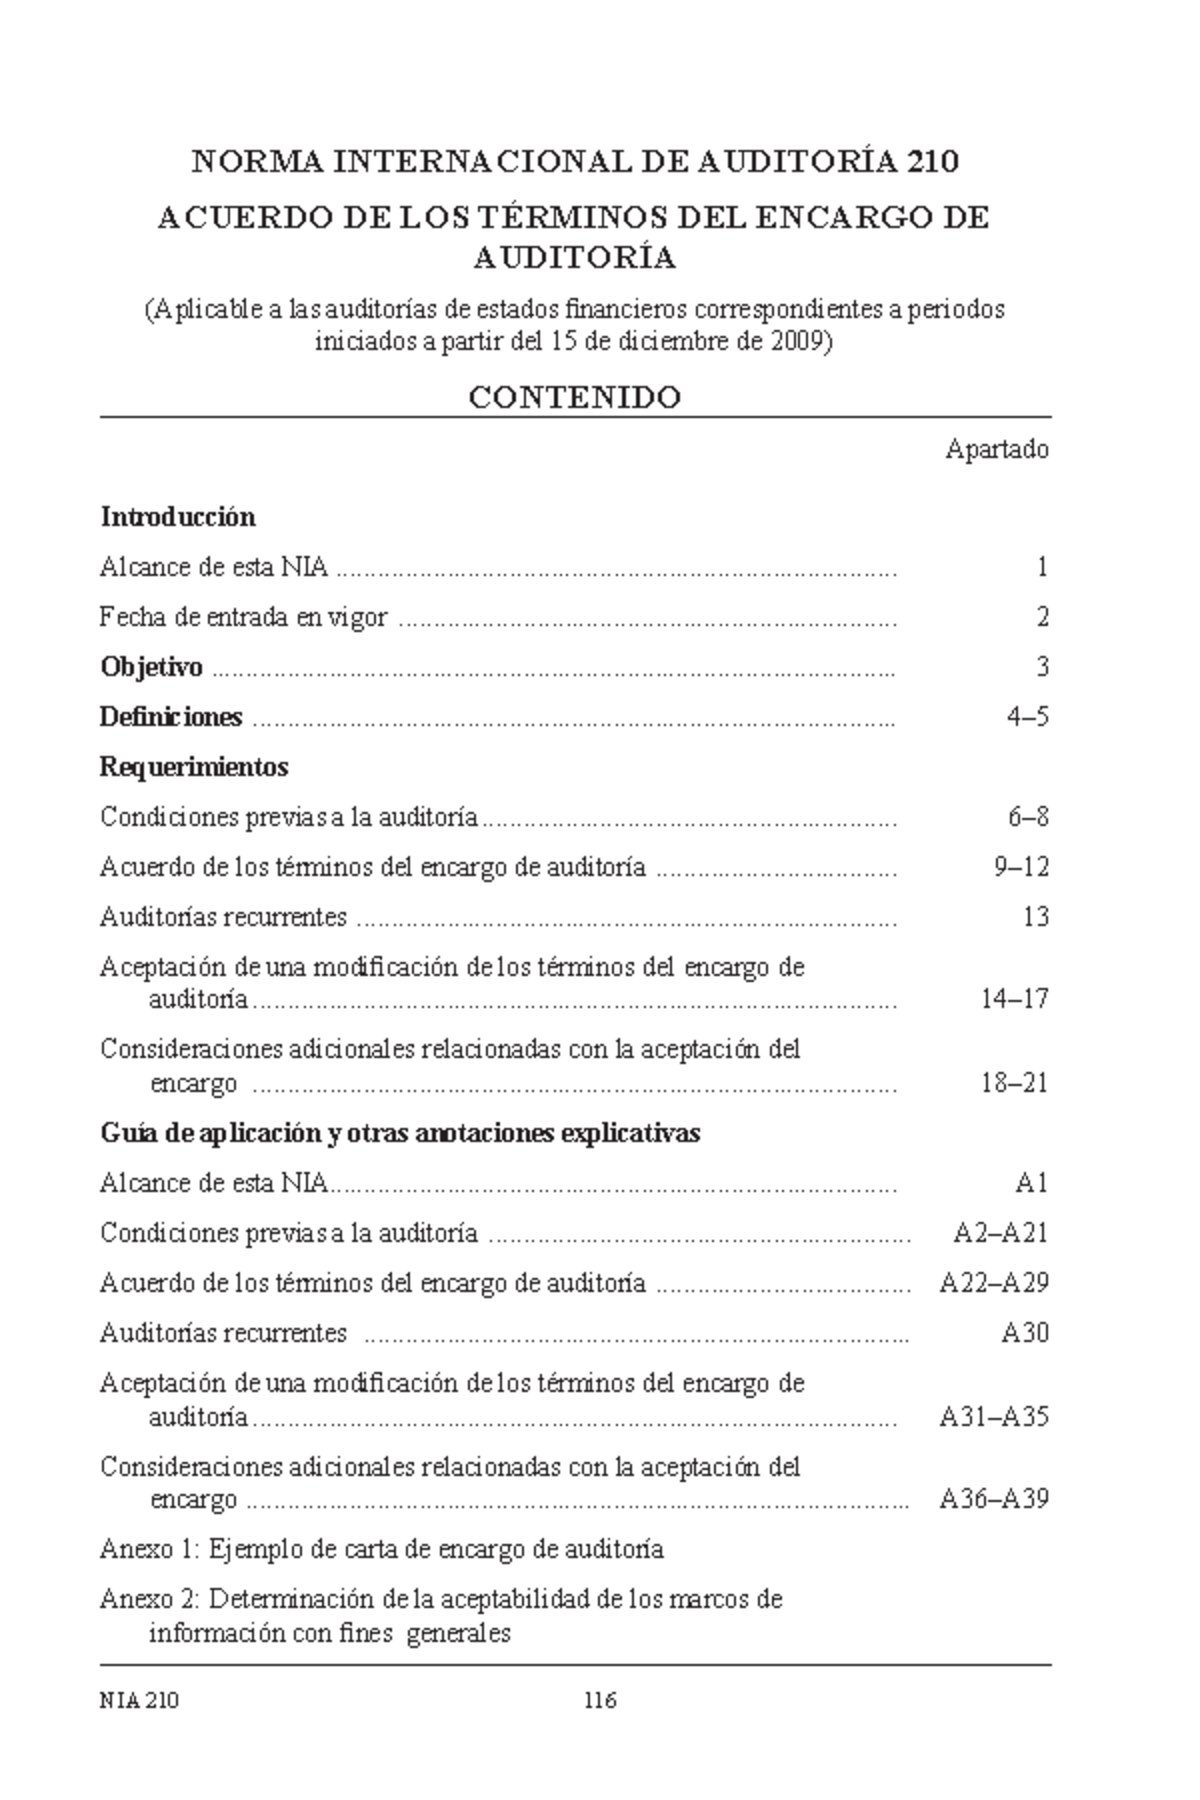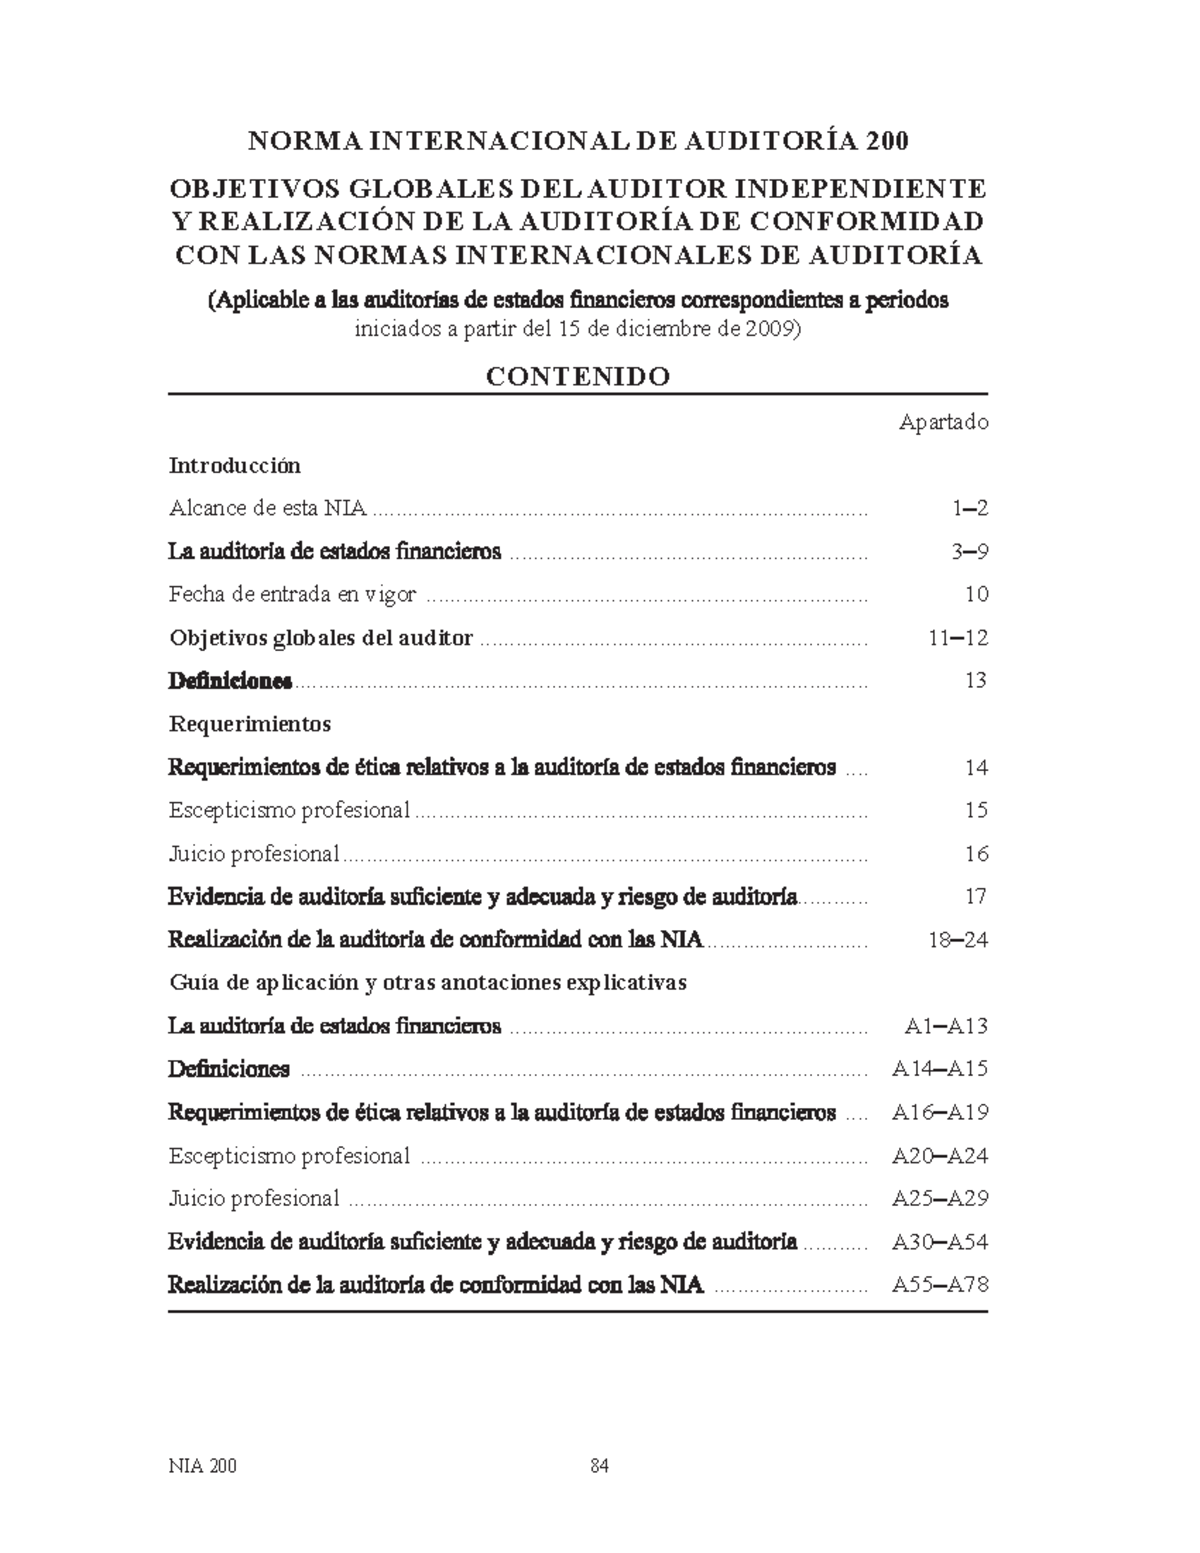
Understanding Norma Internacional De Auditor A: What It Actually Means In Practice
Most people encounter this standard when they need to prepare for an audit engagement or review a colleague's work. The document is more complicated than it looks at first glance. It covers the foundational requirements that every auditor must satisfy before signing off on anything. The International Framework of Quality Management, Ethics, Review and Other Assurance Services includes this as one of its core pillars. I spent years dealing with engagements where this standard was either ignored or misunderstood. One particular case stands out. A company was preparing for its annual statutory audit, and their internal team had already drafted financial statements using their own conventions. When we started the engagement under Norma Internacional De Auditor A, the first thing I noticed was that the materiality threshold they had set internally was completely arbitrary. They had picked a number that looked reasonable on paper but didn't account for the industry's typical risk profile. This is a real problem because materiality isn't just a calculation. It requires professional judgment based on the entity's specific circumstances. The workaround I used in that situation was straightforward but took time. I pulled together historical financial data going back five years, calculated average fluctuations in key line items, and cross-referenced industry benchmarks from the sector's regulatory filings. That gave us a materiality figure that actually held up under scrutiny. The internal team's original number would have been challenged by any reviewing partner.
Norma Internacional De Auditor A: Core Requirements Explained
This standard establishes the auditor's responsibilities when conducting an audit of financial statements. It covers everything from professional competence and ethical requirements to the planning and execution phases of an engagement. The document is structured around several key principles that are non-negotiable. Independence is one of the most critical aspects. I've seen firms lose their licenses over this. The standard requires both independence in fact and independence in appearance. The second part is often overlooked. Even if your team is technically independent, if a reasonable and informed third party would question that independence based on the available information, you are in violation. I worked with a firm that had a long-standing relationship with one of their audit clients. The client's CFO happened to be the sister-in-law of the firm's senior partner. There was no financial interest involved. Nothing improper. But when we learned about it during a routine quality review, we immediately recused ourselves from that engagement. Better to lose one client than to risk your entire practice. Professional skepticism is another area where most auditors struggle. The standard expects you to approach every audit with a questioning mind. This doesn't mean assuming management is dishonest. It means not accepting explanations at face value without sufficient appropriate audit evidence. In my experience, the auditors who get into trouble are rarely the ones who are too skeptical. They are the ones who become too comfortable with a client over time.
Common Pitfalls That Beginners Miss
There are several nuances that aren't obvious unless you have actually managed an audit from start to finish. One of the most important involves the concept of sufficient appropriate audit evidence. The word "appropriate" gets less attention than it deserves. You can collect more evidence than necessary, but if that evidence isn't relevant to the assertion you are testing, it is worthless. I've reviewed engagement files where junior auditors had spent weeks gathering documentation that addressed the wrong risk. The engagement partner had to essentially redo the work. This typically adds three to four weeks to the audit timeline and significantly increases costs for the client. Another pitfall relates to the use of internal audit work. The standard allows external auditors to use the work of internal auditors when appropriate. However, many auditors misinterpret this provision. Using internal audit work doesn't mean you can outsource your responsibility. You still need to evaluate the competence and objectivity of the internal audit function and perform procedures on their work. I once encountered a situation where a firm relied entirely on an internal audit department that reported to the CFO of the same entity they were supposedly auditing. That is a clear conflict. The internal audit function had no independence from management, and therefore their work could not be relied upon under this standard. The standard also places significant emphasis on documentation requirements. Every significant judgment, every conclusion reached, and every piece of evidence considered must be documented. The documentation should be sufficient to enable an experienced auditor, having no previous connection to the engagement, to understand the work performed and the conclusions reached. This is not a suggestion. It is a requirement. I have seen audits delayed by weeks because documentation was incomplete. In one case, a review team spent two days reconstructing conclusions that should have been recorded in real time.
Get the Full Details
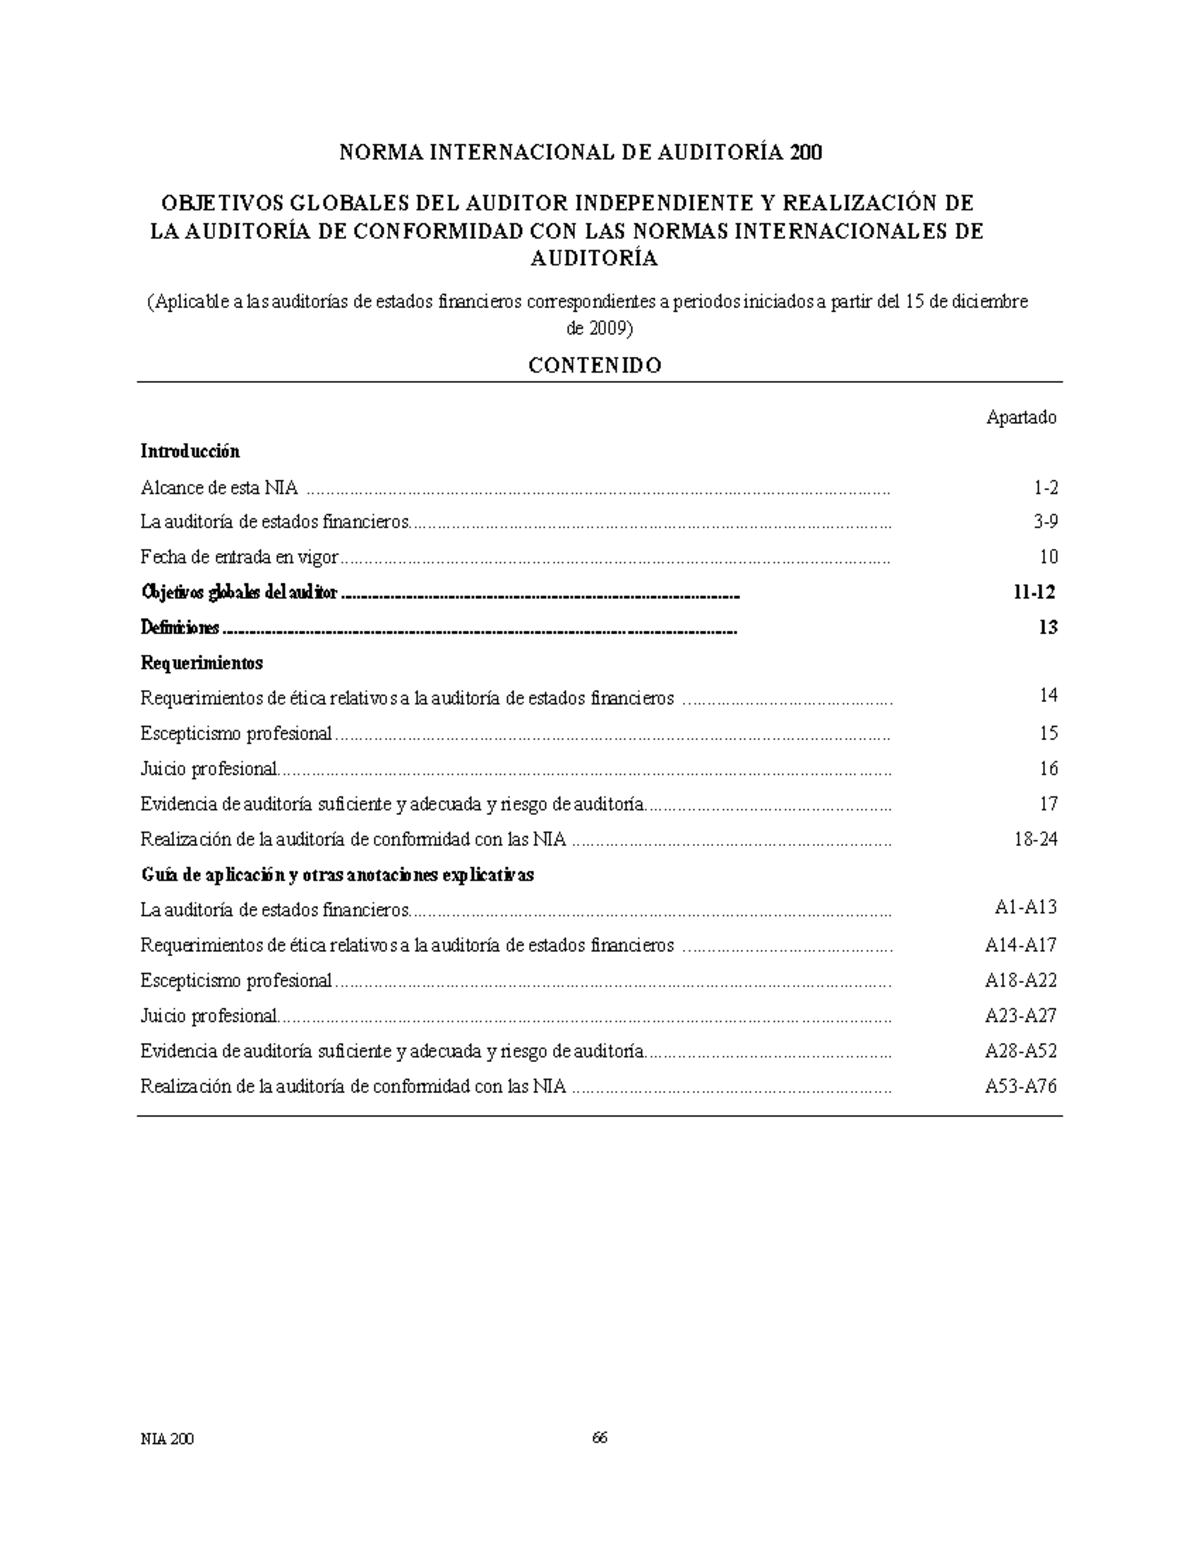
When This Standard Doesn't Apply
It is important to understand the limitations of this standard. It applies to audits of historical financial statements conducted in accordance with International Standards on Auditing. It does not cover agreed-upon procedures engagements, reviews, or other assurance services. If you are conducting a review engagement, you are working under a different standard entirely, and the level of assurance provided is lower. Confusing these two types of engagements is a common mistake, and it can lead to serious legal liability for the firm. Another limitation is that this standard assumes the financial reporting framework applied is acceptable. If management uses a special purpose framework that is not appropriate for the entity's circumstances, you may need to consider whether to accept the engagement at all. I recall a case where a company wanted to prepare financial statements using cash basis accounting rather than accrual basis. The standard permits this in some jurisdictions, but the auditor needs to ensure that the framework is acceptable and that the financial statements include adequate disclosure about the basis used. Failure to address this can result in a modified opinion or refusal to issue a report.
Practical Steps For Implementation
If you are responsible for ensuring compliance with Norma Internacional De Auditor A, start with a comprehensive understanding of the standard's requirements. Read the full text carefully. Don't rely on summaries or secondhand interpretations. The standard has been updated several times, and each revision addresses specific concerns that arose from real-world engagement failures. Next, establish internal quality control procedures that align with the standard's requirements. This should include policies for independence verification, professional development, engagement performance, and monitoring. The standard expects firms to operate within a system of quality management that provides reasonable assurance that the firm and its personnel comply with applicable standards and regulatory requirements. Training is another area that deserves attention. I have found that the most effective approach is not to conduct a single annual training session and call it done. Instead, integrate the standard's requirements into your ongoing engagement processes. Use engagement team meetings to discuss how the standard applies to specific situations. Have senior staff review each other's work with the standard's requirements in mind. This creates a culture of compliance rather than a checklist mentality.
Documentation should be approached systematically. Develop templates and checklists that align with the standard's requirements. These should not be so rigid that they stifle professional judgment, but detailed enough to ensure consistency across engagements. In my experience, well-designed documentation templates can reduce the time spent on engagement files by approximately twenty percent without sacrificing quality.

Where To Find The Official Document
The International Auditing and Assurance Standards Board publishes the full text of this and related standards. You can access the complete document on their official website. The standard is updated periodically, so always verify that you are using the current version. Outdated references can create compliance issues and expose your firm to unnecessary risk. The current version is regularly revised to reflect changes in the auditing landscape, including developments in technology, new financial reporting standards, and lessons learned from recent high-profile audit failures. Some professional bodies and accounting firms also provide commentary and implementation guidance. While these resources can be helpful, they should not replace the actual standard. The standard itself is the authoritative source. Commentary is interpretive and may reflect the perspective of a particular organization. If there is a conflict between commentary and the standard, the standard always takes precedence. I have personally encountered situations where relying on secondary commentary led to incorrect application of the standard. A firm I consulted for had followed an interpretive guide that suggested a particular approach to documentation. The approach was consistent with the commentary but did not fully meet the standard's requirements. When we identified the discrepancy, we had to supplement the engagement documentation substantially. This took additional time and resources that could have been avoided if the firm had consulted the original standard directly.
The bottom line is that this standard is not optional. If you are conducting an audit under International Standards on Auditing, compliance is mandatory. Understanding it thoroughly and implementing it consistently is what separates professional auditors from amateurs. The standard exists for a reason. It has been developed through decades of practice, review, and refinement. Ignoring its requirements or treating them as suggestions is a recipe for engagement failure, legal liability, and reputational damage.