
Why Your ODE Solver Keeps Diverging
I spent three weeks debugging a coupled system of five differential equations last fall because I assumed my default RK45 integrator was doing what it was supposed to do. It wasn't. The solution blew up past t = 8.2 because I had missed a stiffness boundary I hadn't even realized existed. The fix wasn't changing the solver. It was scaling the state variables so the Jacobian wasn't dominated by one column while the rest stayed near zero. This is the part most textbooks skip. They teach you Runge-Kutta and call it a day. In practice, getting reliable Numerical Solutions Of Differential Equations usually means understanding when your equations refuse to behave like textbook examples, and that's where most people hit a wall.
Numerical Solutions Of Differential Equations: Where It Actually Breaks
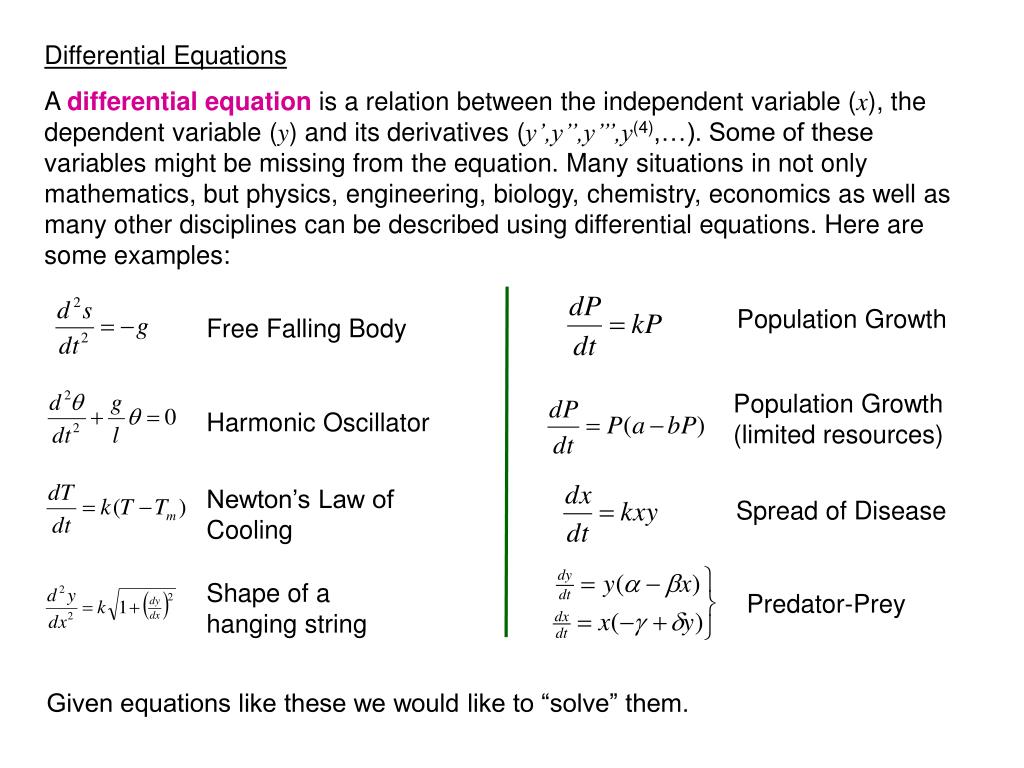
A first-order ODE like dy/dt = f(y, t) looks straightforward on paper. Euler's method gets you the right answer in the limit. But stepping forward with a fixed timestep on anything non-linear quickly produces garbage. The solution drifts, then oscillates wildly, then exits through the ceiling of your plot range. The pragmatic approach starts with classifying the problem. Stiff systems require different treatment than smooth ones. A stiff ODE is one where explicit methods force you into impractically small timesteps just to maintain stability, even though the solution itself is smooth. The classic example is the van der Pol oscillator when the damping parameter mu exceeds about 10. Your timestep has to shrink by orders of magnitude, and wall-clock time explodes. I ran into this exact situation with a reactor kinetics model where neutron population dynamics operated on millisecond timescales while temperature feedback ran on seconds. Running an explicit Adams-Bashforth method with adaptive stepping meant the solver was effectively stuck in milliseconds for the entire integration window. Switching to an implicit BDF method, specifically VODE or LSODA which auto-detects stiffness, cut runtime from roughly 40 minutes to under two on the same hardware. That is not a marginal improvement.
Getting From Equation to Output
Start by writing your system in standard form. If you have a second-order equation like y'' + 2y' + y = sin(t), you convert it to a system by defining u = y and v = y'. Then du/dt = v and dv/dt = sin(t) - 2v - u. This looks trivial until you are juggling twelve coupled equations and the conversion introduces subtle indexing bugs that silently corrupt your results. From there, pick a method based on your constraints. For a quick single-shot integration with moderate accuracy demands, an embedded Runge-Kutta pair like Dormand-Prince (RK45) with adaptive step control is the default for good reason. Scipy's solve_ivp implements this, and it handles most non-stiff problems without requiring much tuning. Set a reasonable maximum timestep and let the error controller do the work. The overhead of step-size adjustment is usually 10 to 20 percent more compute than a fixed-step method, but it prevents you from walking into instability zones blindly. When the system is stiff, switch to BDF methods. Backward Differentiation Formulas are implicit, meaning each step requires solving a nonlinear algebraic system. Newton iteration inside the solver does this work. The computational cost per step is higher, but the timestep can be orders of magnitude larger. The tradeoff is real and worth understanding before you blame the wrong thing when your solver hangs.
Get the Full Details

Handling Boundary Value Problems
Initial value problems are the easy case. Boundary value problems where conditions are specified at two different points require a different strategy entirely. Shooting methods work by guessing the missing initial condition and integrating forward until you check whether the far boundary condition is satisfied. Then you adjust the guess using a root-finding algorithm like Brent's method or a Newton update based on the sensitivity of the endpoint to the initial guess. The shot method fails when the problem is sensitive enough that small changes in the initial guess cause exponential divergence. I encountered this with a heat transfer problem across a composite wall where thermal conductivity changed discontinuously at an interface. The shooting method oscillated between wildly different solutions and never converged past three iterations. Switching to a collocation method using a finite-difference discretization across the domain and solving the resulting nonlinear system with a sparse Newton-Krylov solver was the only path that worked reliably. It took more setup time upfront but produced a clean result on the first run. For PDEs, the spatial discretization choice matters as much as the time integration. Method of lines is the standard framework: discretize the spatial derivatives to get a large system of ODEs, then hand that system to an ODE integrator. The quality of your spatial stencil directly affects how stiff the resulting ODE system becomes. A second-order centered difference on a fine grid can make an already stiff system completely impractical for explicit methods.
Practical Pitfalls That Waste Days
Event detection is one of those features everyone forgets about until they need it. If your system has discontinuities or thresholds, like a control switching on at a temperature limit, a standard integrator will sail right through the event without noticing. You need to use event functions that stop the integration, trigger a state change, and then resume. Most production ODE libraries support this natively. Don't try to hack it with post-processing logic afterward. Another common failure mode is ignoring units consistency. When I once mixed a model written in SI units with a subsystem using CGS without converting, the solver produced perfectly valid output that was off by factors of ten in half the state variables. The numbers looked physically reasonable, which made catching the bug take longer than it should have. Every variable needs a clear unit context documented at the point of definition. Conservation properties are another area where naive implementations quietly fail. If you are integrating a Hamiltonian system with a standard explicit method, energy will drift over long time intervals. Symplectic integrators preserve the geometric structure of the phase space and keep energy bounded over arbitrarily long integrations. If your problem involves orbital mechanics or molecular dynamics, this is not optional. Using a leapfrog or Stormer-Verlet scheme instead of RK45 for a satellite trajectory simulation changed my energy drift from growing linearly with time to staying bounded within numerical precision for the entire integration window.
Verification and Validation
Running a solver once and trusting the output is where most people get burned. The minimum verification step is a timestep convergence test. Run the same problem with your default tolerance, then halve the tolerance twice more. If the solution changes significantly between runs, your tolerances are too loose. If it doesn't change, your tolerances might be unnecessarily tight and you are wasting compute. For problems where an analytical solution exists, use it as a reference. The logistic equation, damped harmonic oscillator, and a few others have closed-form solutions that are useful for sanity checks. When no analytical solution is available, compare against a highly resolved reference solution computed with very tight tolerances, or use a method of known order to estimate the error independently. Code verification with the method of manufactured solutions is worth the investment if you write your own integrator. You construct a fake exact solution, derive the forcing term that makes it exact, and then verify your code reproduces that solution at the expected convergence rate. This catches implementation errors that unit tests with trivial right-hand sides will never reveal.
Resources and Tools
For production work in Python, scipy.integrate.solve_ivp covers most initial value problems with a clean interface. The method parameter lets you choose between RK45, BDF, and LSODA, which automatically switches between explicit and implicit based on detected stiffness. For boundary value problems, scipy.integrate.solve_bvp is adequate for simple cases but can struggle with strongly nonlinear or highly stiff systems. In those situations, COLNEW through the scikits.odes package or PETSc's SNES solvers with appropriate KSP preprocessing give you more control. If you are working in C or Fortran, SUNDIALS is the industry standard suite. CVODE handles stiff and non-stiff IVPs, IDA handles differential-algebraic equations, and KINSOL solves the nonlinear systems that arise in BVP collocation. These are well-tested, actively maintained, and used in many production codes where reliability matters more than convenience. For Julia users, the DifferentialEquations.jl ecosystem is noticeably more extensive than what most Python packages offer out of the box. The auto-diff between explicit and implicit methods, the GPU acceleration options, and the broader family of specialized solvers for stochastic and delay equations make it worth the learning curve if you are doing serious numerical work in that language.
Common Mistakes in Numerical Solutions Of Differential Equations
Setting absolute tolerance to zero is a frequent error. The solver cannot drive the error below the tolerance floor you impose, and some methods will fail or stall when you request exactness. A reasonable abs_tol of 1e-12 or 1e-14 is usually appropriate depending on your problem scale. Setting it to zero effectively tells the solver to ignore that constraint entirely, which can cause internal inconsistencies. Another mistake is treating the solver as a black box without monitoring the internal timestep history. If your average timestep drops below your minimum allowed value consistently, the solver is spending most of its time trying to satisfy stability rather than accuracy. This is a clear signal that either your method is wrong for the problem or your equations need reformulation. Ignoring this warning and waiting for completion is how you waste hours on a broken setup. Parallel integration is not a silver bullet. While multiple shooting or parallel-in-time methods exist, they introduce additional complexity that often outweighs the benefit for single-problem integrations. If you need to integrate many parameter variations, vectorize across parameters rather than trying to parallelize within a single solve. The overhead of coordinating parallel solves within one trajectory usually costs more than simply running sequential solves on available cores.
The fundamental issue with numerical ODE integration is that you are always trading accuracy, stability, and computational cost against each other. There is no configuration that minimizes all three simultaneously. The practical skill is recognizing which constraint is binding in your particular problem and adjusting accordingly. A stiff chemical kinetics system and a smooth orbital mechanics problem require fundamentally different solver configurations even though they share the same mathematical form. Understanding that distinction and having the toolbox to address both is what separates people who get answers from people who get reliable answers.


