Understanding the NY IT-2104 Withholding Allowance Certificate
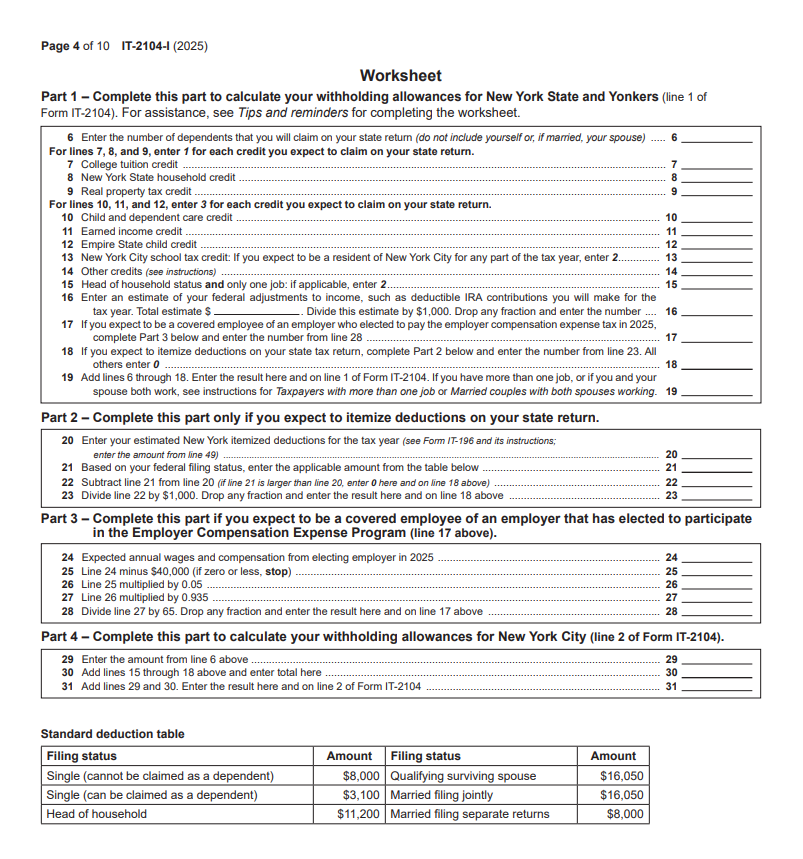
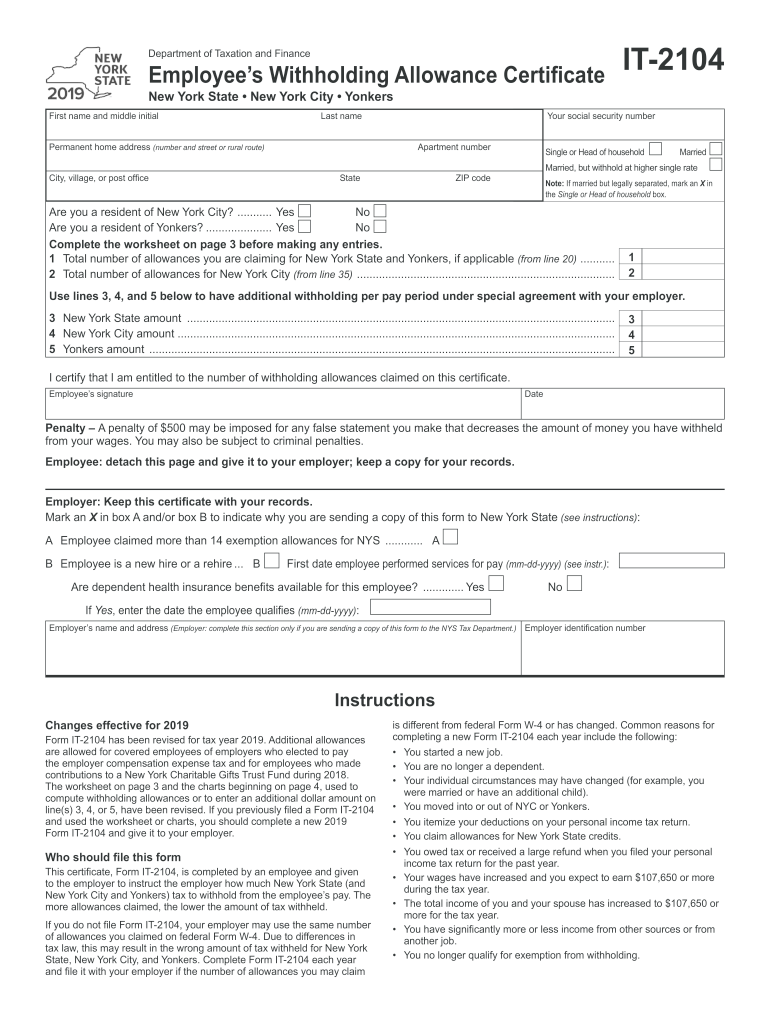
The NY IT-2104 is the form New York State uses to determine how much income tax to withhold from your paycheck. It functions the same way as the federal W-4 — you claim allowances that tell your employer whether to withhold more or less tax. Getting it right matters because a wrong entry means you either lose money throughout the year or owe a lump sum at filing time. I have seen both happen repeatedly. Start with Part 1, where you enter your personal information — name, address, and Social Security number. This is straightforward. Part 2 is where people typically make mistakes. You are asked to claim a certain number of withholding allowances, and the number you pick directly controls your take-home pay. More allowances means less tax withheld each paycheck. Fewer allowances mean the opposite. The worksheet portion of the form walks you through the calculation. It asks about your filing status, dependents, additional income, and deductions. If you have a straightforward W-2 job and nothing unusual, the math is simple. You claim one allowance for yourself, then additional allowances for each qualifying dependent listed on your tax return. The New York instructions provide a table that maps those inputs to a total allowance count.
Here is something most beginners miss. The IT-2104 does not use a flat deduction-per allowance system the way the old federal method did. New York applies its own bracket structure after calculating allowances, and the brackets shift slightly every year. A result that looked correct two years ago might be off now. Always check the current year's instructions rather than assuming your old number still applies. I ran into a specific edge case last spring involving a client with two jobs. The IT-2104 instructions say you can only submit one form per employer, but they do not explicitly warn that spreading allowances across two jobs can underestimate your total withholding. I had this person claiming four allowances on job one and three on job two, thinking they were simply splitting their household exemptions. Their combined withholding fell short because New York's tax brackets are progressive and the jobs together pushed them into a higher bracket than either job alone would suggest. The fix was reducing one of the forms to zero allowances and leaving the other at the calculated total, which brought the withholding back in line with their actual liability.
When to Submit a New IT-2104
You should submit a fresh form whenever your personal or financial situation changes significantly. Marriage, divorce, a new dependent, or a second job all qualify. The form itself says you must provide a new one within thirty days of any change. Employers are required to keep it on file and update their withholding records accordingly. There is also a scenario where submitting a new IT-2104 makes sense even without a life change. If you receive a significant bonus or overtime that pushes your annual income into a higher bracket, the original allowance count becomes inaccurate mid-year. Filing a revised form then prevents a large tax bill in April.
Get the Full Details
Common Pitfalls to Avoid
The biggest mistake I see is people treating the IT-2104 as a one-time form and never reviewing it again. Tax law changes, bracket thresholds adjust, and personal circumstances shift. An outdated form is worse than no form at all because it creates a false sense of security. Another frequent error involves the exemption for dependents. New York allows a personal exemption for each dependent claimed on your return, but the exemption amount is capped. If you have more dependents than the cap allows, claiming the full amount on the IT-2104 will under-withhold. The worksheet on the back of the form is supposed to catch this, but the calculation is easy to rush through. I have caught three cases this year alone where the taxpayer missed the cap and ended up owing several hundred dollars at filing. A third issue is the interaction between the IT-2104 and the New York City resident tax. If you live in NYC and work there, you may also need to file a form for city withholding. The state and city forms are separate, and the allowance calculations do not automatically carry over. Treating them as interchangeable is a reliable way to end up under-withheld on one of them.
Alternatives If the IT-2104 Does Not Fit Your Situation
If your income is irregular, self-employed, or primarily from investments, the standard IT-2104 worksheet may not produce an accurate withholding estimate. In those cases, making estimated tax payments through quarterly VTR forms is often the better path. Fixed percentage withholding is another option if your employer allows it, though it does not account for deductions or credits the same way the allowance method does. The IT-2104 works well for typical wage earners with predictable income and standard deductions. It breaks down when your financial picture is complex, your income fluctuates, or you have multiple withholding sources that interact in ways the worksheet does not model. Knowing the boundary of when it works and when it does not is what separates a competent approach from a guess. You can download the current year's form and worksheet from the New York State Department of Taxation and Finance website. Make sure you are grabbing the latest revision, since the allowance tables are updated annually and using an outdated version introduces errors that are difficult to trace back to their source.