What you actually need to know about the Small Business Health Options Program
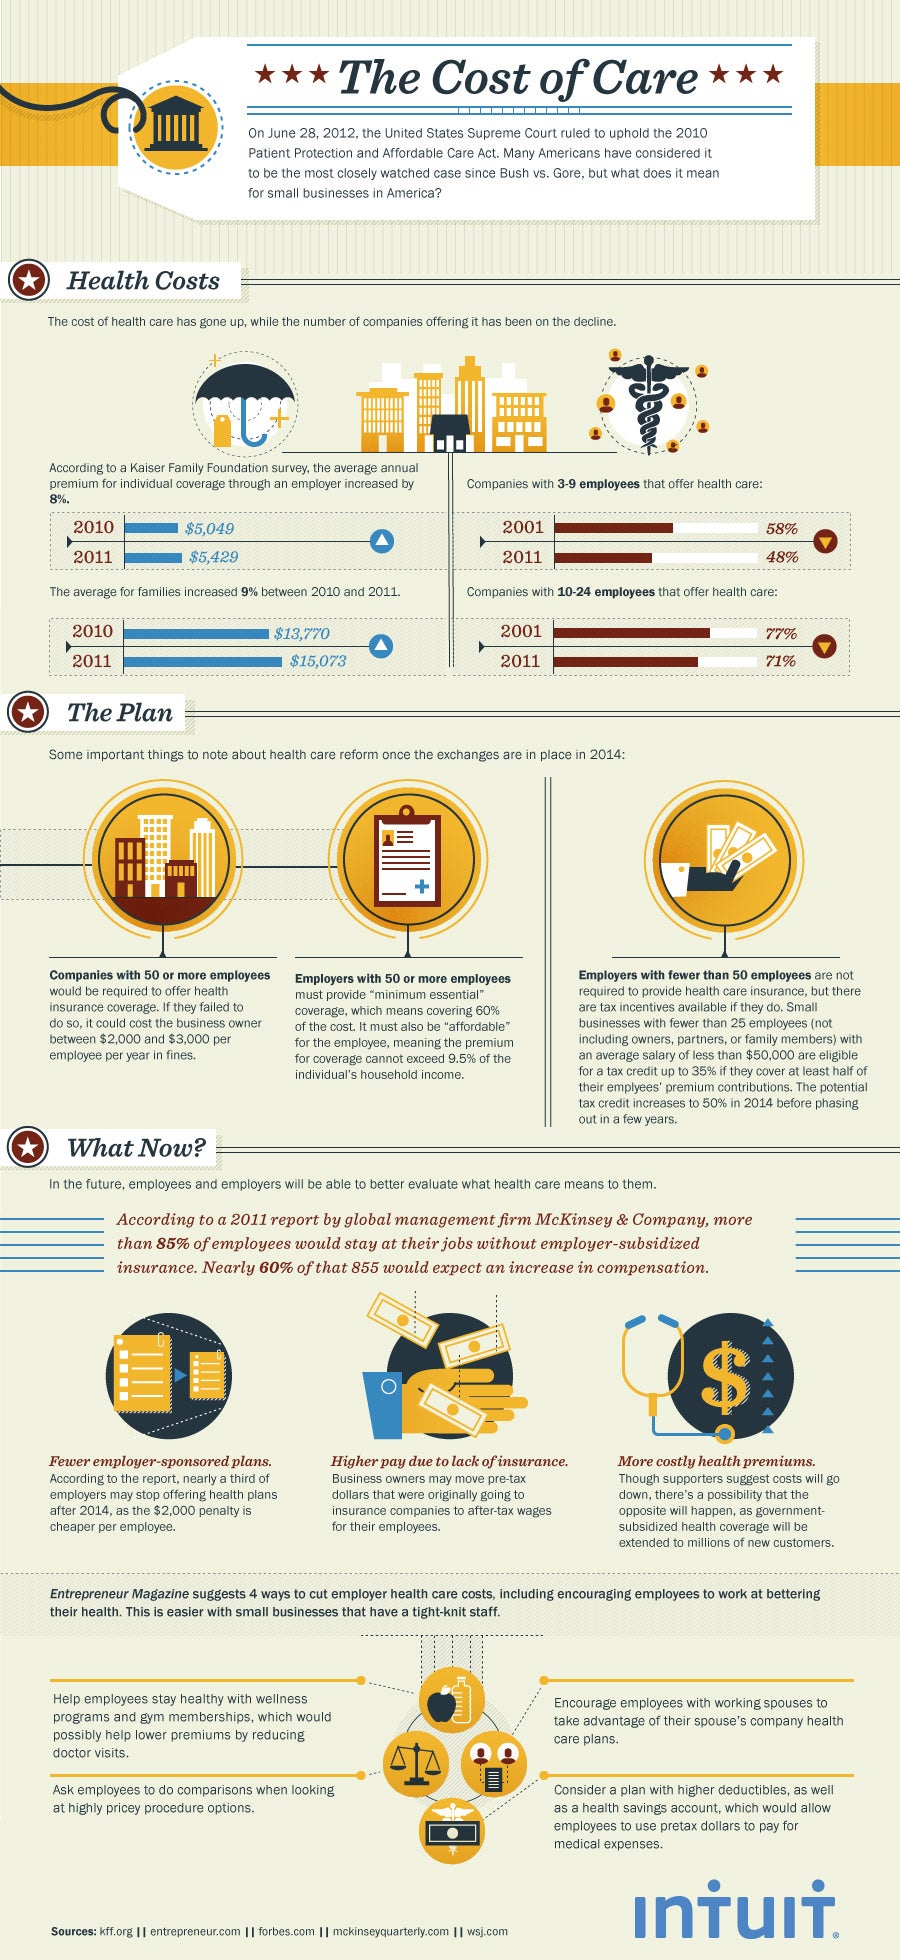
I have dealt with small business health insurance enrollment since the ACA marketplace opened up. The main program people mean when they say Obama Care For Small Business is called the Small Business Health Options Program, or SHOP. It is a state-run or federally-run marketplace where businesses with one to 50 full-time equivalent employees can shop for group health plans. Some states expanded it to 100 employees. The IRS also tracks these through the employer mandate rules. The process starts with figuring out your full-time equivalent employee count. This is not as simple as counting heads. You have to calculate FTEs by adding up total hours worked by part-time workers over a measurement period, then dividing by 120 hours per month. I once had a contractor who tracked this wrong and enrolled at what looked like seven employees but actually totaled 14 FTEs. That pushed him into a different rate tier and completely changed his premium calculation. Make sure you do this math correctly before you even log into the marketplace portal. After your FTE count is locked down, you pick a carrier and plan level. The affordable coverage threshold matters here. Under federal law, you have to contribute at least 60 percent of the premium for single coverage to qualify for the small business tax credit. Most brokers will build the quote showing that percentage by default, but double check it yourself. The paperwork sits in front of you and the numbers look fine on screen until you see the actual employee contribution on the enrollment form.
You also need to pick a renewal year and agree to the participation requirement. In most states, you have to enroll at least 70 percent of your eligible employees. If you have twelve eligible people, that means you need eight enrolled at renewal. I ran into a situation once where two key employees dropped out because their spouse offered them something cheaper through their own job. That left us at 66 percent and the marketplace portal would not let us renew until we either brought someone back on or dropped to a smaller plan tier. We solved it by moving one person from the high deductible plan to the basic tier plan, which counted toward the headcount even though the premium was lower. The tax credit is where things get confusing for owners. You can claim up to 50 percent of your premium contribution as a credit if you stay under 25 FTEs, pay average annual wages under a certain limit, and buy through SHOP. The wage cap changes every year. For 2024 it is roughly 75 thousand dollars in average wages. The credit phases out linearly as you go above five FTEs and above that wage threshold. A business with eight FTEs making 60 thousand average does not get the full credit. You have to run the IRS calculation yourself because the marketplace quote will not tell you the exact dollar amount you will save on your tax return. I use a simple spreadsheet that maps FTEs, average wages, and the credit phase out table from IRS publication 974.
The parts nobody warns you about
The biggest issue I see people hit is the difference between the quoted premium and the actual cost after state mandatory benefits are added. The base rate you see on the calculator often excludes certain required coverages depending on your state. California, for example, adds behavioral health parity requirements and specific maternity minimums that inflate the price compared to a quote from a neutral tool. The marketplace display will show the final number, but it happens late in the process. By then you are already stressed about the paperwork and likely to just accept it without questioning it. Another thing that catches people off guard is the timing. The open enrollment window for SHOP is not the same as the individual marketplace. Your state determines when you can enroll, change plans, or add new employees. Some states align it with the calendar year. Others use rolling enrollment with a ninety day wait for new hires. I learned this the hard way when a client hired someone in March and expected immediate coverage. The portal gave us an effective date of June first. We had to pay out of pocket for three months of claims on that employee, which was a painful surprise. Always check the state enrollment calendar before you make hiring decisions. You should also know that the marketplace is not always the cheapest option. I have found cases where a direct carrier quote for a fully insured plan came out ten to fifteen percent lower than the SHOP rate. This happens most often in states where the SHOP administration fees add a markup. If your business is under five FTEs or your employees have very specific coverage needs, you might be better off going direct. The tax credit only applies through SHOP though, so run both numbers before you commit.
Get the Full Details

What I wish I knew before the first enrollment
The enrollment itself is straightforward. You create an employer account, upload the employee demographics, select the plan tiers, and confirm each person's election. It takes about twenty minutes if your data is clean. If you have paper records or employees who never provided their information, it can take an afternoon. I keep a standard template that asks employees for their name, date of birth, social security number, and whether they have other qualifying coverage. Having this upfront cuts the enrollment time in half. You will also get a confirmation number and a summary of benefits document within a few days. Keep that confirmation number somewhere safe. I have had clients call me three months later because they lost it and needed to verify their enrollment status. The marketplace support line can find you by employer ID, but it takes longer and the hold time is usually forty-five minutes or more. If your business grows past fifty FTEs, the SHOP market resets. You move into the individual or large group market depending on your state. The transition is not automatic. You have to reapply and the rates will change. I had a small software company that hit fifty one FTEs in a single quarter because of seasonal contractors. Their premium jumped forty percent because they lost the SHOP rate structure. They ended up splitting the contractor work differently the next year to stay under the threshold, which is a legitimate strategy but requires actual operational planning.
The bottom line is that SHOP works well for most small businesses that want a simple group plan with some tax benefit. It is not perfect. The process has state variations, timing traps, and cost surprises. Do the FTE math first. Check the participation requirement against your headcount. Run the tax credit calculation yourself. And verify whether direct carrier quotes might beat the marketplace rate in your state before you finalize anything.