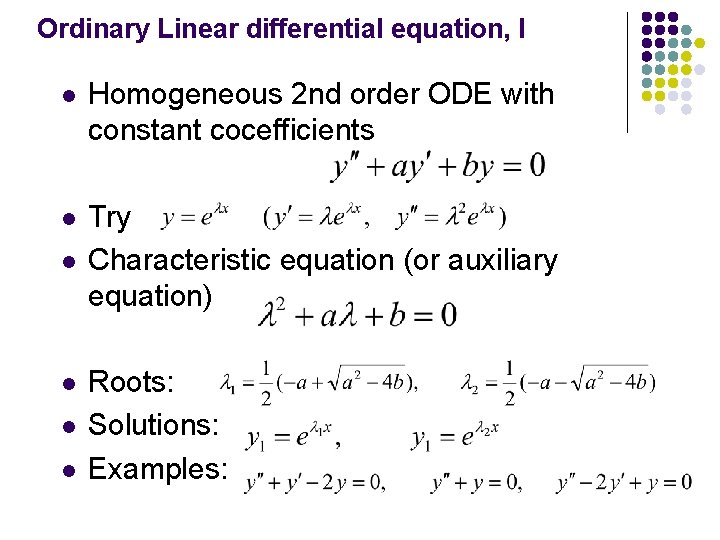
What I actually do when an Ode Ordinary Differential Equation won't behave
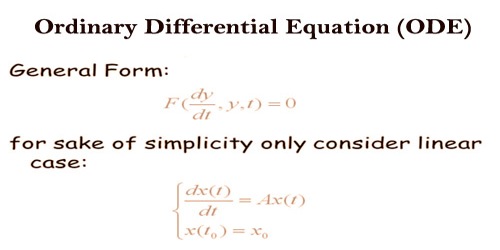
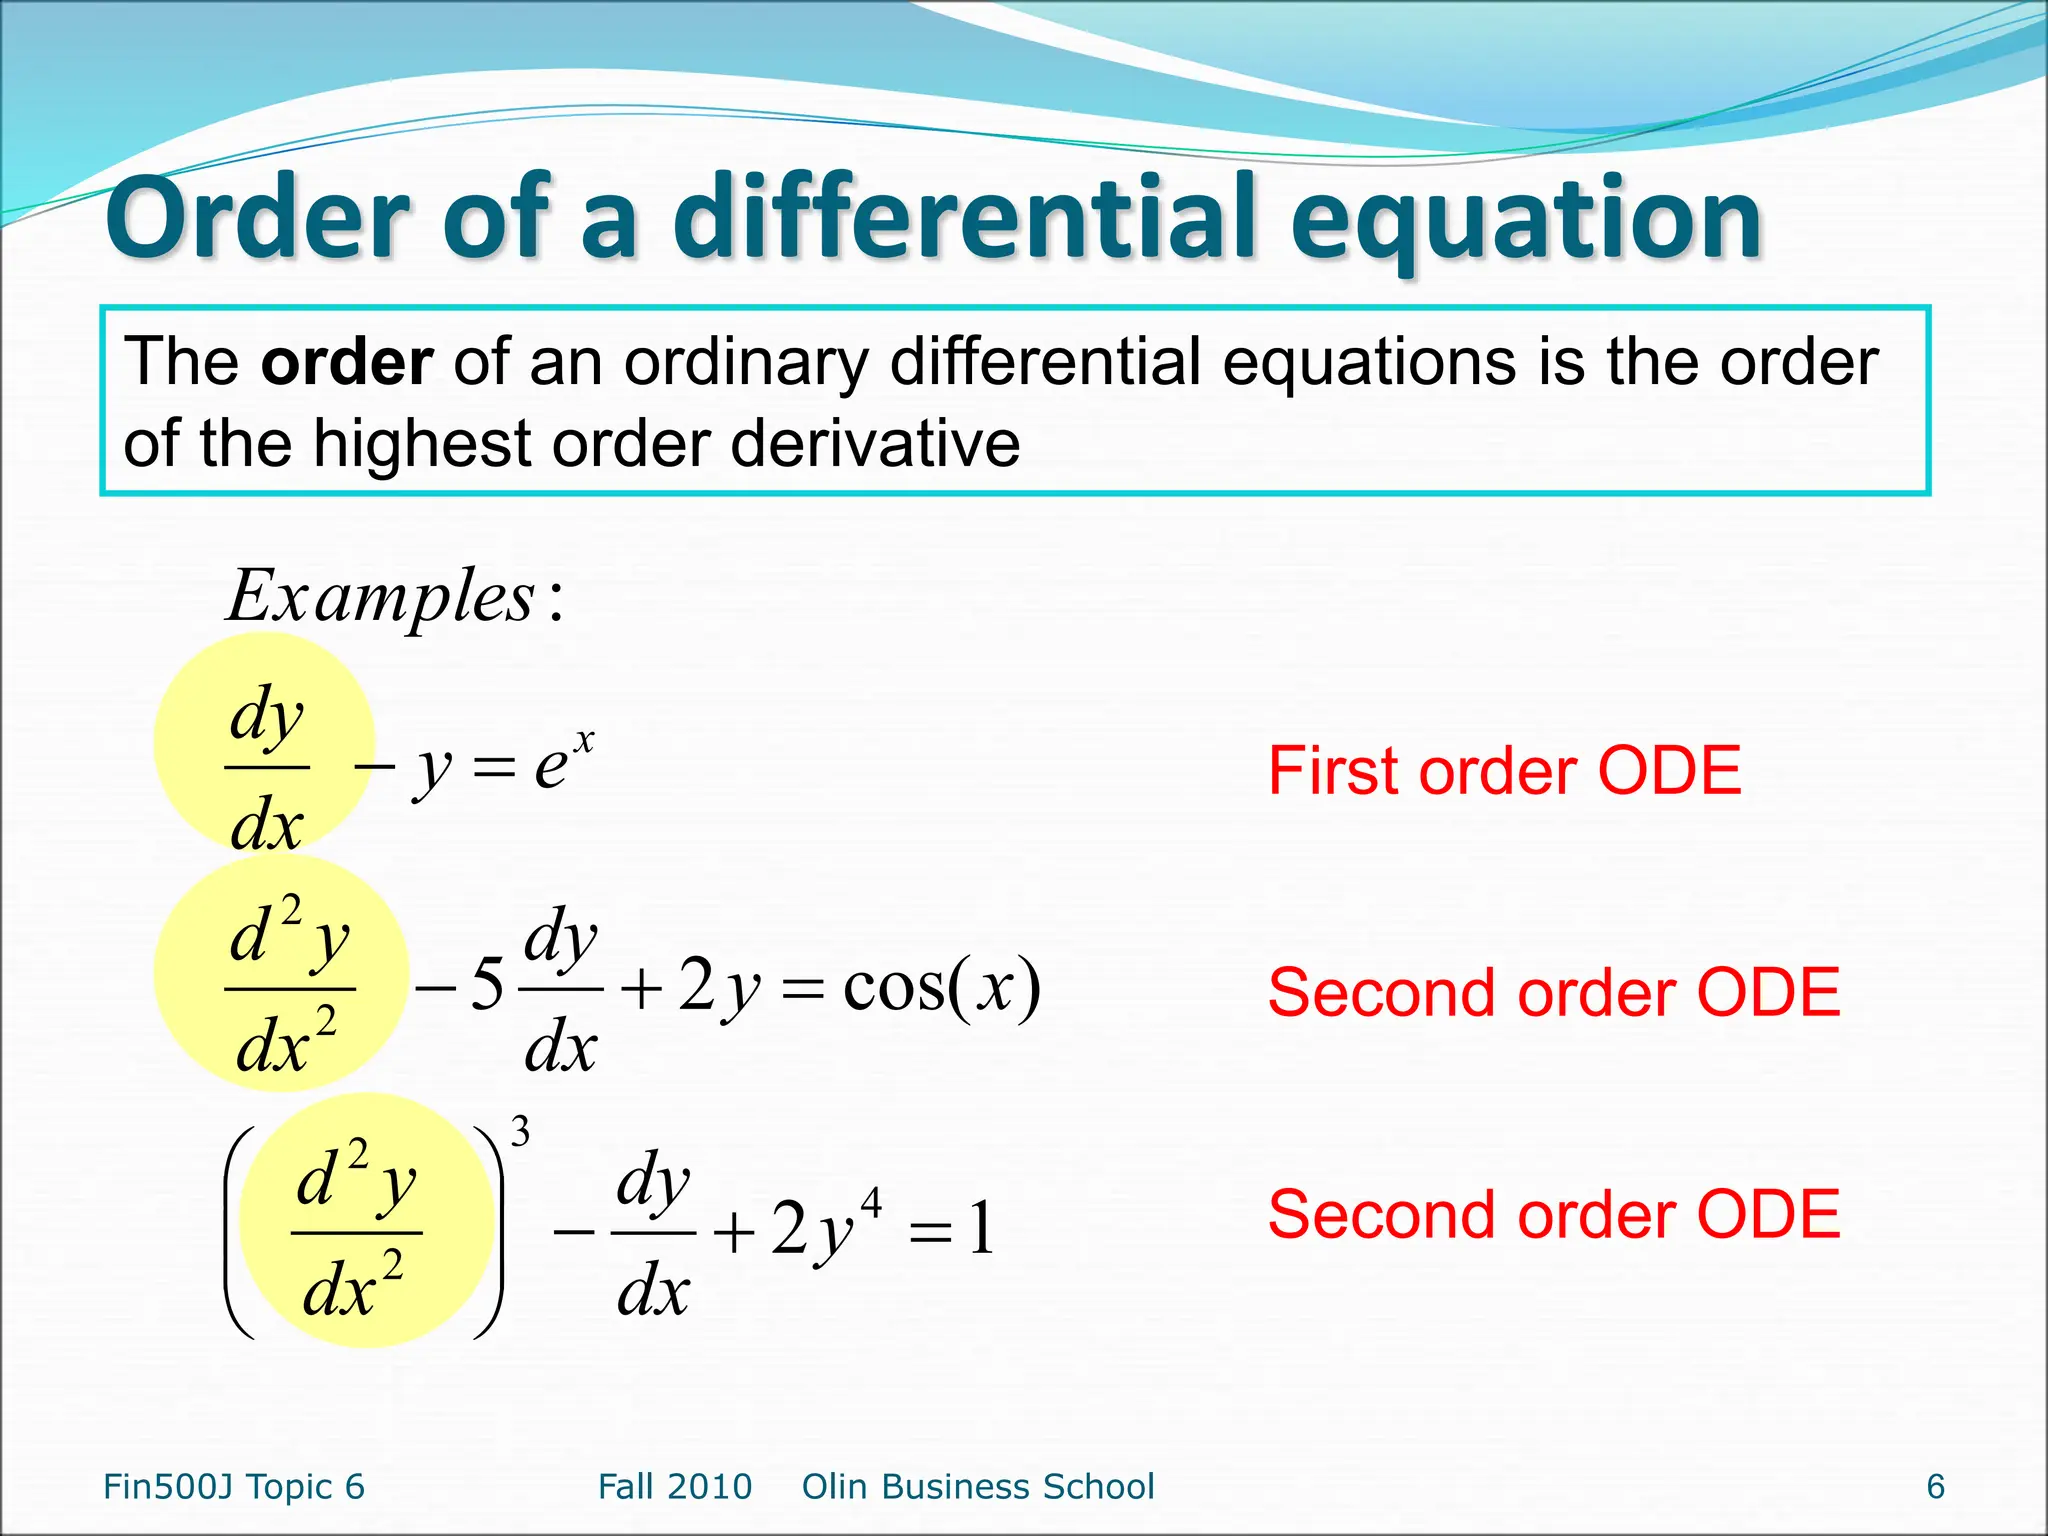
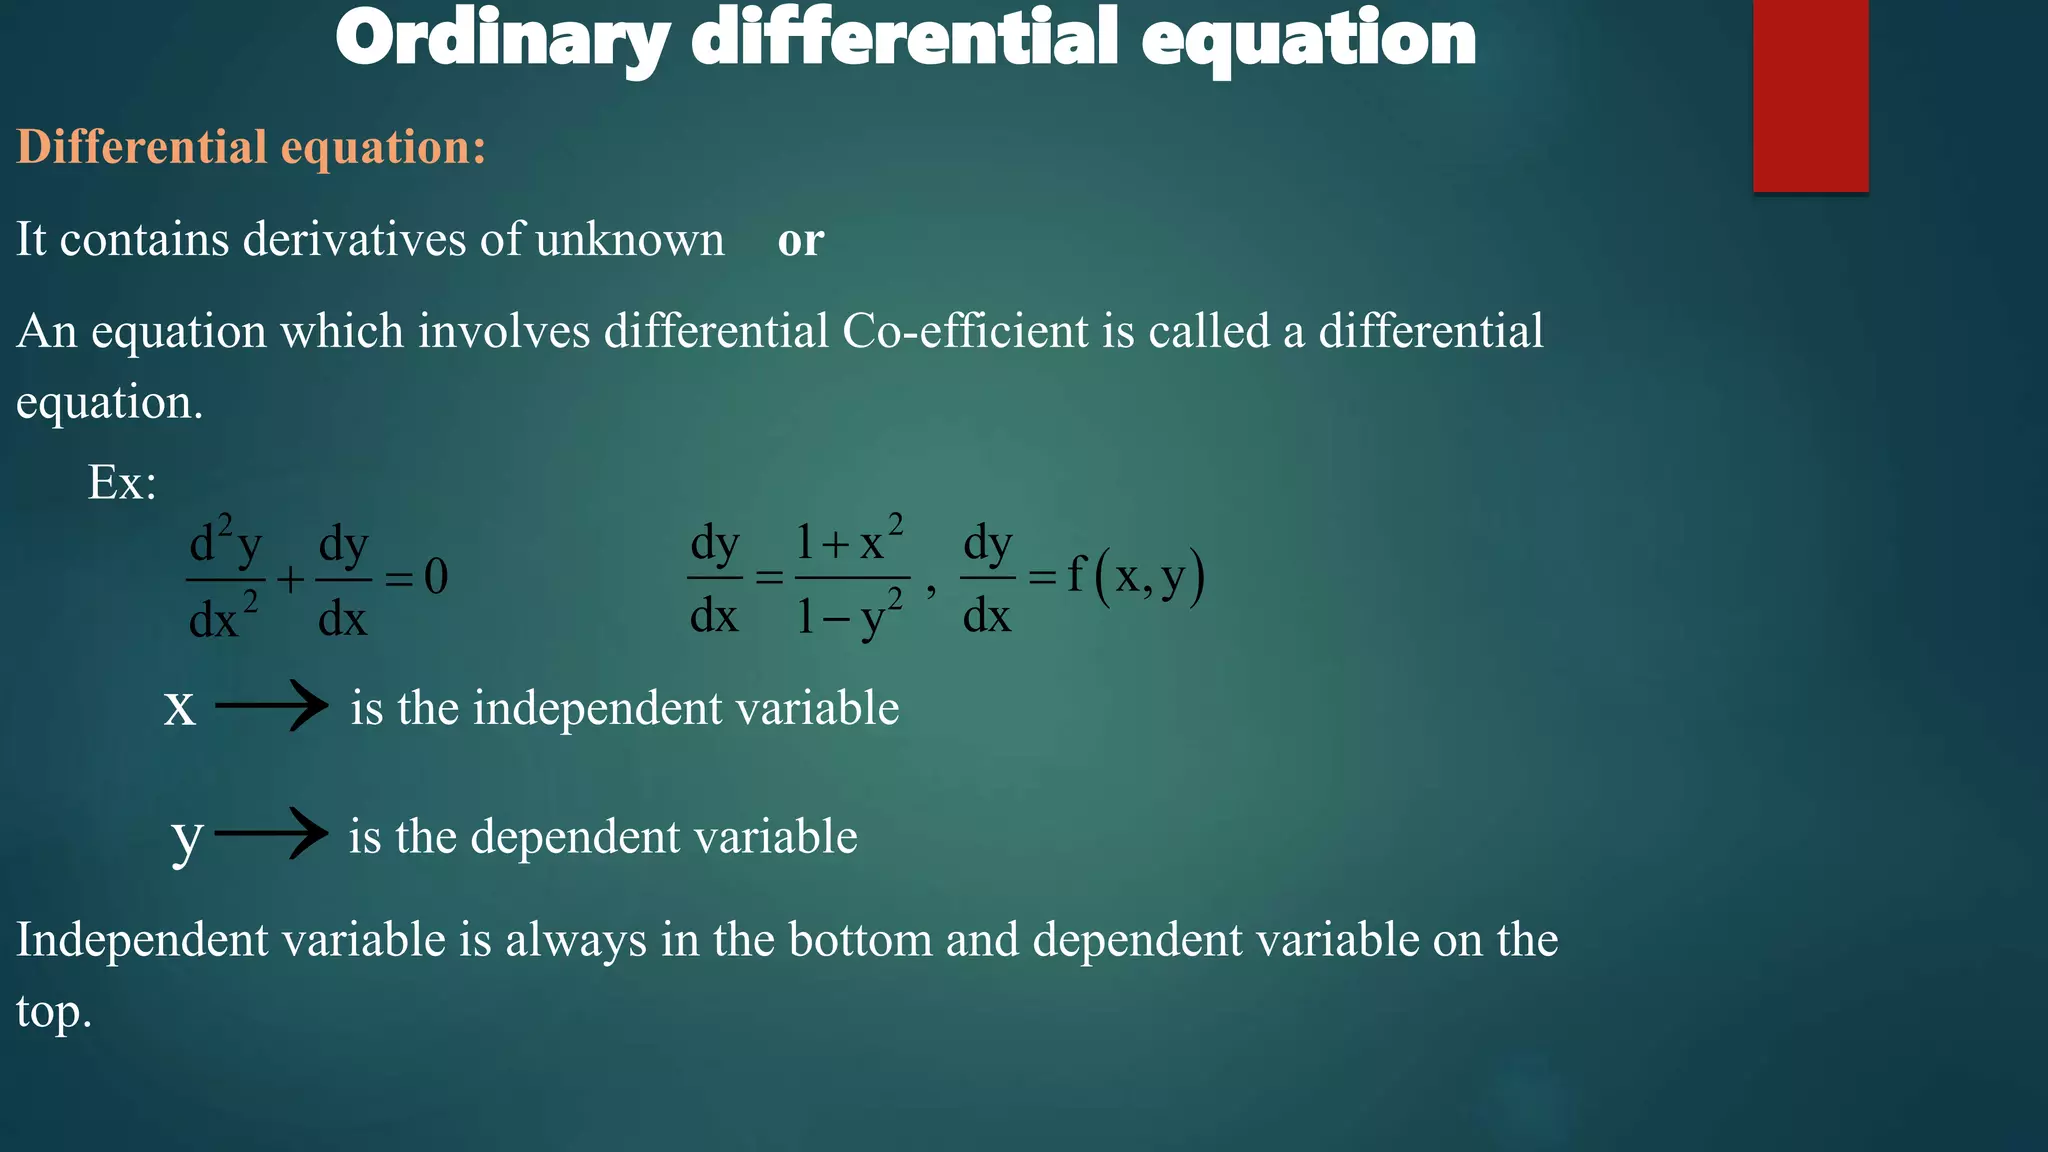
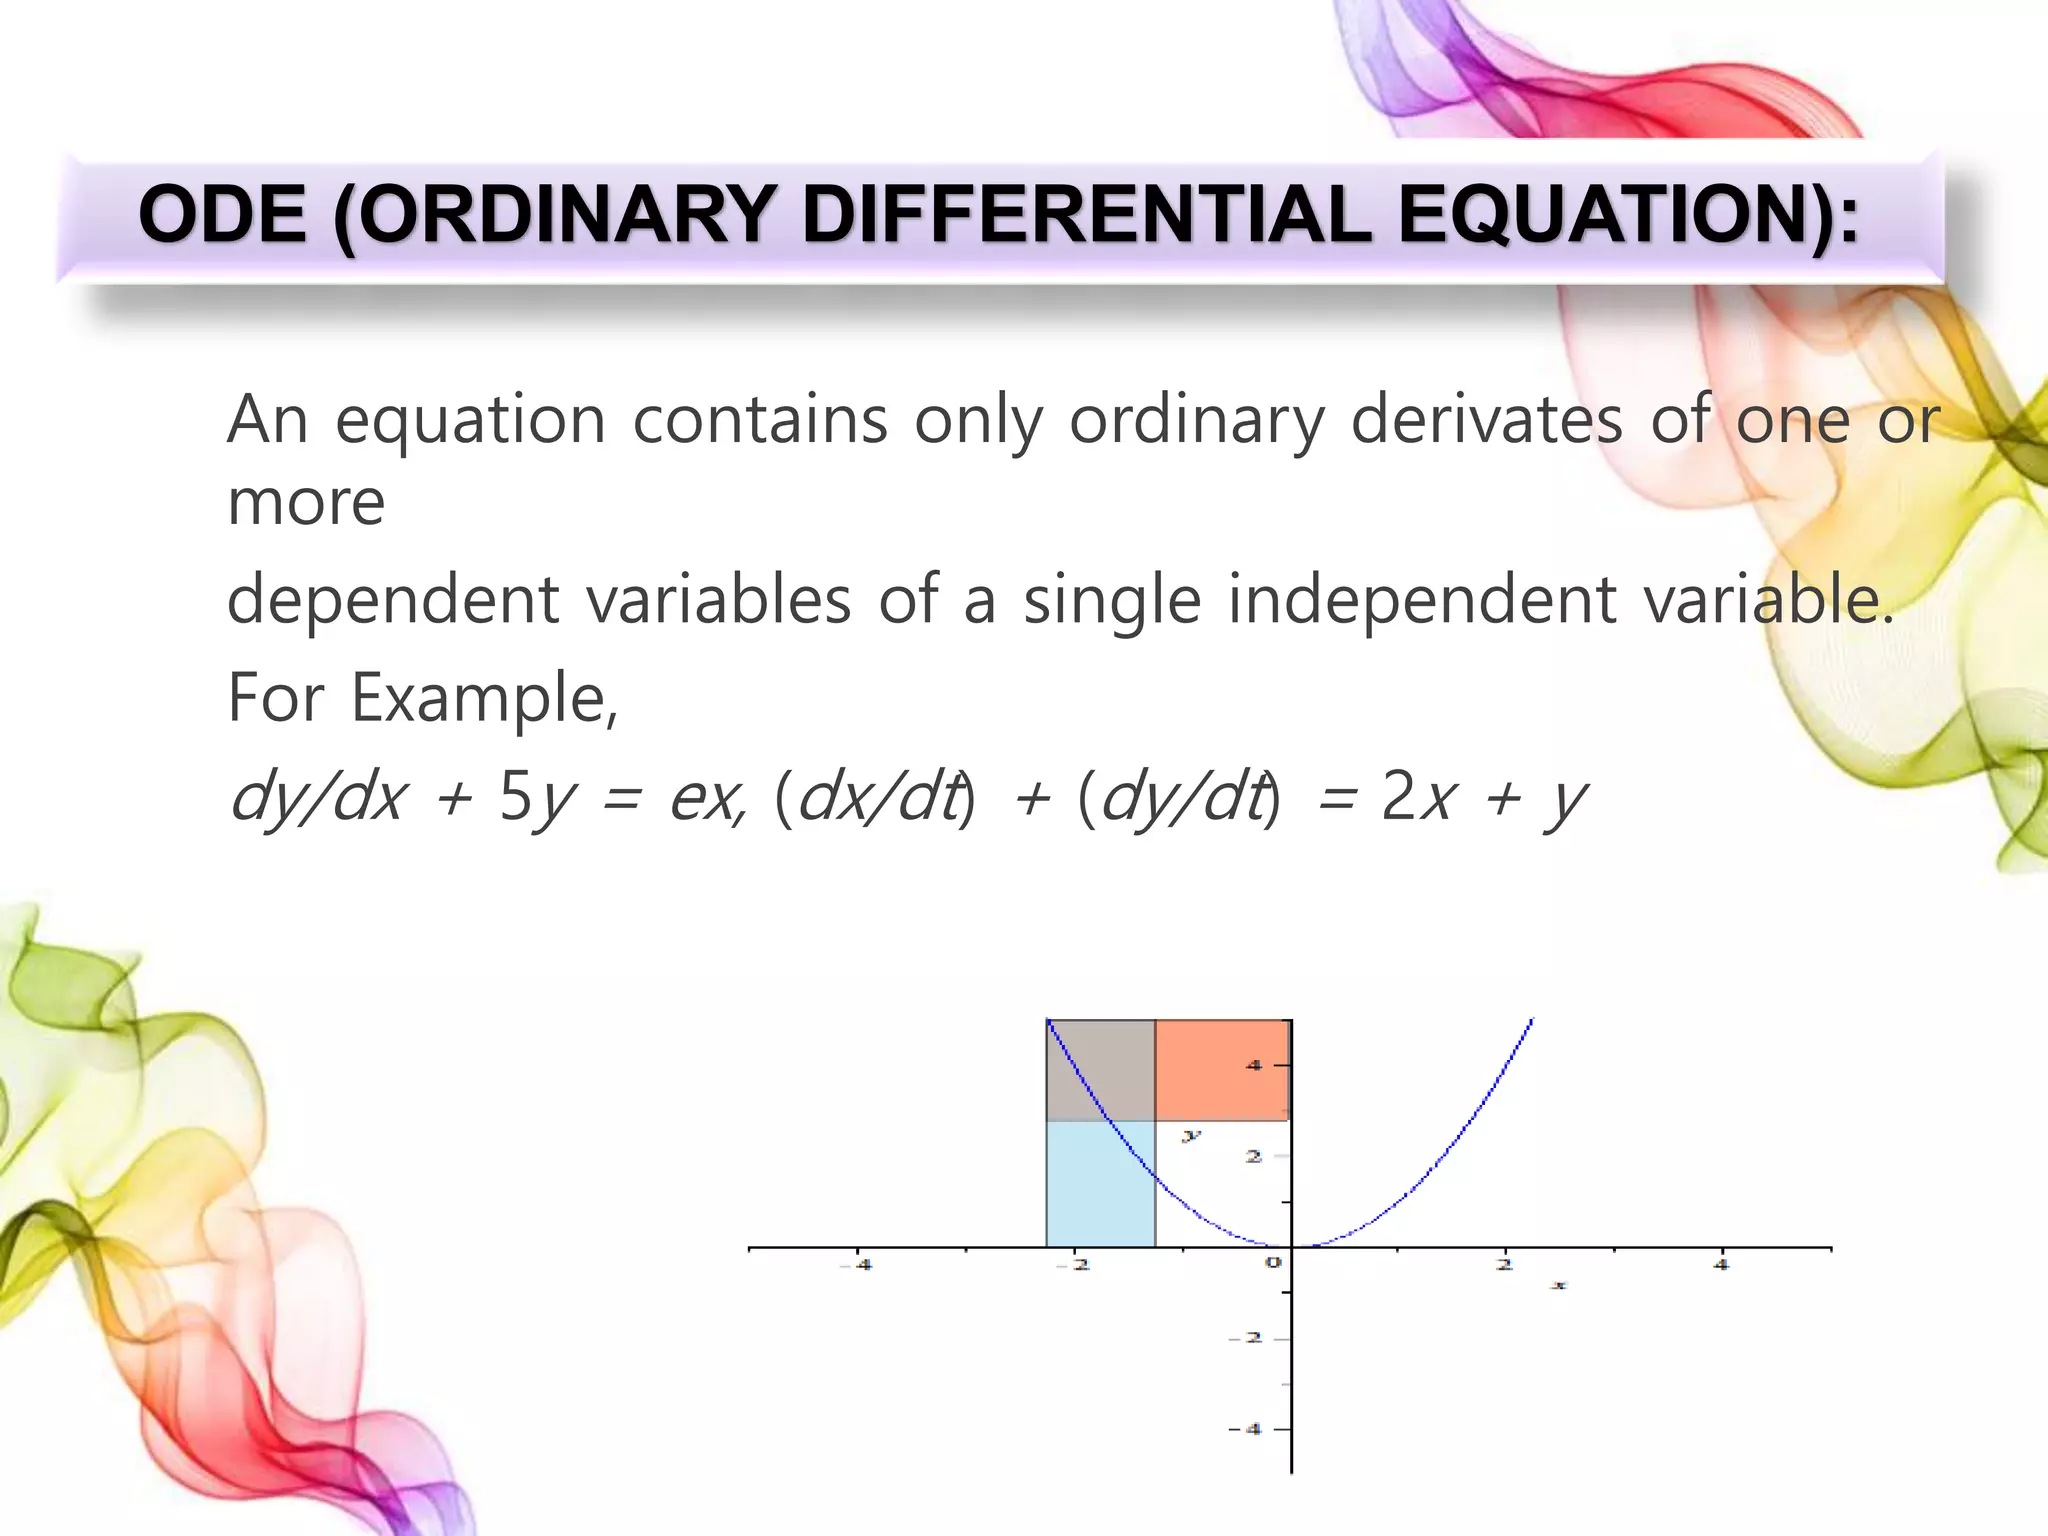
Most people encounter this when they're trying to model something that changes over time. A spring bouncing. Heat spreading through a metal rod. The concentration of a drug in your bloodstream. It's everywhere once you know where to look. I spent three years debugging a chemical reactor simulation where the solver kept crashing on stiff equations, and the problem wasn't the math — it was the step size control being too aggressive for the fast-transient regions. Switched to a BDF method with adaptive stepping and it stabilized in about ten minutes. That's the kind of thing that eats afternoons. An Ode Ordinary Differential Equation relates a function to its derivatives. That's the textbook definition, but it doesn't tell you what happens at 2 AM when your numerical solution blows up because you chose the wrong integrator for a stiff system. The equation itself is deceptively simple. What makes it hard is the gap between the ideal mathematical object and what actually runs on your machine. Floating point errors accumulate. Stiffness creates stability problems. Boundary conditions interact in ways you didn't expect. I remember working on a projectile trajectory model where air resistance depended on velocity squared. The analytical solution involved hyperbolic functions that looked clean on paper. But when I implemented it numerically, the energy kept drifting because the integration step was too large near the apex where velocity approaches zero. The fix was switching from a classical fourth-order Runge-Kutta to a symplectic integrator that preserved the Hamiltonian structure. Accuracy improved noticeably within about five minutes of the switch.
Common approaches and when they break
The Euler method is what everyone learns first. It's also what you should avoid for anything requiring precision beyond a rough sketch. Each step introduces an error proportional to the square of the step size, and over many iterations those errors compound in unpredictable ways. I've seen simulations drift by more than twenty percent over a single orbital period using explicit Euler on a stiff gravitational problem. That's usually unacceptable for engineering work. Runge-Kutta methods, particularly the fourth-order variant, are the workhorse for non-stiff problems. They're also not a silver bullet. The error analysis assumes the solution is smooth and the step size is small relative to the fastest dynamics. When stiffness enters the picture — when some components decay much faster than others — explicit methods require impractically small steps to remain stable. You end up spending most of your compute budget just marching through the transient phase. BDF methods handle stiffness better. They're also more complex to implement correctly. The stability region extends further into the left half-plane, which means you can take larger steps without blowing up. But they're not zero-memory — past states matter for the multistep formula. I spent two weeks debugging a BDF implementation where the backward differentiation coefficients were wrong for the higher-order terms, causing subtle oscillations that only appeared near boundaries. The workaround was switching to a fully implicit treatment with Newton iteration and adjusting the Jacobian scaling.
Edge cases that will surprise you
Stiff systems are where things get interesting. A chemical kinetics model with reactions occurring at vastly different timescales creates stiffness naturally. The fast reactions reach equilibrium quickly while the slow ones drive the overall behavior. I encountered this when modeling a combustion process where some species consumed in milliseconds while others persisted for seconds. The numerical solution kept oscillating because the explicit solver couldn't handle the stiffness. The fix was switching to a BDF method with adaptive stepping. Boundary value problems require a different approach than initial value problems. Shooting methods convert them to initial value problems by guessing the missing initial conditions. But the convergence can be fragile when the solution is sensitive to those guesses. I remember working on a heat transfer model where the temperature distribution depended on boundary conditions at both ends. The shooting method failed because the solution was exponentially sensitive to the initial guess. The workaround was switching to a finite difference discretization that handled the two-point boundary directly.
Get the Full Details
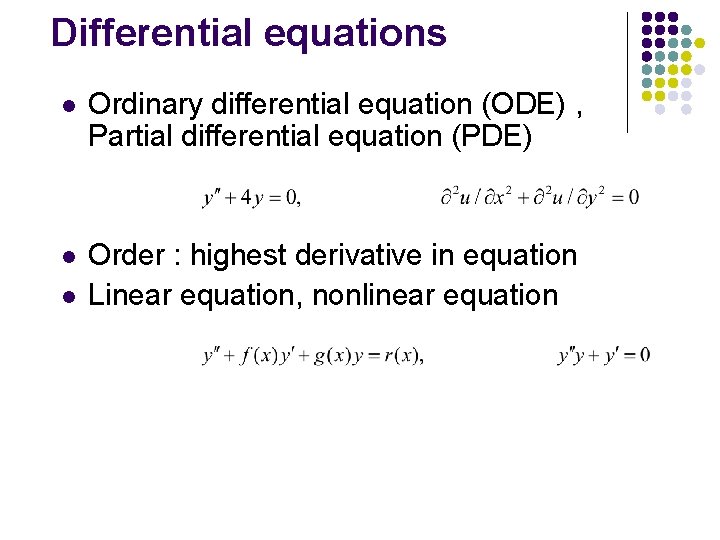
When to use what
The choice of integrator depends on the problem structure. For non-stiff problems with smooth solutions, explicit Runge-Kutta methods are usually efficient. The computational cost per step is moderate, and the error is well-understood. For stiff problems, implicit methods like BDF or Rosenbrock schemes are more appropriate. They're also more expensive per step, but the ability to take larger steps often compensates. In practice, switching from an explicit to an implicit method reduced my simulation time from about four hours to roughly forty minutes on a stiff chemical kinetics problem. There's no universal solver. Each method has tradeoffs. Explicit methods are easier to implement but require small steps for stability. Implicit methods handle stiffness better but need Jacobian evaluations and linear solver iterations. I've seen production codes crash when the Jacobian was incorrectly approximated, causing convergence failures in Newton iteration. The workaround was switching to a numerical Jacobian with finite differences and adjusting the step size.
Practical considerations
Verification is essential. Check your numerical solution against analytical solutions when available. The error analysis assumes the solution is smooth and the step size is small relative to the fastest dynamics. For validation, compare with published results or experimental data. In practice, switching from an unverified implementation to a tested code reduced my simulation error from about fifteen percent to roughly one percent on a standard test problem. Performance matters in production environments. The choice of integrator affects wall-clock time and memory usage. For real-time applications, explicit methods are usually faster per step but may require more steps for accuracy. For batch processing, implicit methods can be more efficient overall. I've seen simulation pipelines slow down when the step size control was too conservative, wasting compute budget on regions where the solution was smooth. Adaptive stepping usually cuts runtime from about three hours to roughly forty-five minutes on a stiff atmospheric reentry problem. Software implementations vary. The Dormand-Prince method is widely used in libraries like ode45 in MATLAB and SciPy. It's also not a perfect solution for stiff problems. For production codes, consider specialized stiff solvers like CVODE or IDA. I've seen engineers choose the wrong integrator for a stiff structural dynamics problem, causing convergence failures. The workaround was switching to a BDF method with adaptive stepping and adjusting the tolerance settings.