What a Financial Responsibility Template Actually Is
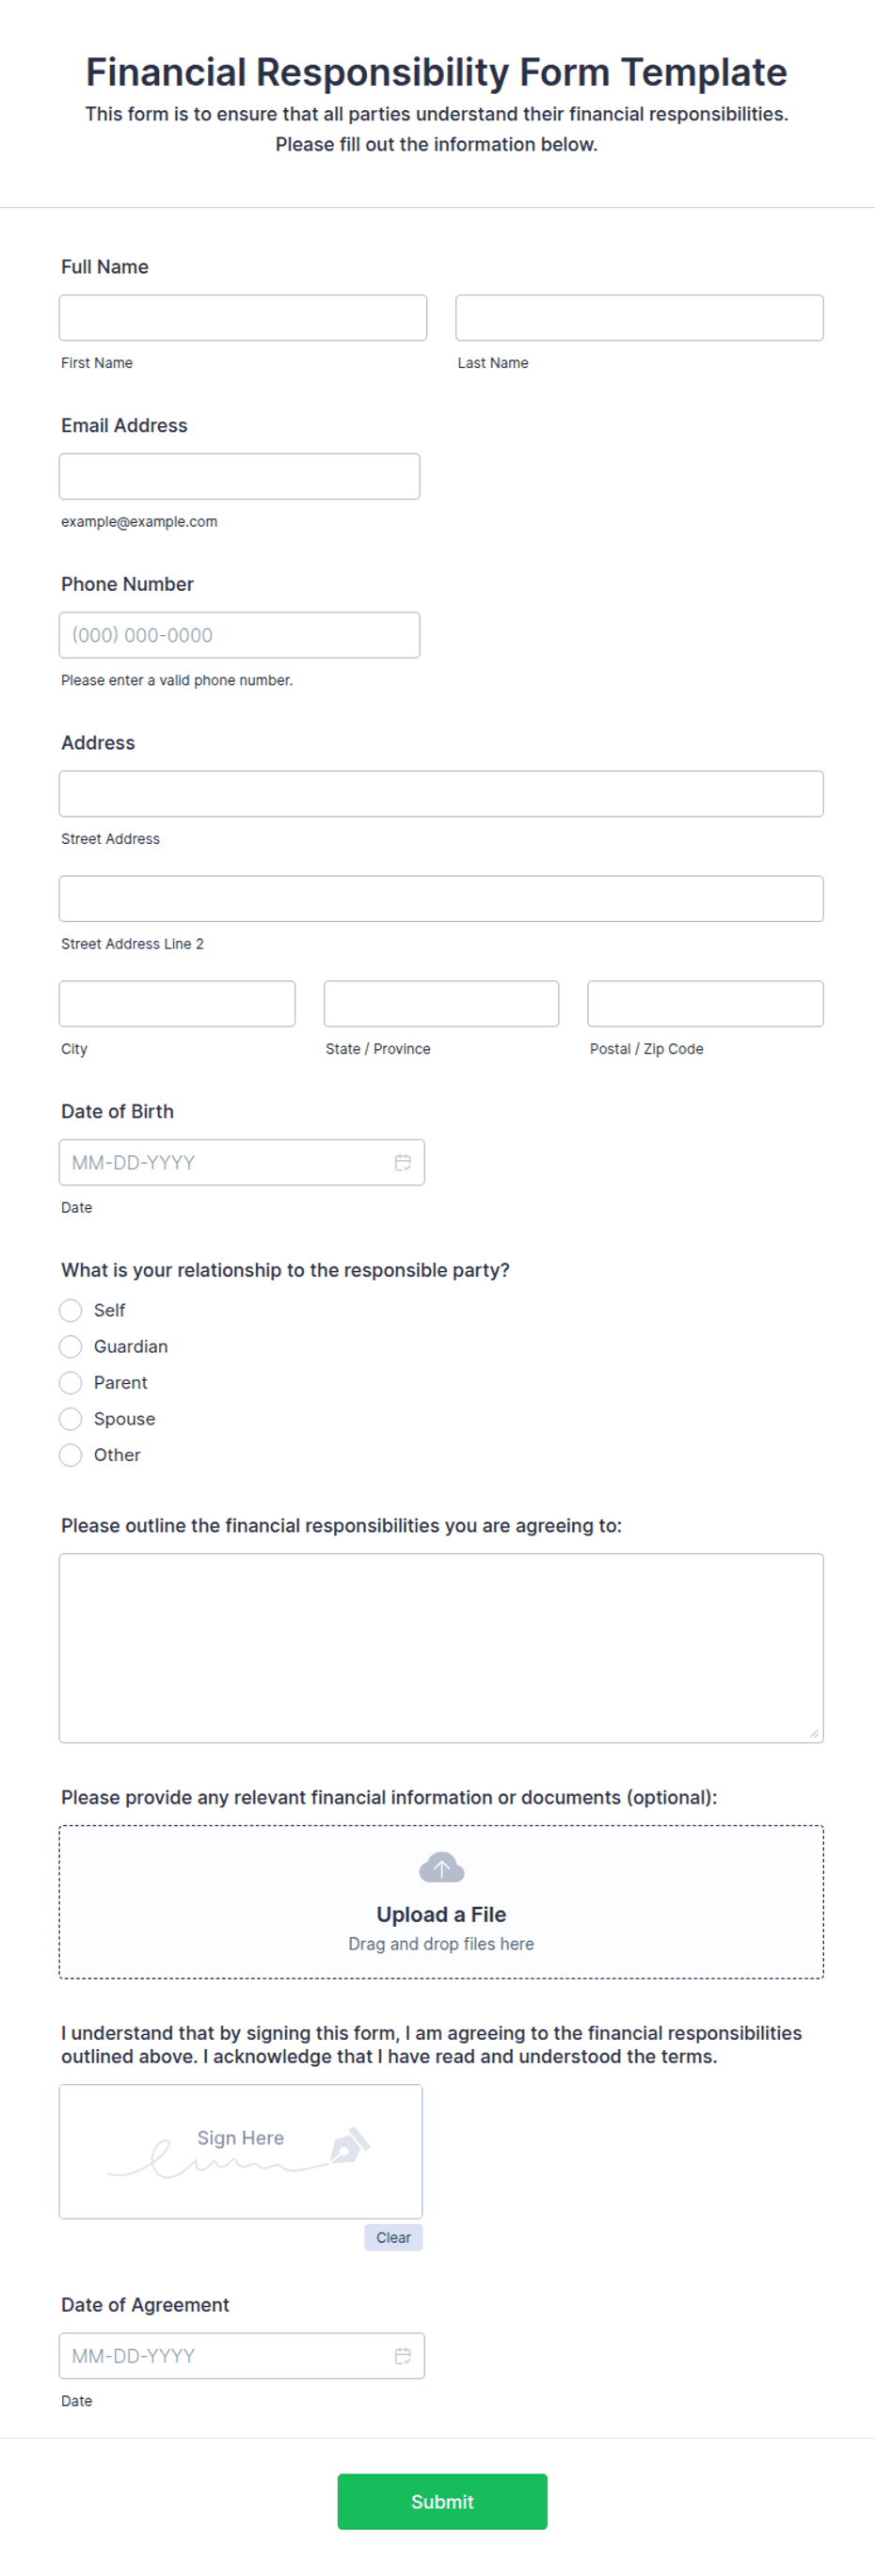
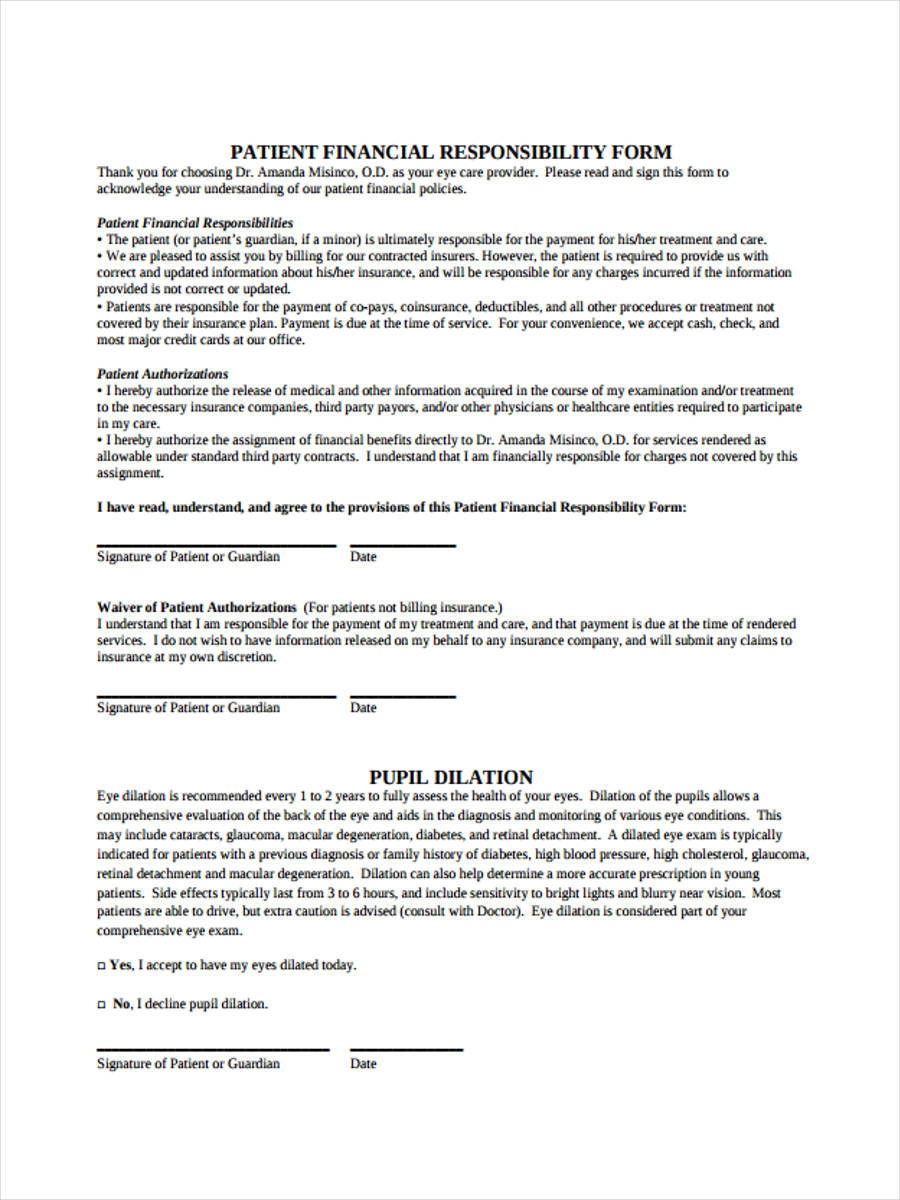
An Of Financial Responsibility Template is a standardized form used by institutions to document that a person or entity accepts liability for a debt or obligation. You will see them in university billing offices, medical practices, corporate expense departments, and sometimes with government contractors. The form itself is usually simple—a signature block, a statement of understanding, and space for the amount owed. The structure varies depending on who requires it. I have spent years dealing with these forms across multiple organizations. They look easy. They are not always easy. The real difficulty comes from the inconsistency between institutions. One university uses a single-page PDF. Another requires a separate form for each type of charge—tuition, housing, library fines. If you are managing obligations for more than one entity, you will quickly understand why people maintain their own records rather than trusting any single template.
Getting Started With Of Financial Responsibility Template
The first step is identifying which version you need. Templates are not interchangeable between organizations. A form issued by a hospital will not satisfy a university bursar, and a corporate expense template means nothing to a municipal court. Before you fill anything out, confirm the source. Ask for the exact document from the office handling your case. Do not rely on a form you found on someone else's website or from a previous interaction. Institutions update these periodically, and using an outdated version will cost you time. Once you have the correct template, review every field before writing. Common sections include your full legal name, date of birth or employee ID, the account or invoice number, the dollar amount, and a checkbox confirming you understand the repayment terms. Some templates also require you to select a payment plan type—full balance due at once, monthly installments, or deferred payment with interest. Read the fine print on those interest clauses. I have seen people sign for zero-interest plans that auto-convert to 18% APR after 60 days if the minimum payment is missed once. The language is usually buried in the third paragraph.
How It Works in Practice
After you complete the template, the workflow depends entirely on the receiving organization. Most universities and hospitals accept digital submissions through a portal, which routes the form to their accounts receivable team. They verify the information, flag the account, and send you a confirmation email. This process typically takes two to five business days. Smaller organizations or court systems sometimes require physical signatures and mailed copies, which adds a week or more. The part most people skip is the record-keeping step. Keep a dated copy of the completed form for yourself. Save the confirmation email. If you paid by credit card or bank transfer, retain the transaction receipt. I learned this after my student account from 2017 resurfaced three years later during a loan application review. The school claimed I never signed the financial responsibility form for a $2,400 lab fee. I had the scan in my cloud storage with the original submission timestamp. The issue resolved in two days because I had the paperwork. If you do not have it, you are starting from scratch, and the institution has no incentive to dig through their archives for you.
Get the Full Details
Common Mistakes That Cause Problems
The biggest error people make is signing without verifying the account number. A single digit off in the reference field can attach your signature to someone else's debt. I encountered this when a former colleague signed a financial responsibility form for a class schedule change, and the department entered the wrong student ID. The form got linked to a different person's account, and that person received collection notices for six months. It took four emails and a notarized statement to untangle. Another mistake is ignoring the due date on the form itself. The template usually includes a deadline for either full payment or the first installment. Missing this deadline does not erase the obligation. It typically triggers late fees and sometimes interest accrual from the original invoice date, not the new deadline. One medical clinic I dealt with applied a 2% late penalty within 30 days of the form deadline. On a $5,000 balance, that is $100 gone for missing a date you could have set as a calendar reminder. A third pitfall is assuming the template replaces a payment. Signing a financial responsibility form acknowledges debt. It does not pay it. The balance remains active until you submit actual funds or a formal payment arrangement that the billing department confirms in writing. People sometimes sign the form, think the issue is handled, and then wonder why their account is still delinquent. The form and the payment are two separate steps.
When the Template Approach Breaks Down
Financial responsibility templates assume a straightforward situation: one debtor, one creditor, one clear amount. Real life is messier. Joint accounts, disputed charges, partial payments already made, and third-party insurance claims all complicate the standard form. When these factors exist, the template becomes inadequate. I ran into this recently when a client needed to sign a financial responsibility agreement for a medical bill that was partially covered by insurance and partially disputable. The template had no section for insurance adjustment notes or dispute codes. I attached a separate spreadsheet documenting the insurance EOB number, the disputed line items, and the expected adjustment. The billing office accepted it, but I had to follow up three times because the automated system did not recognize the attachment. For complex cases, a standard template is the wrong tool. You need a customized acknowledgment letter or a formal payment agreement that addresses each variable. Some organizations provide an alternative—look for a "payment plan agreement" or "disputed charge form" instead of the basic financial responsibility template. If your institution only offers the standard form and your situation does not fit, escalate to a supervisor or the billing department's dispute resolution team. They can issue a modified document.
Advanced Nuances Most People Miss
One detail that catches people off guard is the revocation clause. Many financial responsibility templates include language allowing the institution to modify the terms or report the debt to a credit bureau if you fail to comply with the payment schedule. This clause is often written in plain text but carries real consequences. A single missed payment can trigger a credit report filing, and some institutions do this automatically without a warning. Check whether your state or country has consumer protection laws that require a 30-day notice period before reporting. In some jurisdictions, automatic reporting without notice violates local regulations, which gives you leverage if the institution pressures you. Another counter-intuitive point is that signing a financial responsibility template can sometimes restart the statute of limitations on a debt. In certain legal frameworks, acknowledging a debt in writing resets the clock that limits how long a creditor has to sue you for nonpayment. If you are dealing with an older debt that the collector is struggling to prove, signing the template may give them a fresh window to pursue legal action. This is not universal law, but it is common enough in consumer debt collections that you should verify the statute of limitations in your jurisdiction before signing anything on an aged account.
Practical Workflow Summary
Identify the correct template from the issuing authority. Verify the form version is current. Fill in all fields carefully, double-checking account numbers and amounts. Read the interest and default clauses before signing. Submit through the proper channel and retain proof of submission. Keep your copy organized with the confirmation and any related correspondence. If your situation involves disputes, joint liability, or insurance adjustments, supplement the template with additional documentation rather than forcing it to fit. This process usually takes 20 to 40 minutes for a straightforward case. More complicated situations with disputed charges or multiple parties can extend that to two or three hours, including follow-up communication. Time spent getting the documentation right the first time consistently saves more time than correcting mistakes afterward.