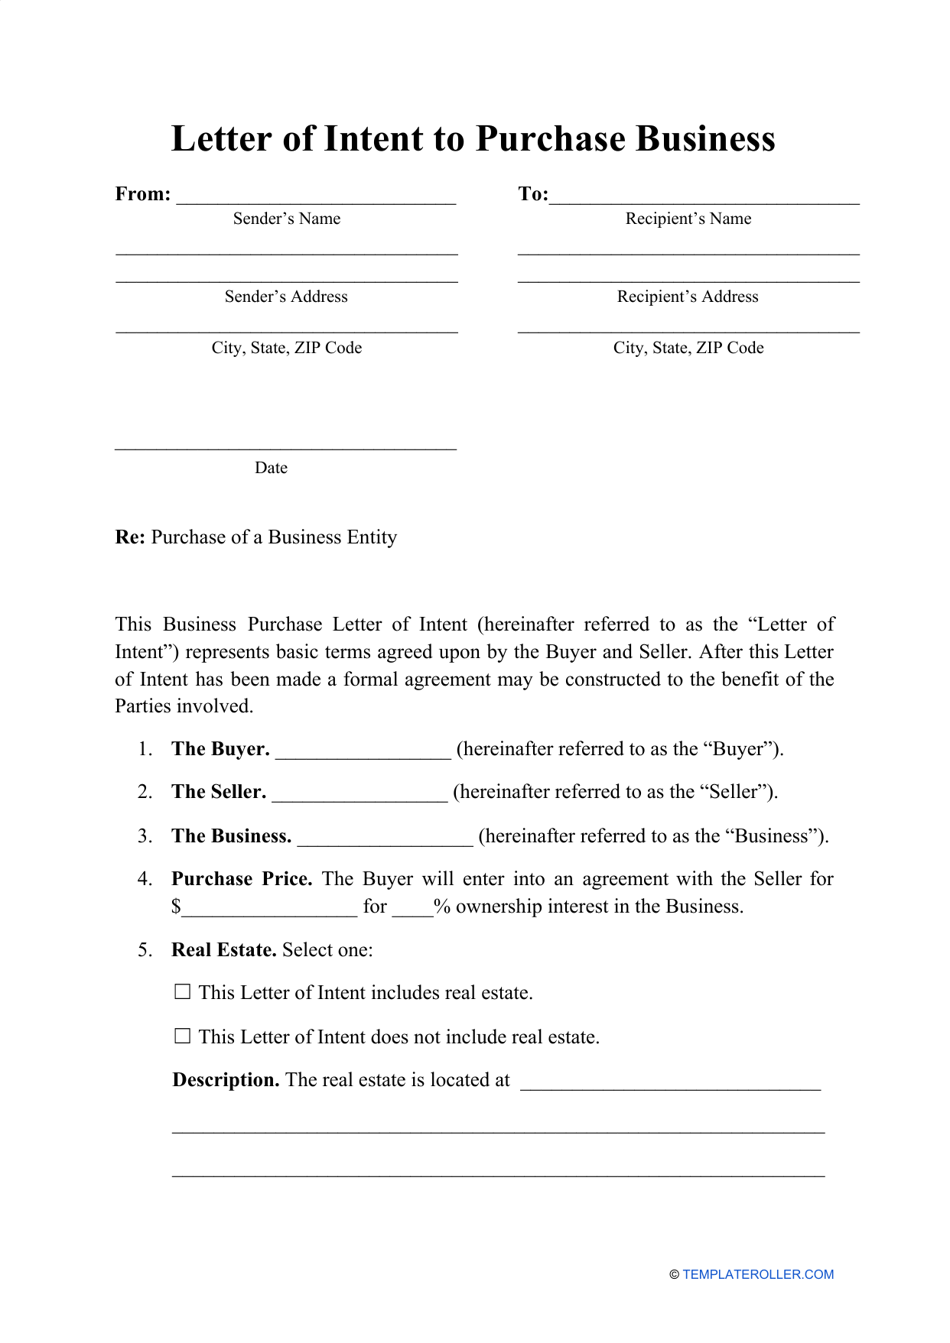
What an Of Intent To Purchase Business Template Actually Looks Like in Practice
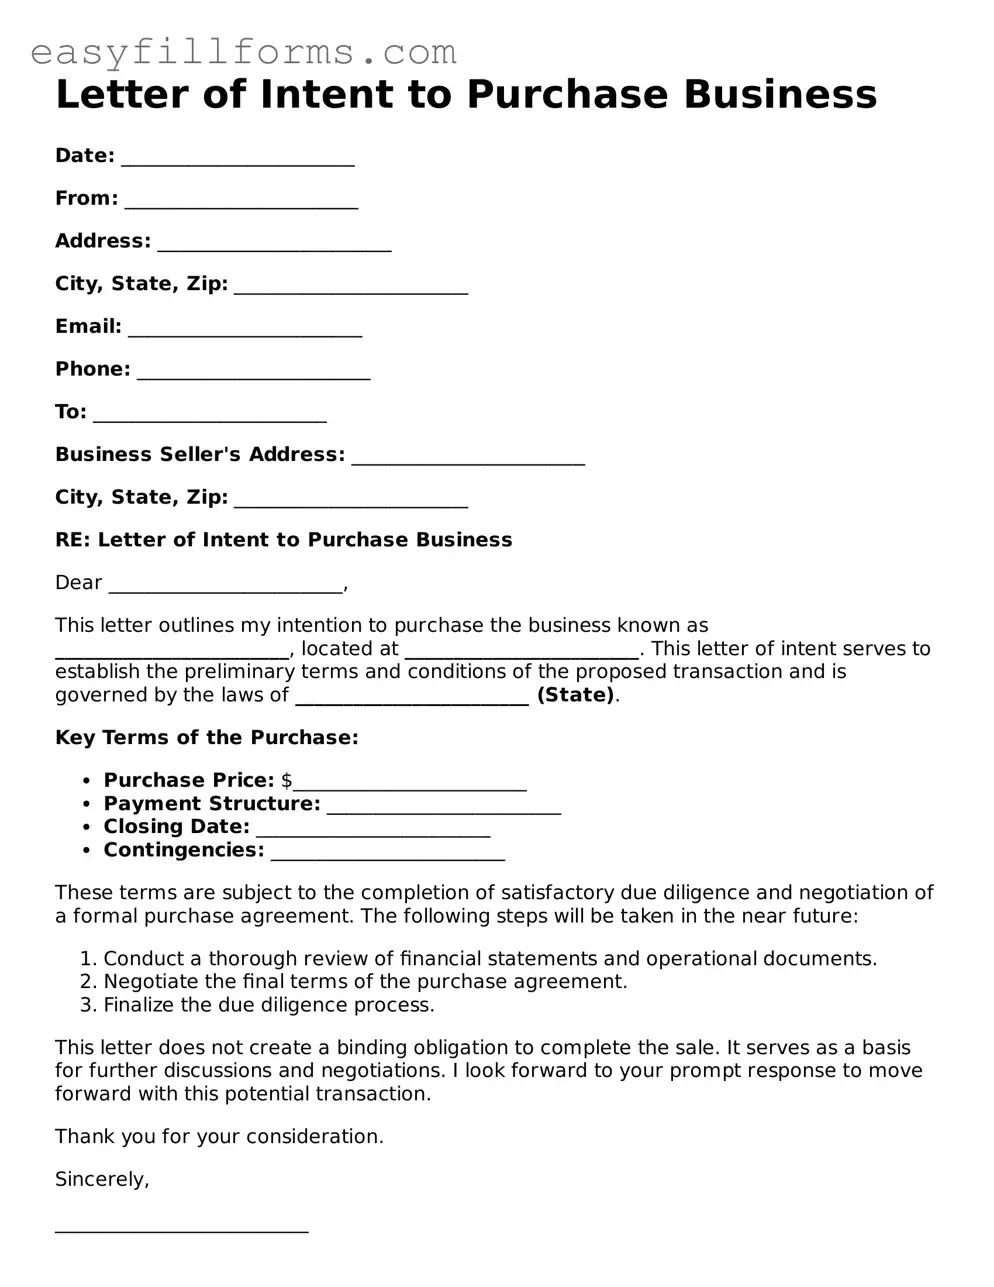
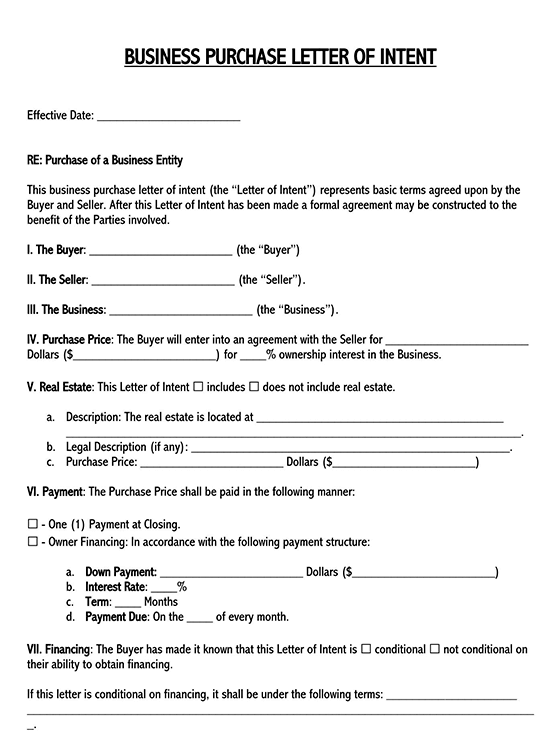
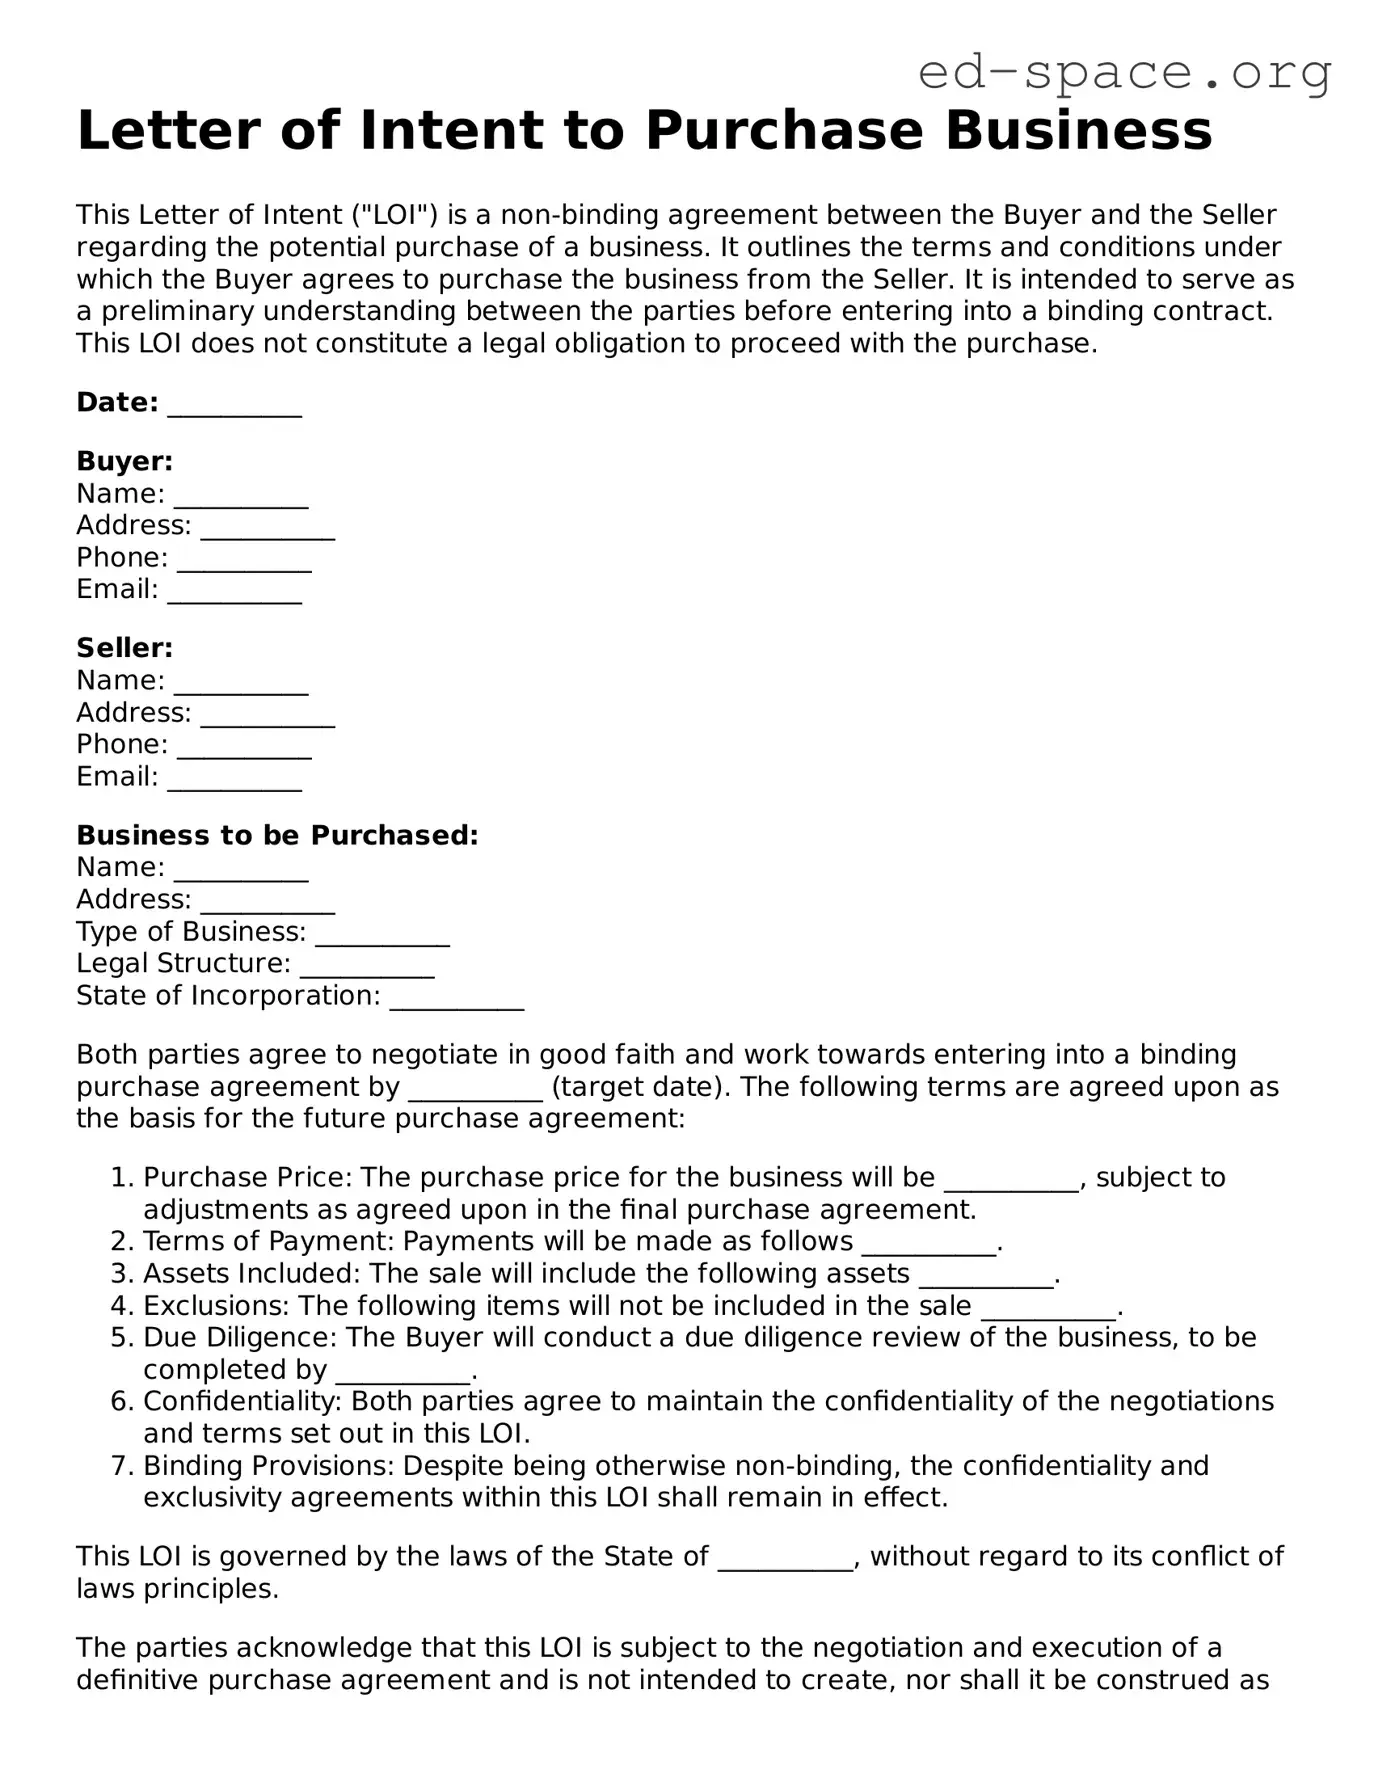
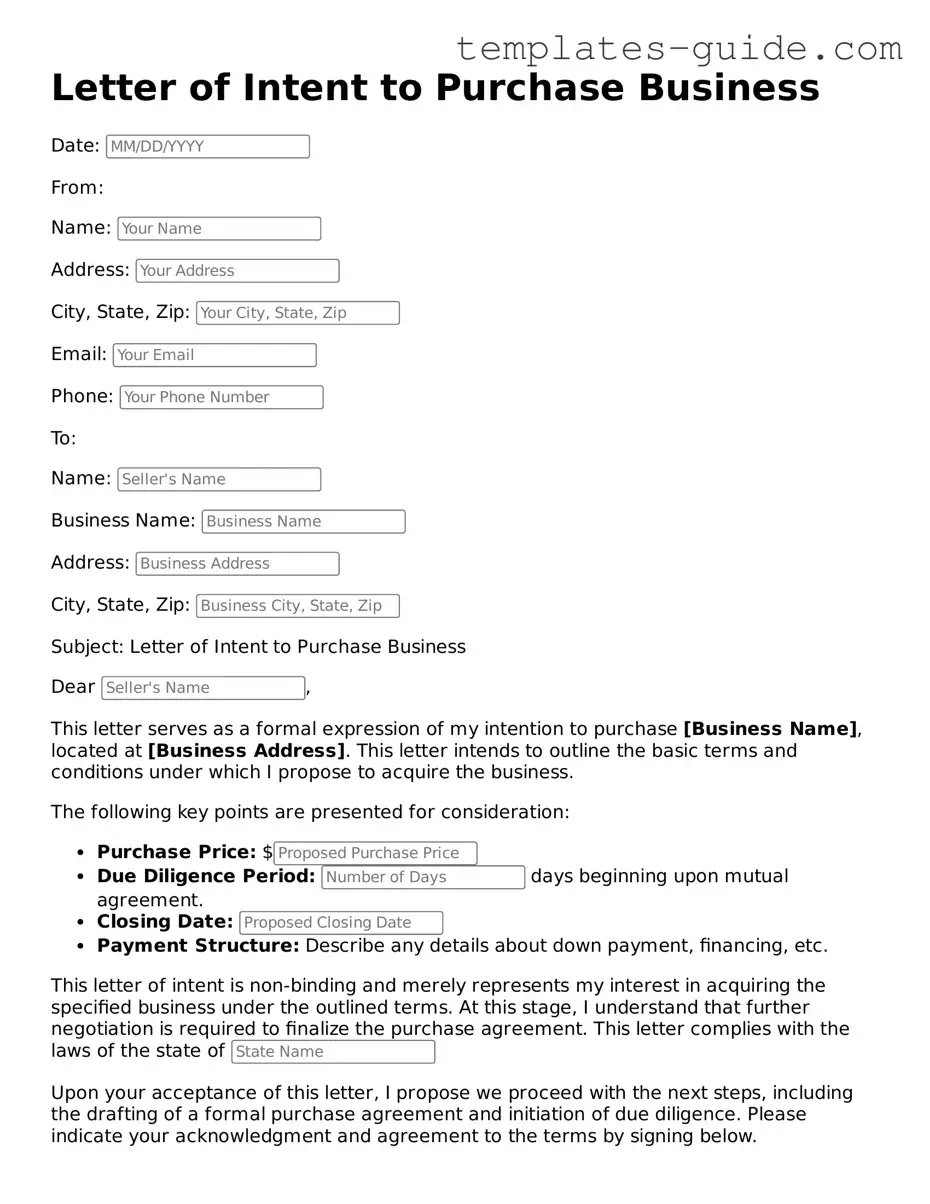
An Of Intent To Purchase Business Template is a prestructured document used when a buyer wants to formally express their intention to buy a business. It sits somewhere between a handshake agreement and a binding contract, usually drafted during early-stage negotiations. The template lays out the basic terms, identifies the parties involved, and signals to the seller that the buyer is serious enough to move forward. I have dealt with these documents on both sides of the transaction for years. On the buyer side, you use it to lock in key terms before spending money on due diligence. On the seller side, it gives you a way to screen out tire-kickers without handing over confidential financials to someone who might never close.
Where to Get a Reliable Of Intent To Purchase Business Template
The template itself is not proprietary. You will find free versions scattered across legal forms websites, small business forums, and attorney blogs. Most of them are functional but shallow. A decent one covers the purchase price structure, timeline, exclusivity period, and confidentiality provisions. That is the minimum baseline. Anything less and you are just writing a letter that has no real teeth. If you want something tighter, the better route is a paid template from a business transaction attorney or a service like Docracy or LawDepot. The cost runs anywhere from twenty to a hundred dollars depending on how detailed you need it. For most small business purchases under two million dollars, that investment is worth it because the alternative is rewriting something flawed from scratch, which takes hours and still leaves gaps you will not notice until the deal falls apart.
How to Fill One Out Without Breaking It
Start with the identification section. Full legal names of both parties, entity types if applicable, and addresses. I see this skipped or done sloppily so often that it is almost impressive. One time, a buyer listed the wrong DBA name on the template, and the seller spent three weeks trying to figure out which entity was actually signing. We eventually tracked it down to a minor clerical mismatch, but the whole thing could have been avoided in thirty seconds. Next, the purchase price and structure. Is it a stock sale or an asset sale? What portion is cash at closing, what portion is seller financing, and is there an escrow holdback? Put the numbers down clearly. Vague language like "reasonable purchase price" or "terms to be negotiated later" defeats the entire purpose of the document. You should not be using this template to park a vague idea. Use it to lock in concrete terms. Then the exclusivity clause, also called a no-shop provision. This is where the seller agrees not to entertain other offers for a set period while you run due diligence. The standard window is thirty to sixty days. I once worked a deal where the buyer pushed for ninety days of exclusivity with no renewal option and no fee for the extra time. The seller saw right through it and walked. The buyer had essentially tried to tie up the deal without putting real skin in the game. It happened more than once.
Get the Full Details
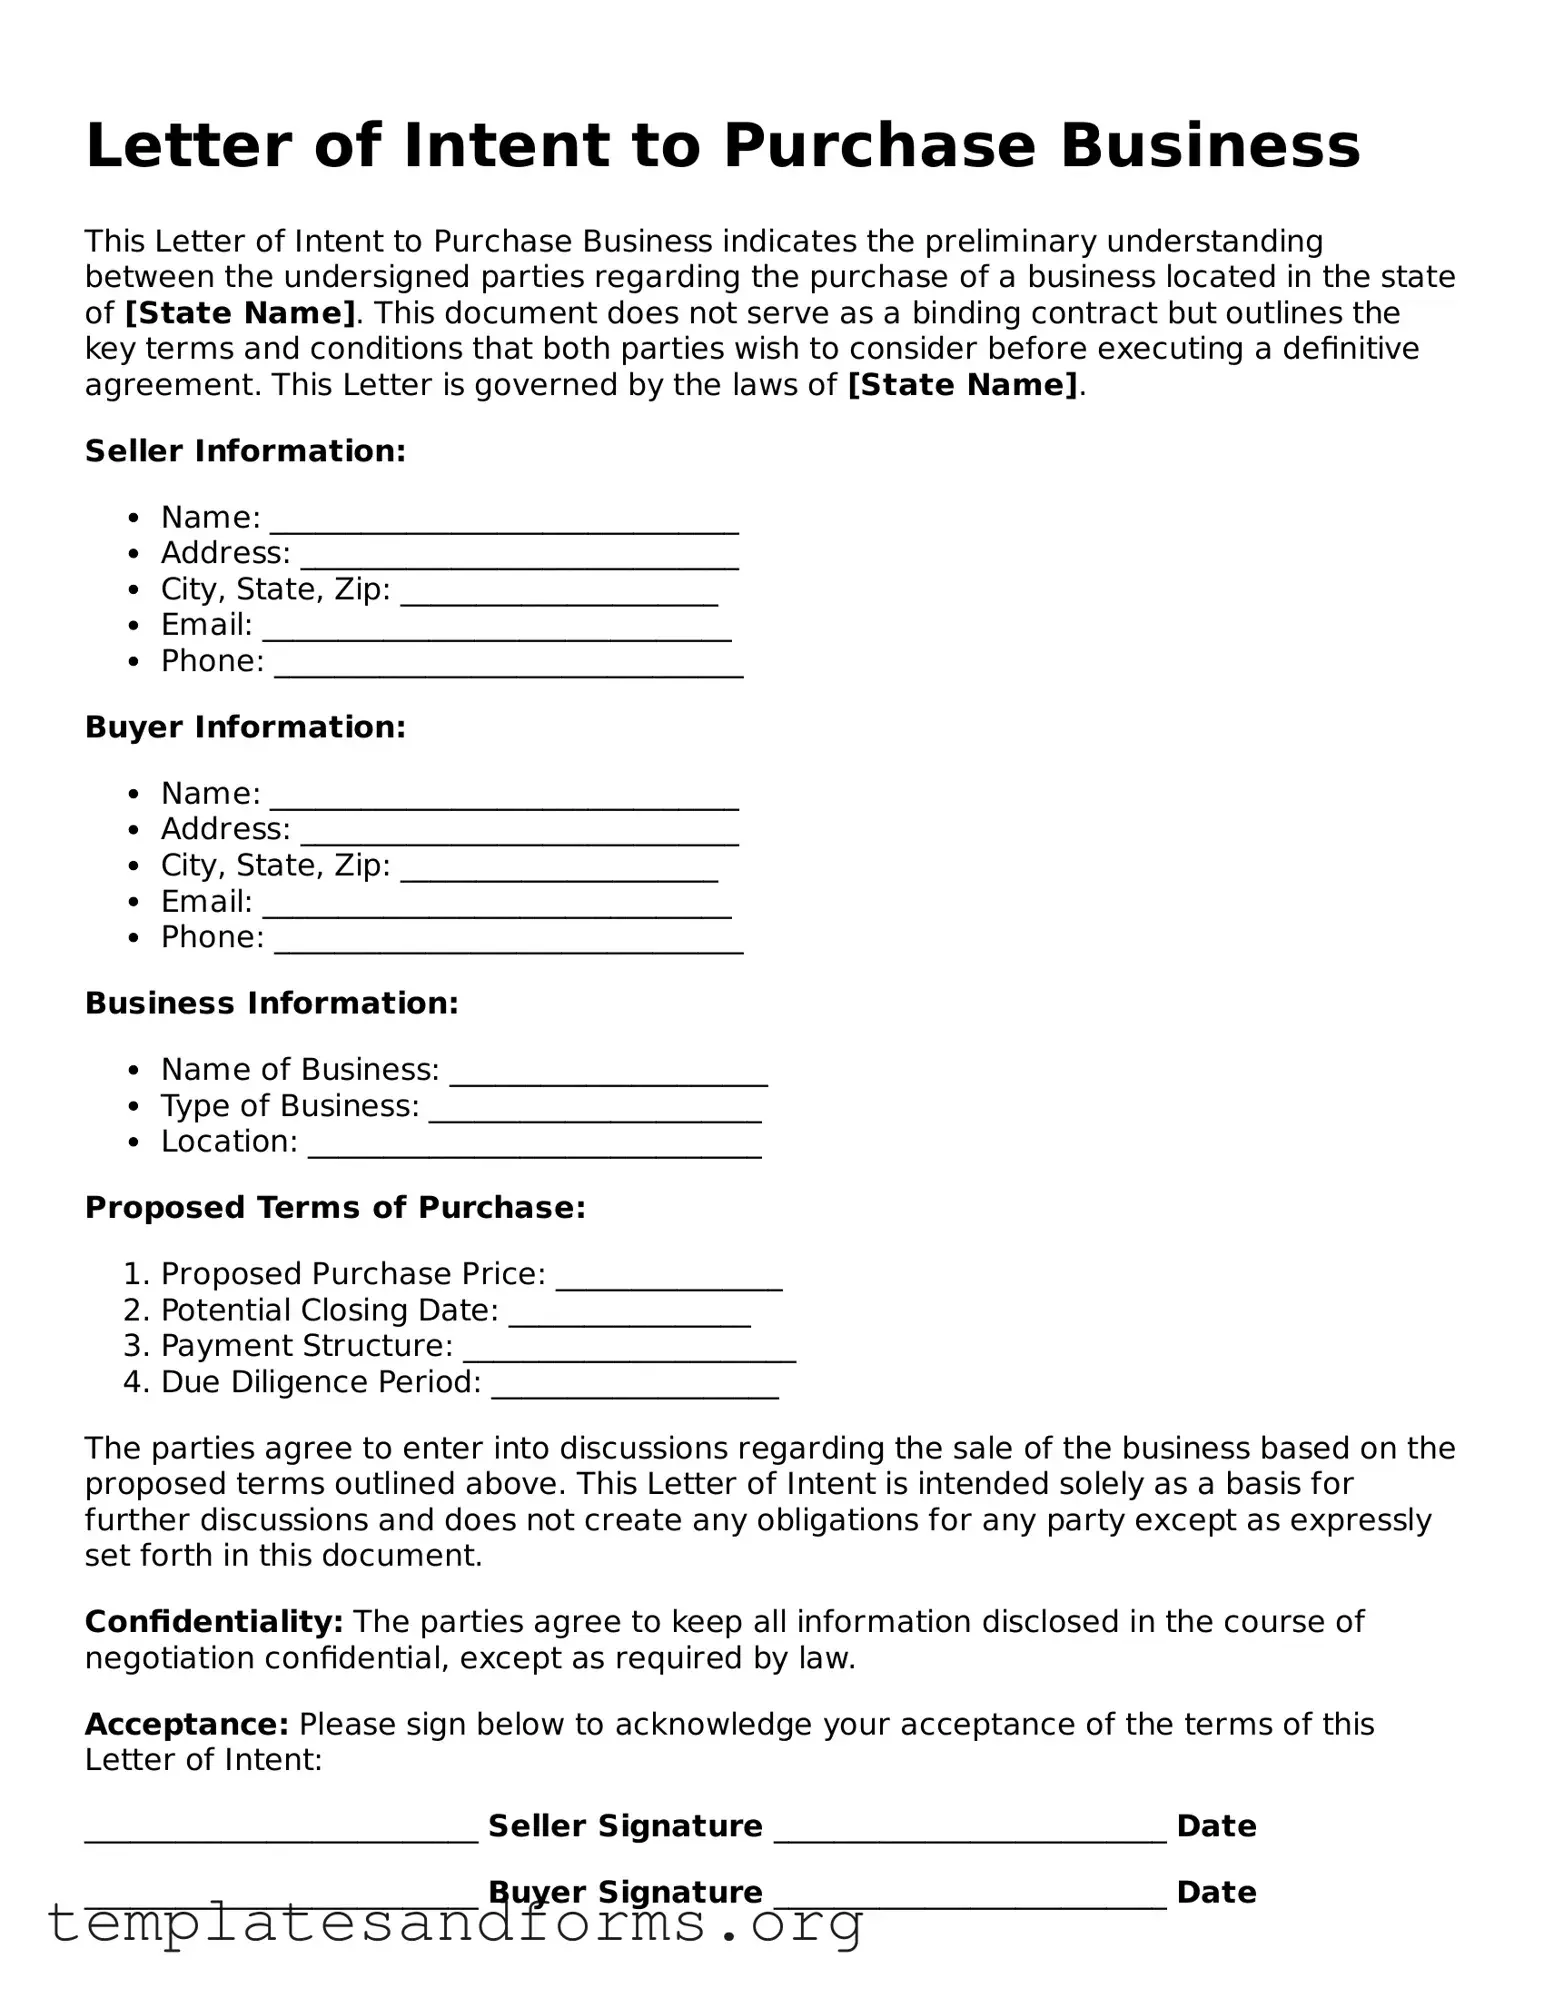
Confidentiality is another section people treat lightly. The template should explicitly state that the buyer cannot share the seller's financials, customer lists, or operational data with anyone outside the immediate advisory team. Attach a separate NDA if needed. The template alone is usually not enough for sensitive industries where information leaks can destroy competitive advantage overnight.
What Most People Miss About These Documents
The first thing beginners misunderstand is that an Of Intent To Purchase Business Template is typically non-binding except for specific clauses. The purchase price and structure sections are usually non-binding because neither side wants to be locked in before due diligence completes. But the confidentiality and exclusivity clauses are typically binding. If you violate those, you can get sued even though the overall deal is not yet signed. The second thing people miss is that this document sets the tone for the entire negotiation. A sloppy template signals that you do not know what you are doing. A seller who receives a poorly drafted version will either raise their price to compensate for perceived risk or lose interest entirely. I have seen legitimate deals die because the buyer sent in something that looked like it was written in an afternoon by someone who had never closed a business transaction before.
When This Approach Fails Completely
The biggest limitation is that a template cannot anticipate every edge case in your specific deal. It works fine for straightforward small business sales where assets, inventory, and some goodwill are all that change hands. It breaks down when you have complex earnout structures, multi-party ownership, intellectual property licensing, or regulatory compliance issues that need custom language. In those situations, a generic template becomes a liability because it gives you a false sense of security. You think you are covered when you are not. Another failure scenario involves high-conflict sellers who use the exclusivity period as a weapon. If a seller gets cold feet after receiving an offer, they can sometimes drag their feet on due diligence access, making the exclusivity period meaningless. The template has no mechanism to force cooperation beyond breach of contract claims, which are expensive and slow to pursue. In practice, this means you may pay for the exclusivity and still end up with nothing if the seller is being difficult. If you are dealing with any of those complications, skip the template approach and go directly to an attorney-drafted letter of intent. The extra cost is real, but it prevents far more expensive problems later. For simple transactions under five hundred thousand dollars in value, the template route is usually efficient and adequate. Beyond that, the margin for error shrinks dramatically and the stakes justify professional drafting.