Building a usable Oil And Gas Financial Model Xls
Most people approach these models from the wrong angle. They start by laying out revenue lines and then try to fit costs around it. That never works because the cost structure drives everything in oil and gas. Field development decisions change the decline curve, which changes cash flow, which changes whether the project passes hurdle rate. If you build bottom-up from expenses and reserves, the model actually tells you something useful. I built my first proper basin-model at a small E&P company in 2011. We were trying to value a Permian acreage package. The model took three weeks to complete because nobody had thought through how to handle differential pricing across multiple delivery points. The takeaway was straightforward: separate your price assumption sheet from your production forecast immediately. When those two things are locked together in one messy block, a single basis assumption change forces a search-and-replace that will miss three cells and break your NPV calculation by about eight percent.
Where to get a functional Oil And Gas Financial Model Xls
You can download various templates online. The ones from consulting firms are decent starting points but they are usually optimized for presentation rather than actual forecasting. A lot of free templates online skip composite lifting cost calculations entirely or use single-cycle depreciation that doesn't match actual field tax structures. Before you download anything, check whether the model handles DD&A (depletion, depreciation, and amortization) using the successful efforts method versus full cost. Those two approaches produce wildly different tax shield profiles and if the template gets this wrong, every metric downstream is inaccurate. The Institute of Energy Economics and Financial Analysis publishes a solid template that covers the basics reasonably well. It is free to members and available to non-members for around fifty dollars. For most smaller operators, that investment pays for itself quickly because the production table alone is properly structured with month-by-month decline curve integration and a clean link to reserves reporting.
The core components you need to model correctly
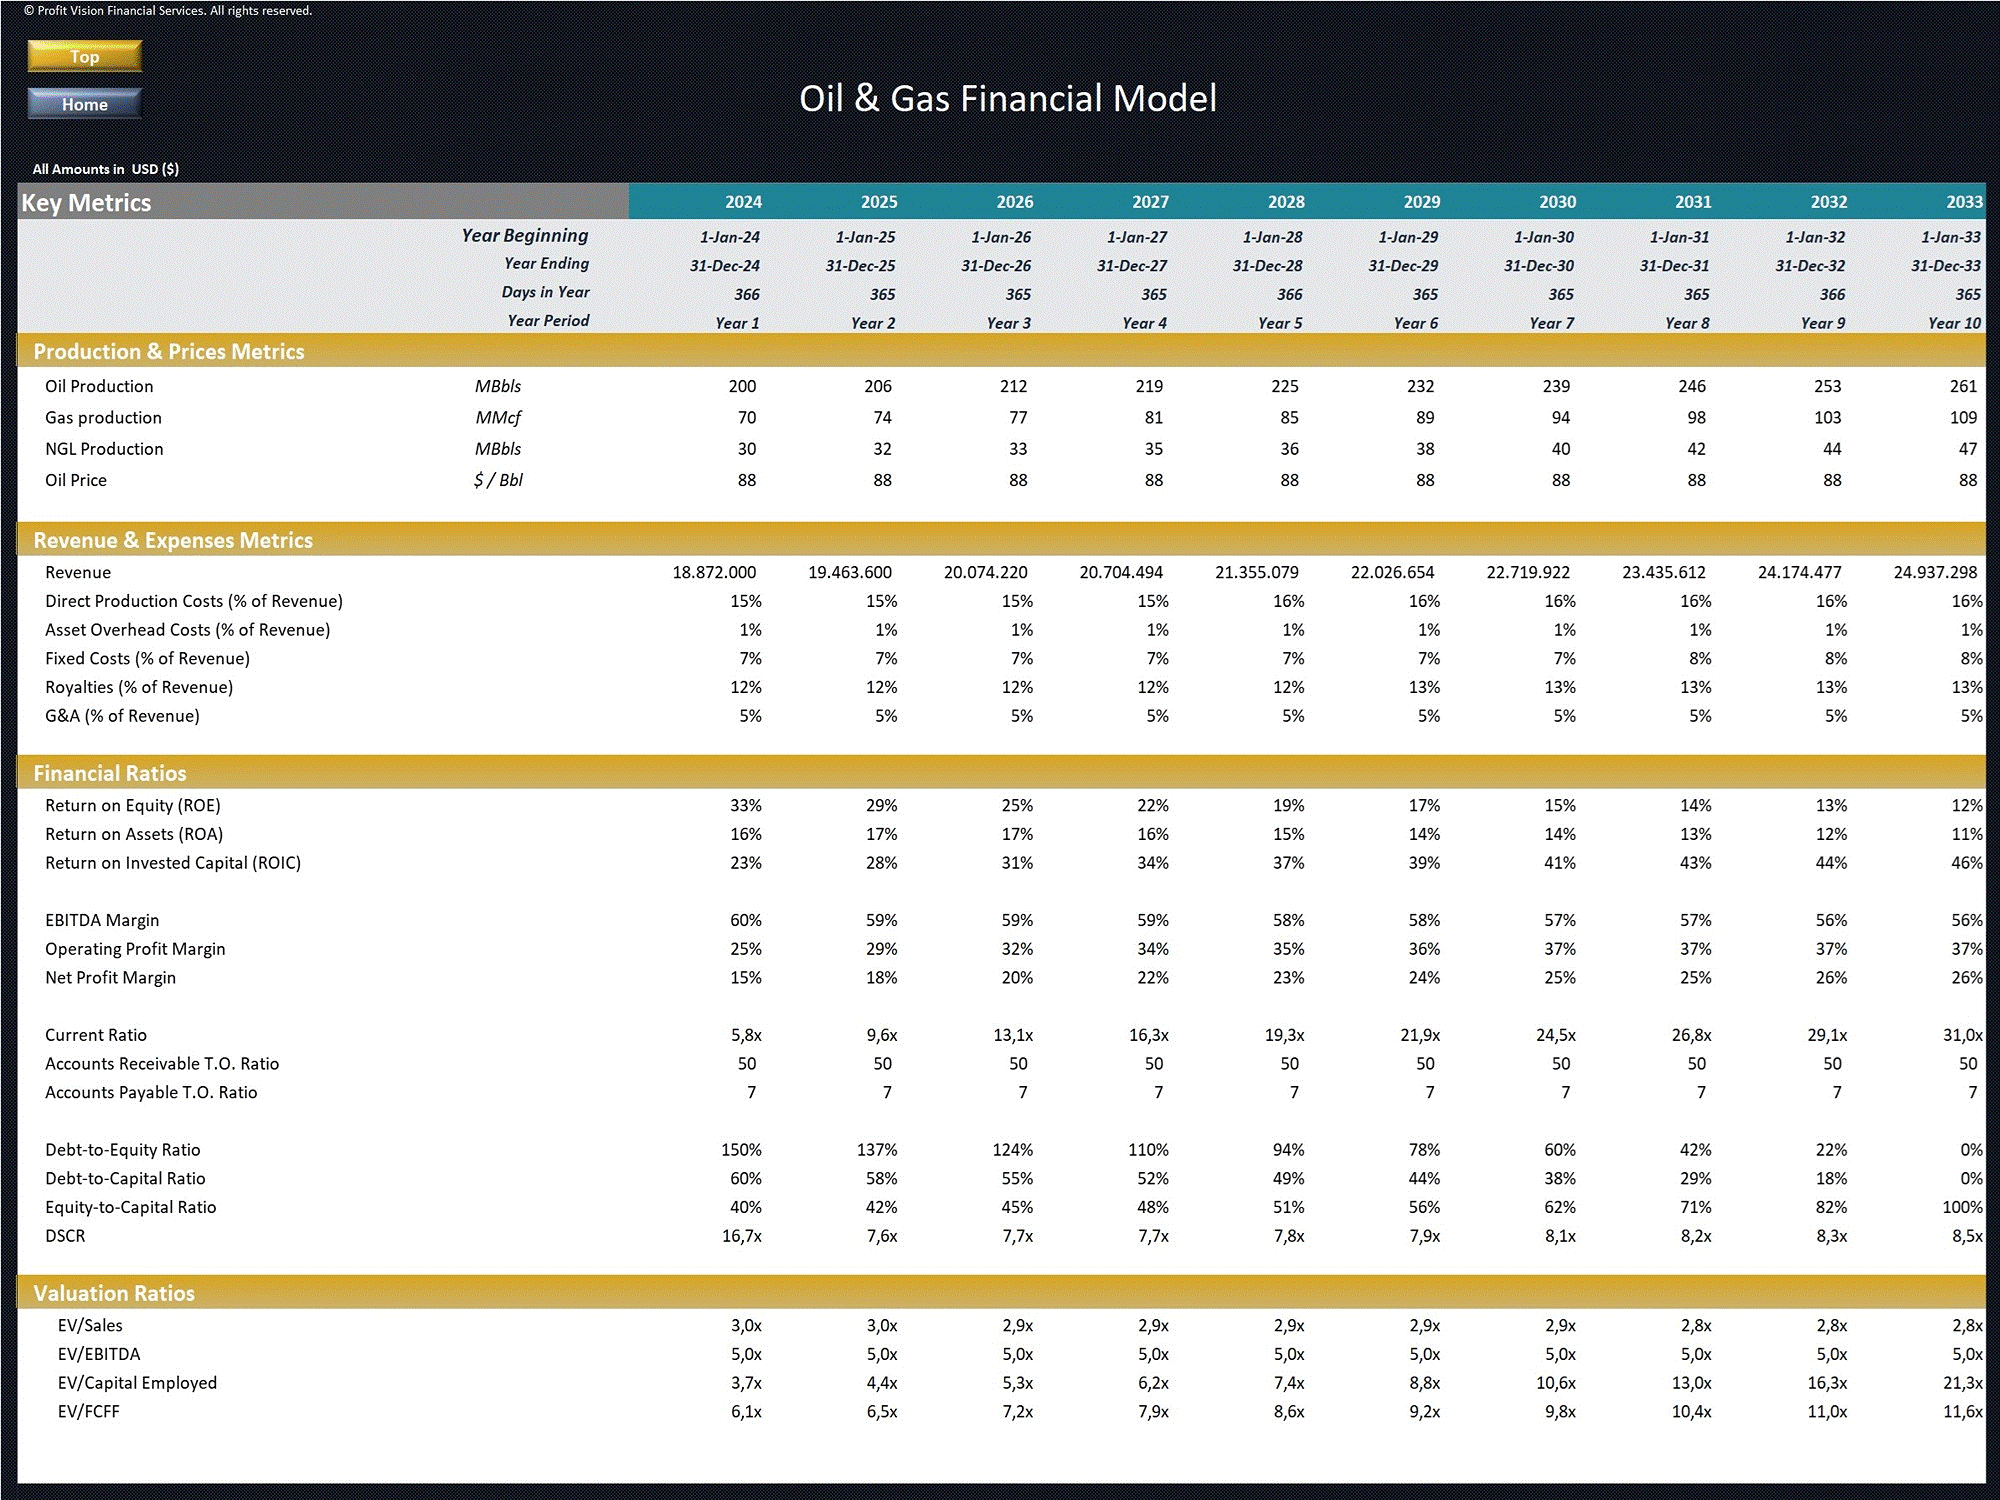
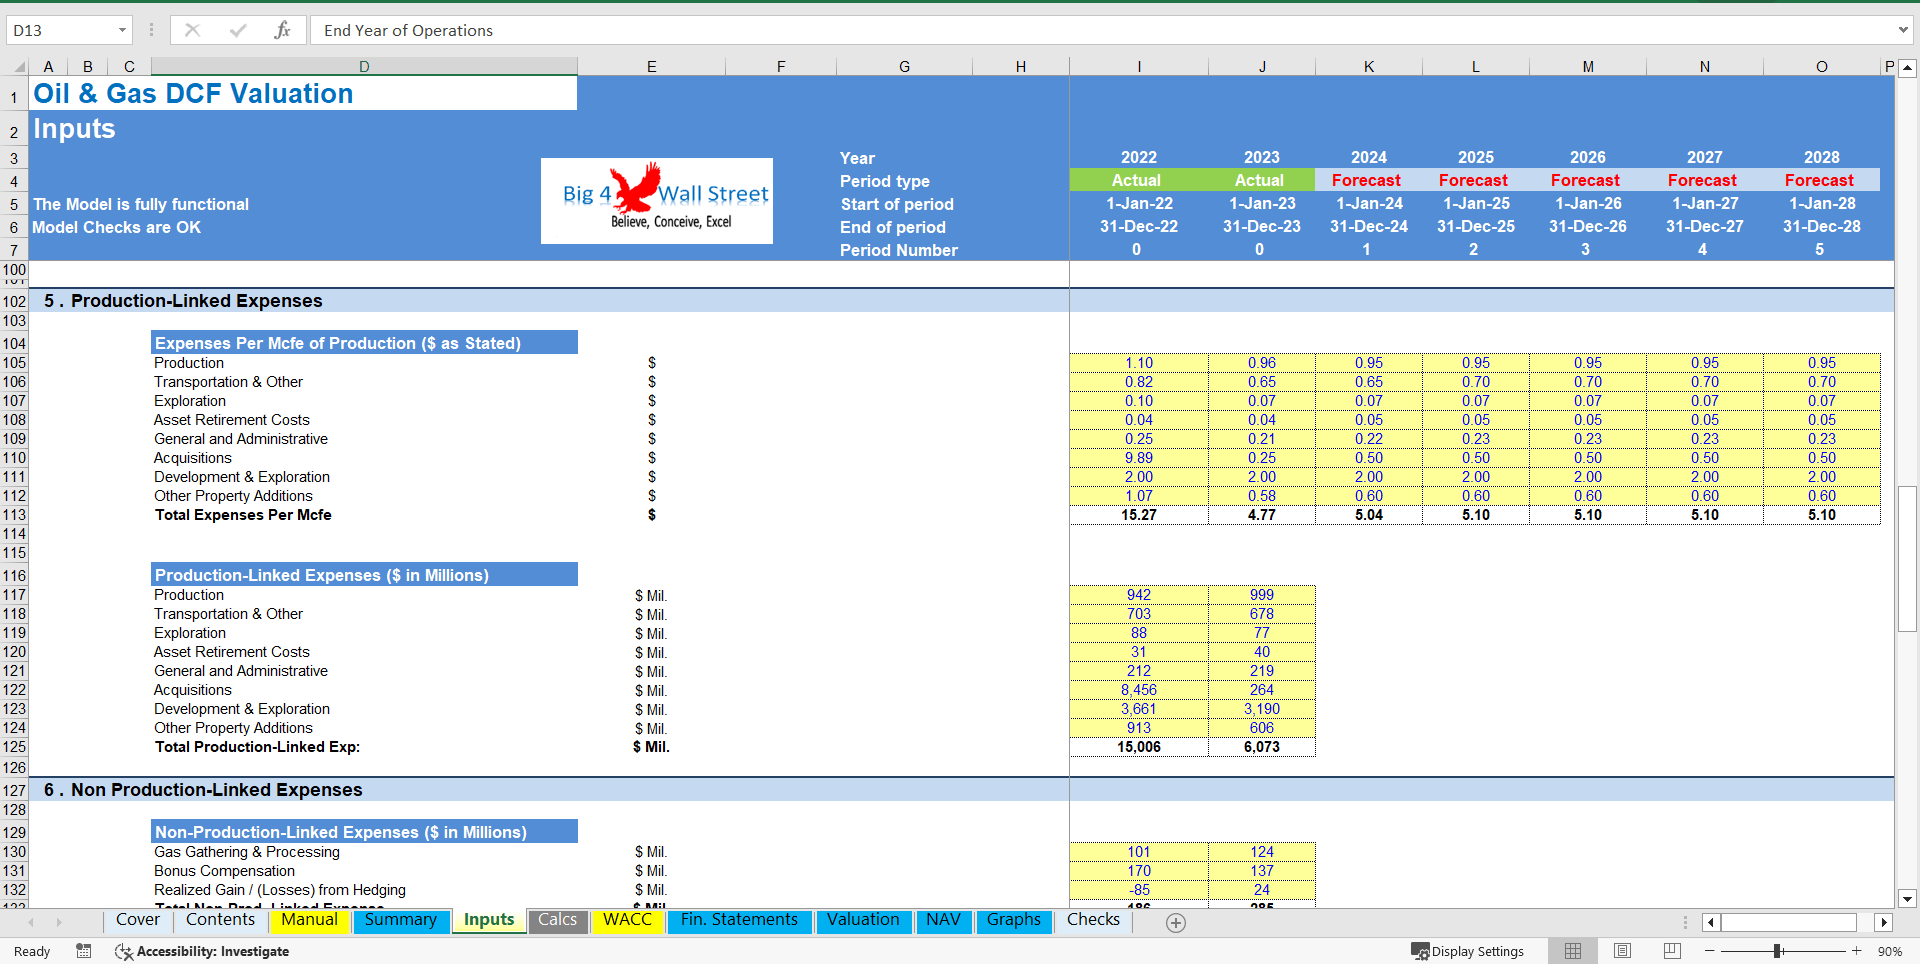
A proper financial model for oil and gas needs these sections working in sequence. The reserves and production section comes first. This is where most models break. You need individual well or field decline curves that roll up into a total production forecast. The ARPS hyperbolic decline equation is standard, but you also need to account for infill drilling and secondary recovery methods if they apply to your asset base. A single decline curve for an entire field masks the reality that new wells have steep early declines while mature wells stabilize. I once saw a model that used a flat production assumption for years three through seven on a shale play. The equity valuation came out completely wrong because the model implied steady cash flows where the actual pattern has a sharp front-loaded profile. Lifting costs come next. These are not uniform across wells or even across months within a well. Water cut increases over time, which raises artificial lift costs. Gas lift compression costs vary with reservoir pressure. If your model uses a single cents-per-barrel lifting cost assumption for the entire life of the asset, it will understate costs in later years by roughly fifteen to twenty-five percent depending on the basin. Build lifting cost as a function of water cut and production volume. It takes maybe thirty minutes more upfront and saves you from defending flawed unit cost assumptions in a due diligence meeting.
Get the Full Details
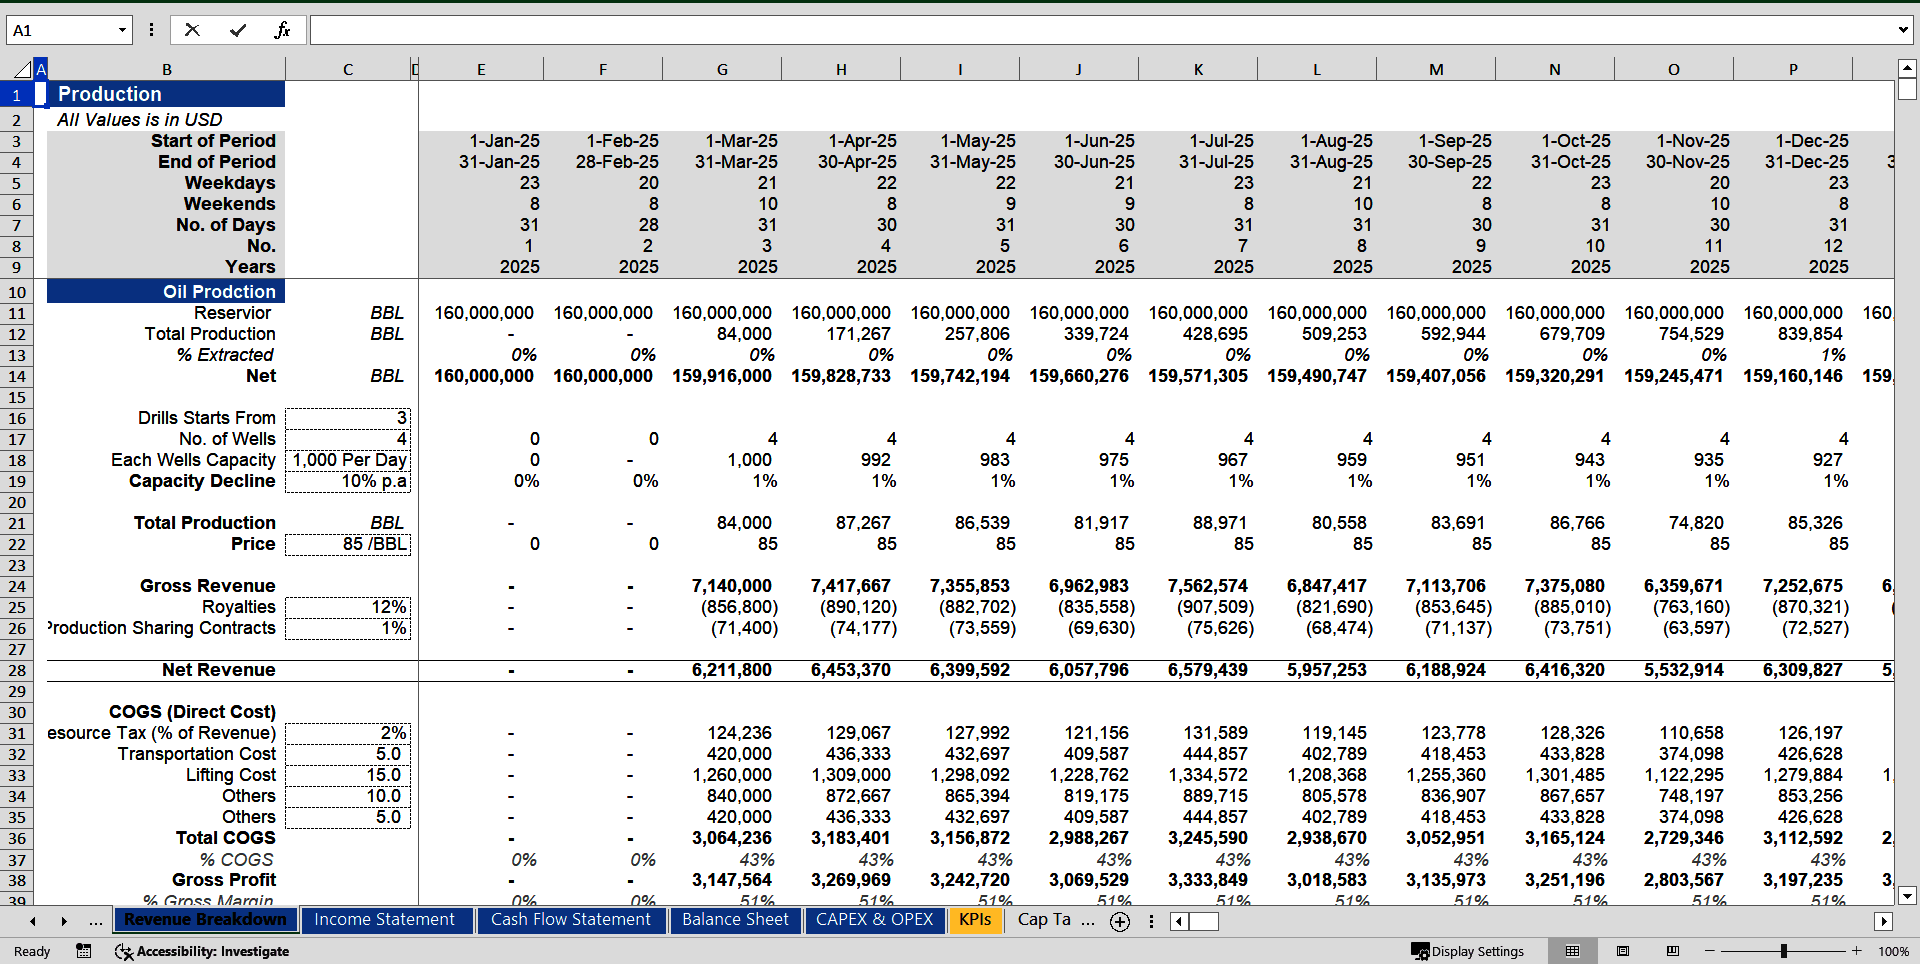
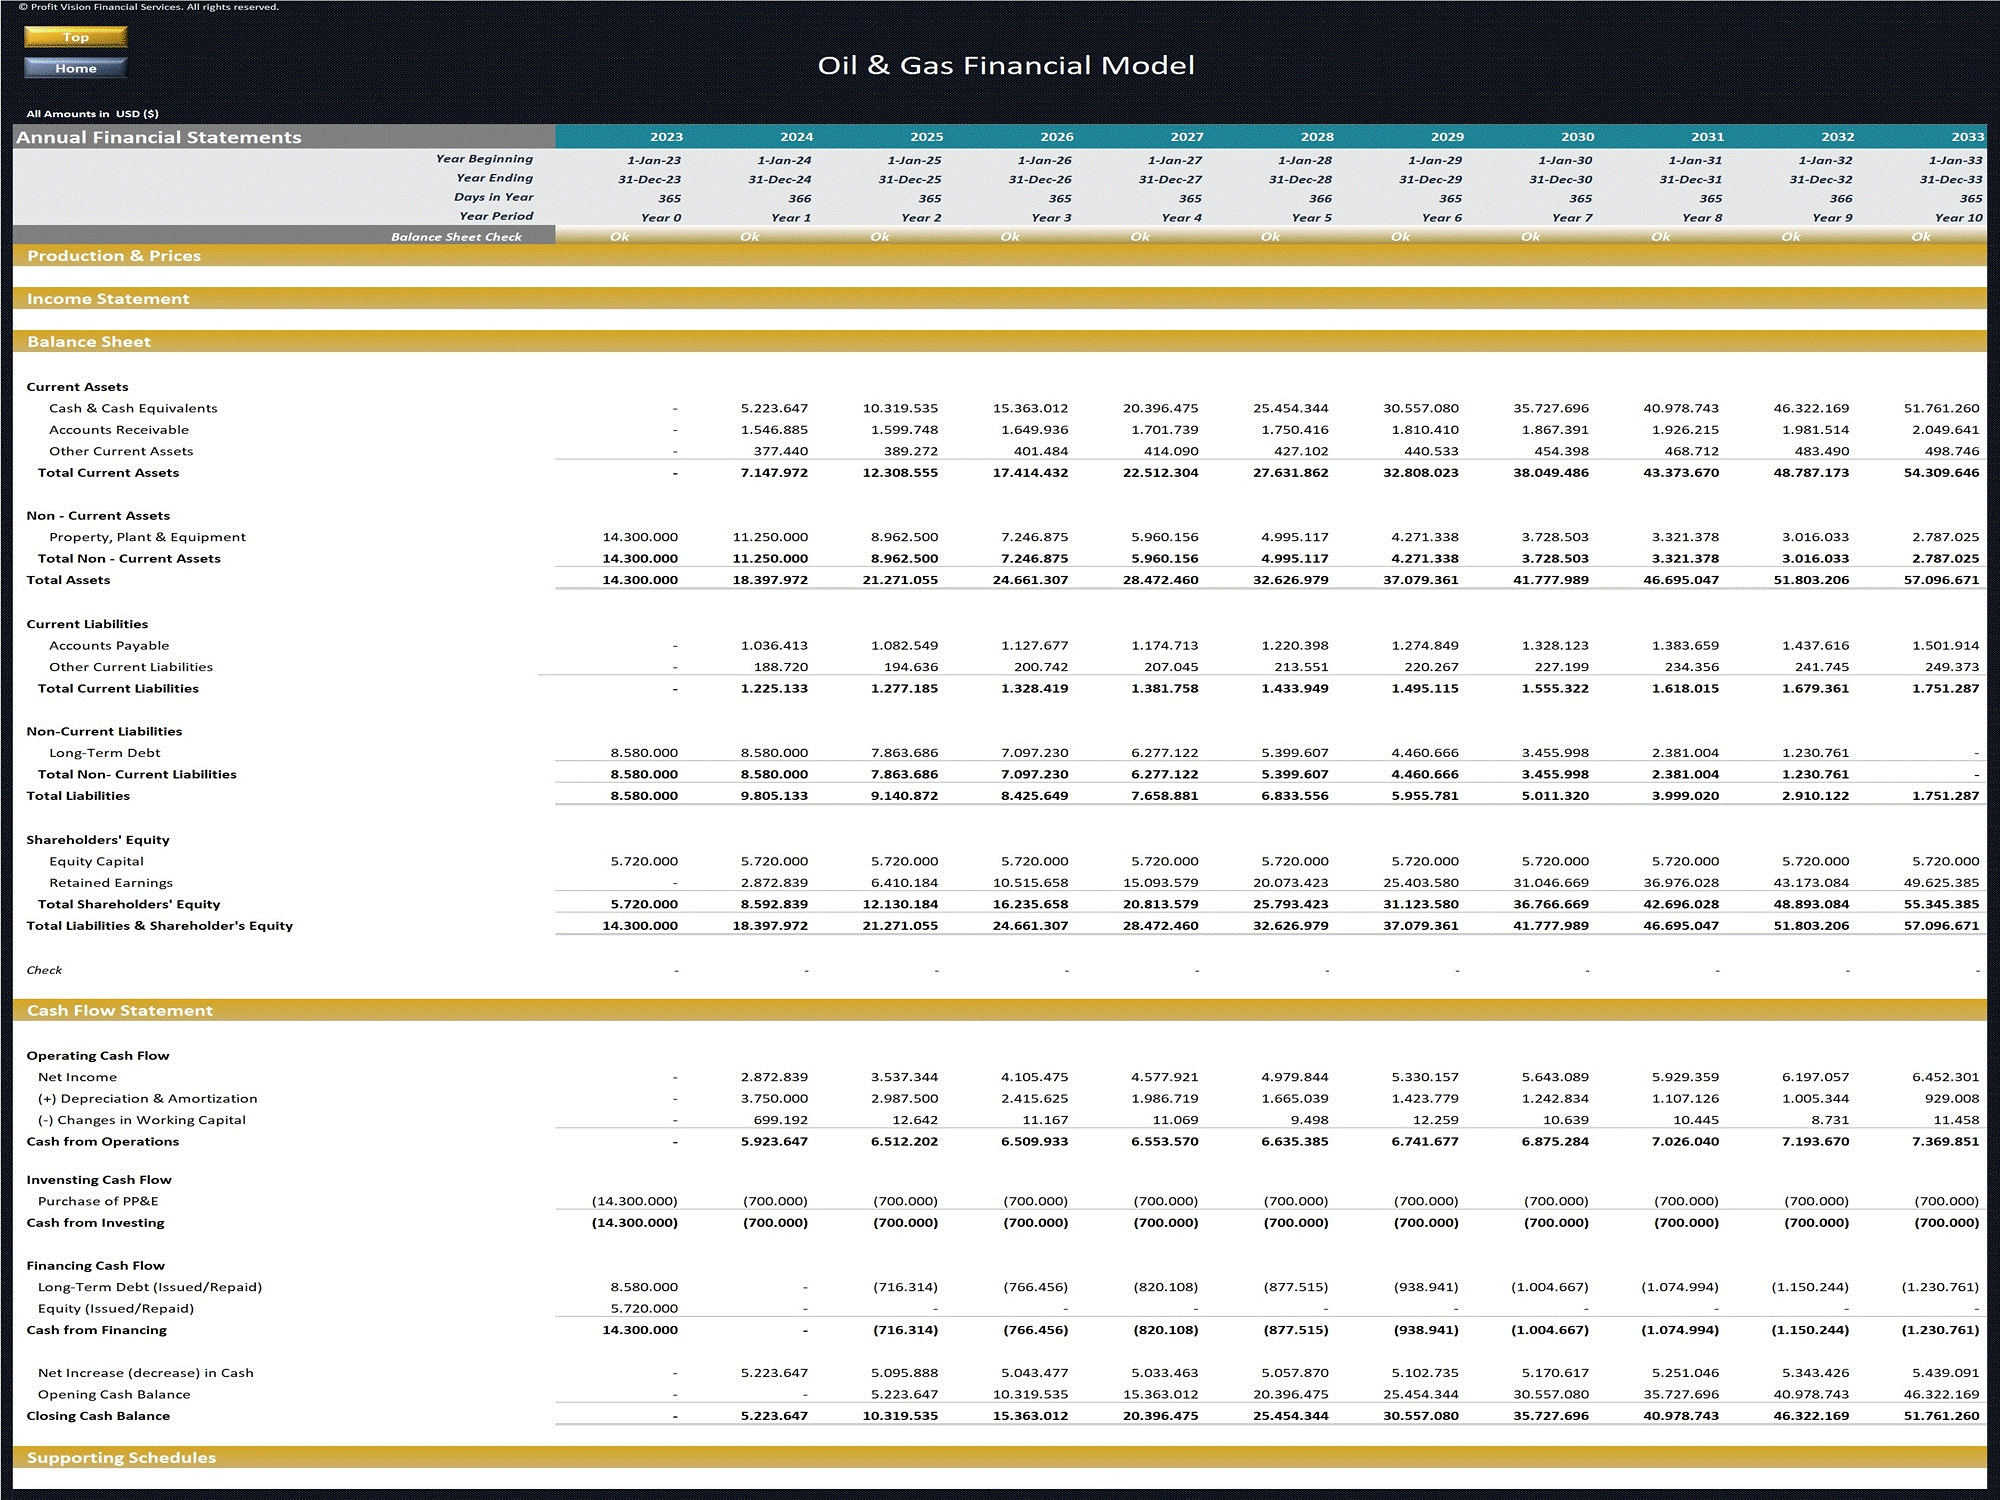
Capital expenditure needs separation between capex and operating expenditure. Drilling and completion costs are capital. Workover costs may be capital or expense depending on whether they restore or enhance production. Royalty payments follow revenue at the agreed percentage. Processing and gathering costs depend on whether you sell at the headgate or a midpoint point of delivery. These details matter for valuation because they determine your netback, which is the actual revenue number that feeds into everything else. The tax section is where non-specialists spend too little time.royalties are deducted before income tax. Depletion deductions reduce taxable income significantly in early years. State severity taxes vary by jurisdiction and are usually calculated on gross revenue before royalties. If you are modeling international assets, you need to layer in profit oil and gas provisions, production bonuses, and possibly stabilization clauses. I worked on a model for a West African offshore project where we missed the adjustment to the royalty rate based on a profitability threshold. The error inflated projected government take by about twelve percentage points and almost cost us the bid. Discounted cash flow sits at the end. Weighted average cost of capital for oil and gas companies typically ranges from ten to twelve percent for stable producing companies and fifteen to twenty percent for explorers. The discount rate choice dramatically affects valuation in long-life projects. A five percent difference in discount rate can swing NPV by thirty percent or more on a twenty-year field development.
Common mistakes I see repeatedly
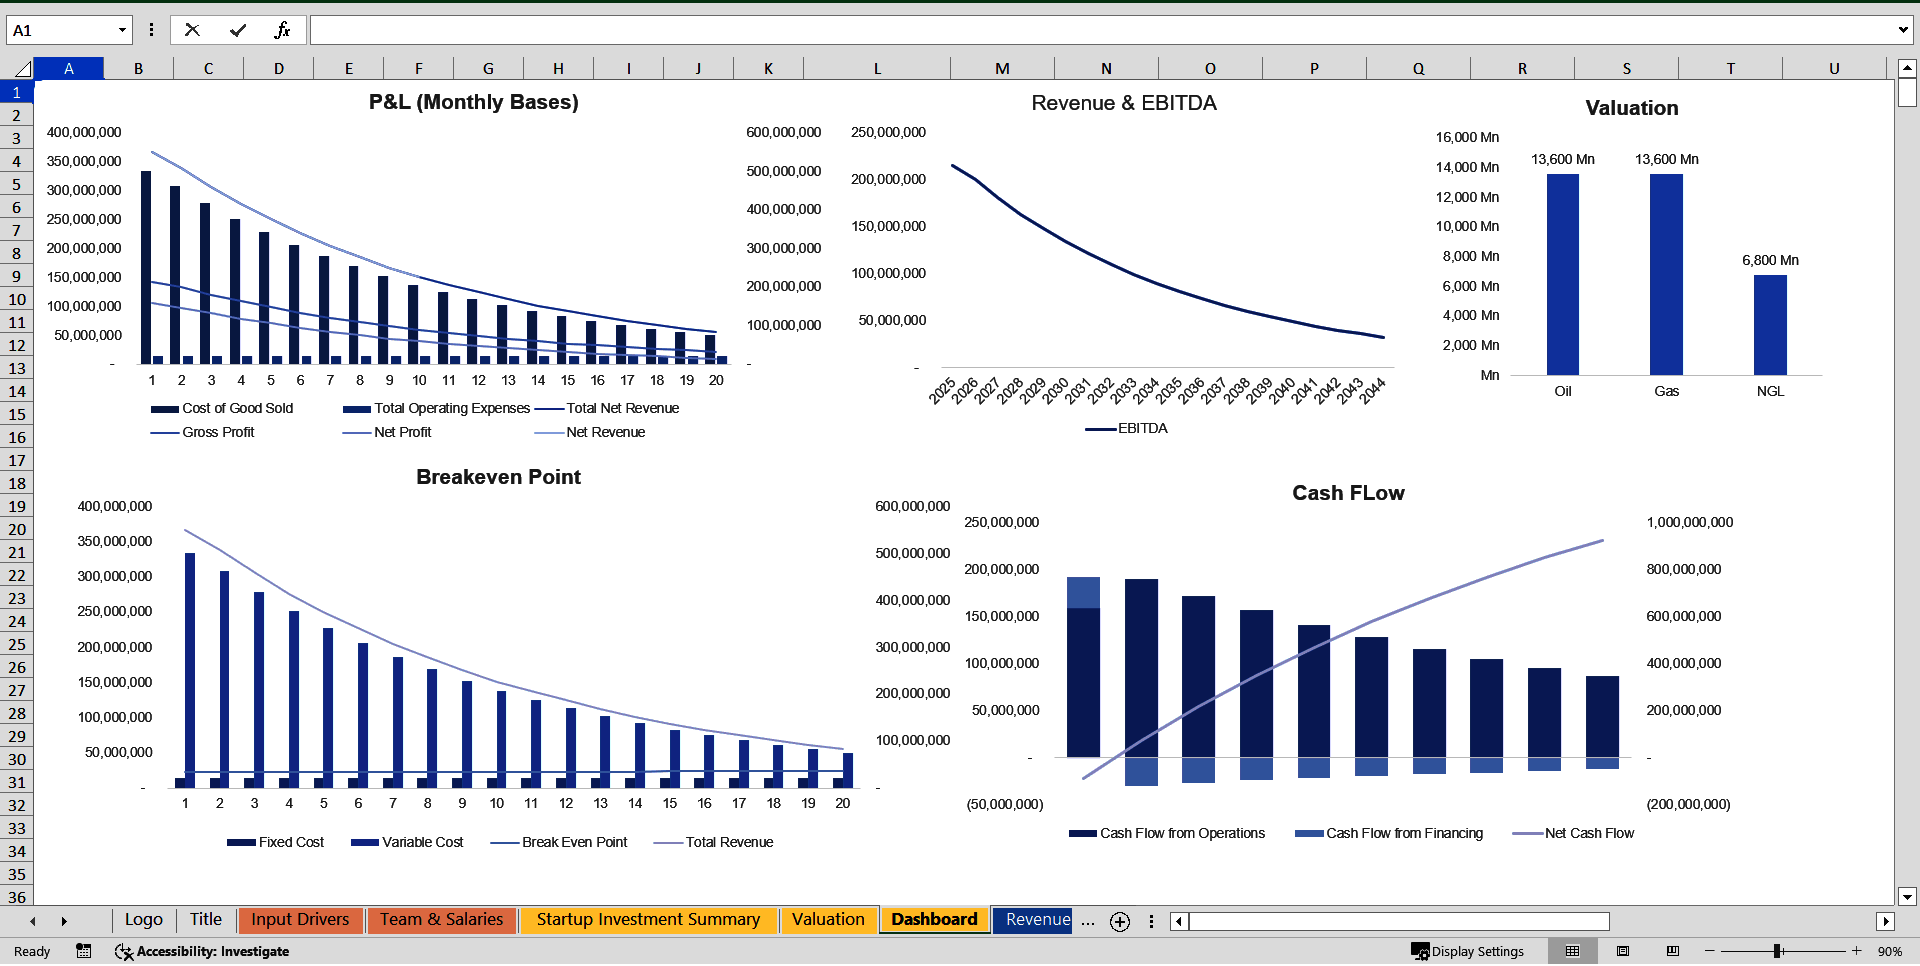
People ignore timing. Cash flow in oil and gas is lumpy. Drilling campaigns create large capital outlays at specific points. Production ramps up gradually. If your model distributes annual capex evenly across quarters or annualizes monthly cash flows without proper timing, your internal rate of return will be off. I learned this the hard way when valuing a Gulf of Mexico deepwater project. The model showed an IRR of fourteen percent. After rebuilding the cash flow timing to reflect actual quarter-by-quarter spending and production start dates, the IRR dropped to eleven percent. The project still passed hurdle rate, but barely, and the board would have made a very different decision with the flawed numbers. Another frequent error is treating price as a single forward curve for everything. Different grades of crude trade at different spreads. WTI, Brent, Light Louisiana Sweet, Midland differential. If your production spans multiple delivery points, model each separately. A single blended price assumption can introduce material error, especially in basins with significant transportation bottlenecks like the Eagle Ford or Bakken. People also forget about abandonment and reclamation costs. These are real liabilities. The model should include a provision for well plugging and site restoration at the end of economic life. In some jurisdictions these are required reserves on the balance sheet. Even if they are not, they represent a future cash outflow that belongs in your model. I once valued a company that had three hundred wells past their economic life with no provision for plug and abandonment. The liability was approximately forty million dollars. It showed up six months later during due diligence and nearly sank the transaction.
When Excel is the wrong tool
Financial modeling XLS sheets work fine for single-asset valuations, portfolio screening, and deal analysis. They break down when you need stochastic simulation, real options valuation, or integrated reservoir-to-economics workflows. If your team is doing Monte Carlo analysis on fifty variables across a dozen fields, Excel will be slow and error-prone. Specialized software like Nexus, Advantage, or even Python-based solutions handle that workload much better. Even within Excel, there are limits to what you can automate cleanly. Version control is a constant problem. File-sharing platforms create parallel edits that overwrite each other. I have seen two analysts working on the same model file simultaneously on SharePoint and end up with two versions that disagreed on depreciation assumptions. The solution is to lock the calculation engine behind a parameter sheet and require all changes through documented version increments. Track every change in a dedicated log. It sounds tedious but it prevents the kind of embarrassment that comes from presenting numbers to a committee and having someone ask about a cell reference that was changed six months ago without documentation. The practical approach is to use Excel for what it does well, which is transparent financial computation and scenario analysis, and be honest about its limitations. Build the model with clear separation between inputs, calculations, and outputs. Use color coding that everyone in your organization understands. Inputs in blue. Hardcoded numbers in black. Formulas in gray. This convention takes five minutes to establish and prevents at least half the questions you will get during review.
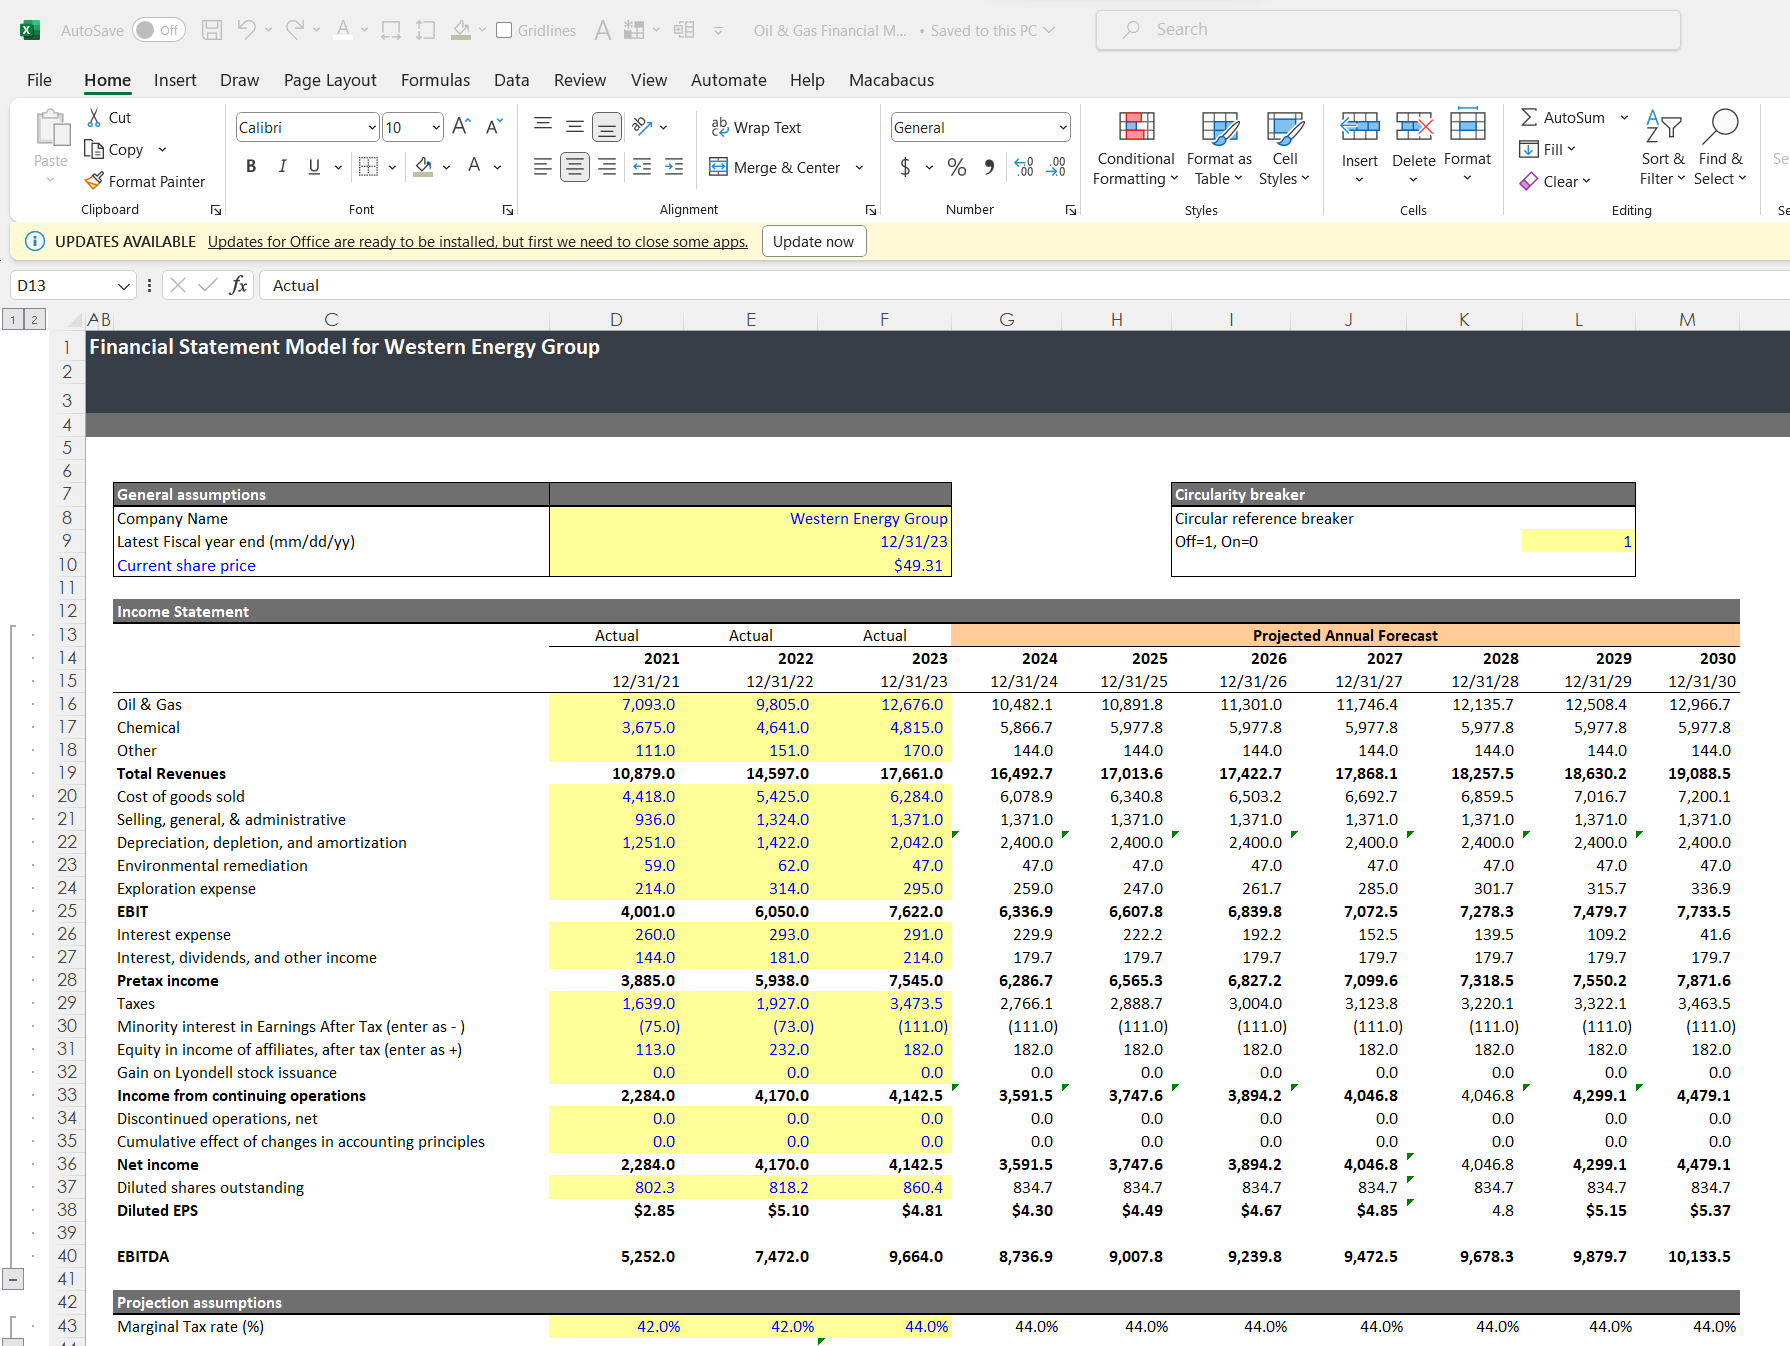
Most importantly, validate your model against actual field data before anyone makes a decision based on it. Run the model against the last three years of production and compare the output to what actually happened. If the model cannot reproduce known results, it will not predict unknown ones accurately. This validation step usually catches calculation errors, incorrect decline parameters, and misunderstanding of the actual cost structure. It takes about two hours and it is the single most valuable thing you can do before running any forward-looking analysis.