Understanding Oklahoma Form 200 for Corporate Tax Filing
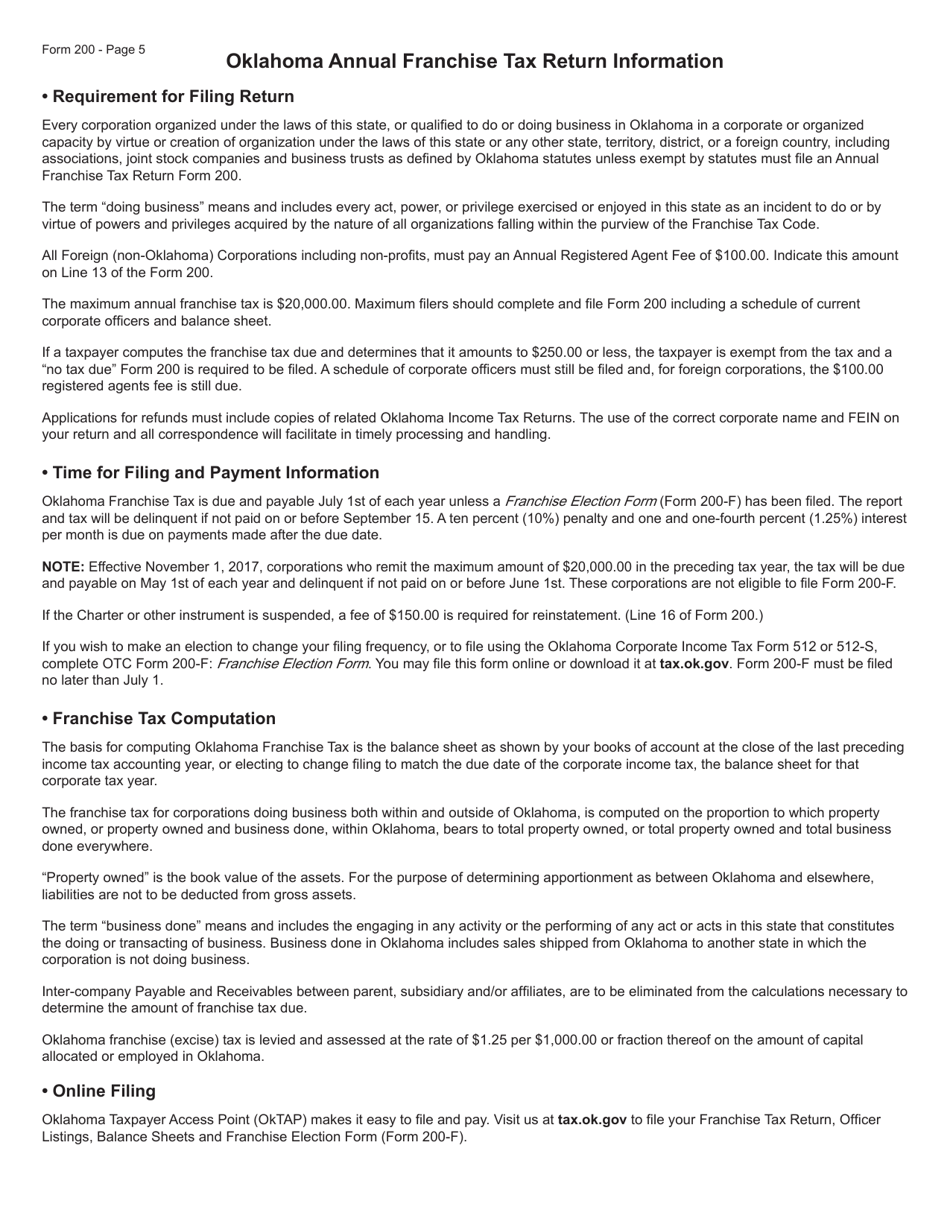
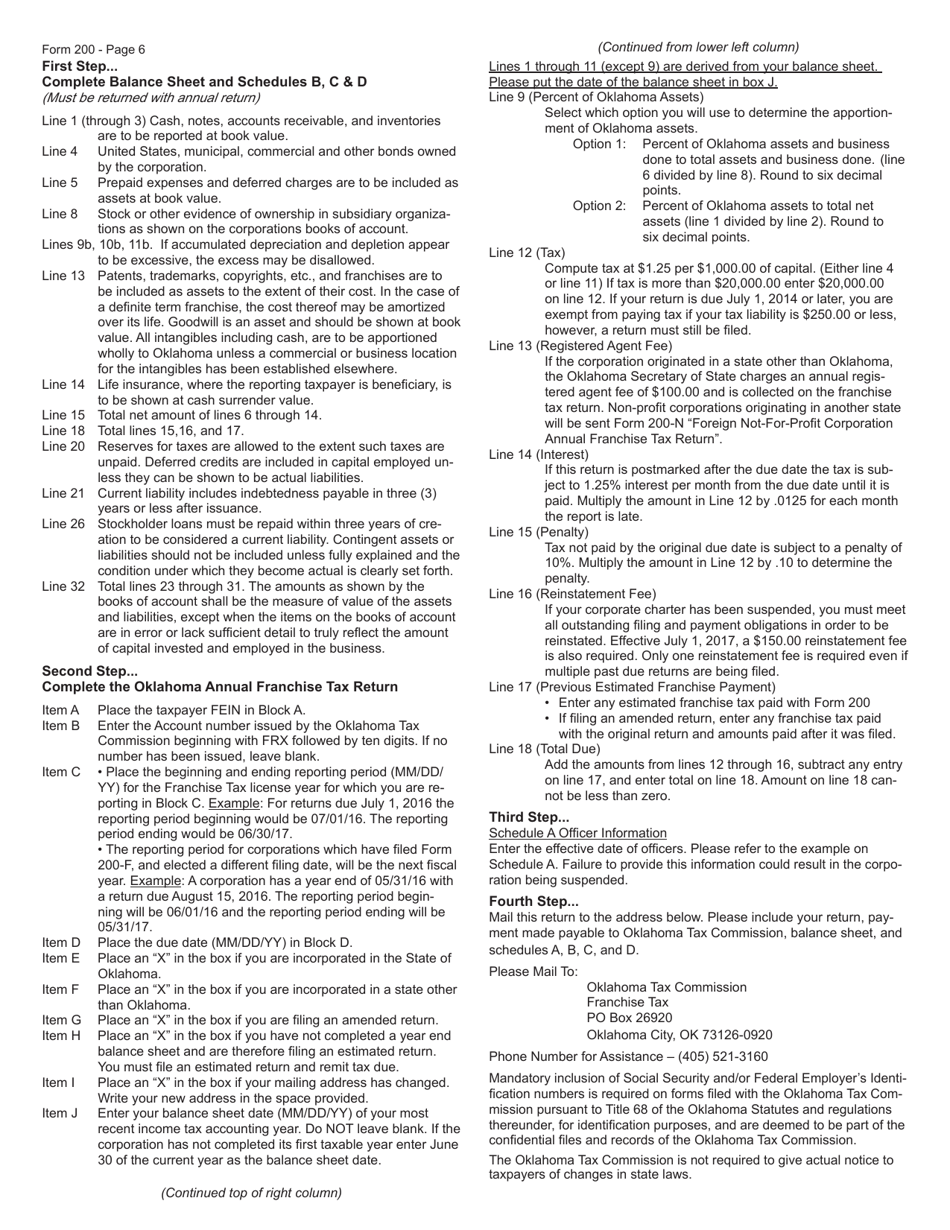
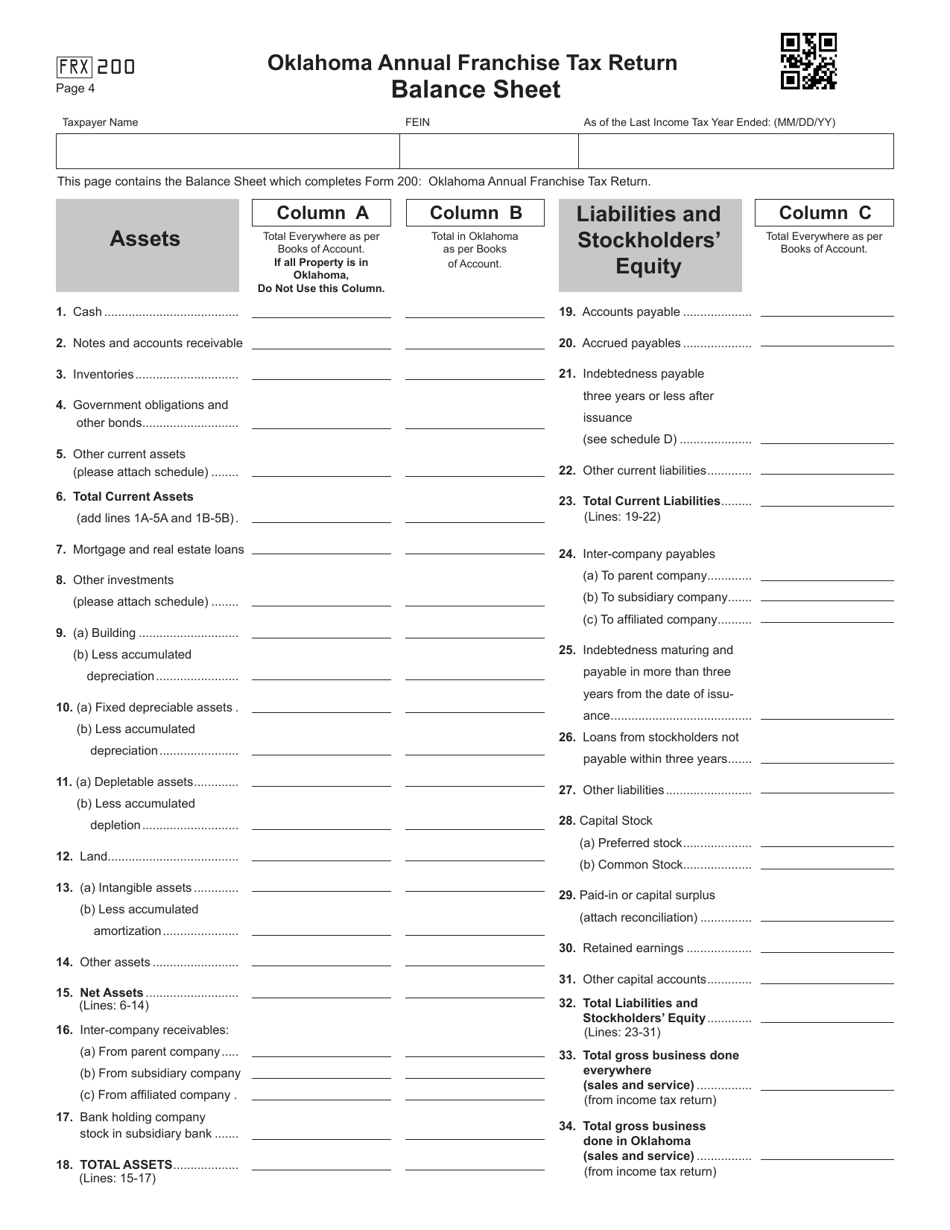
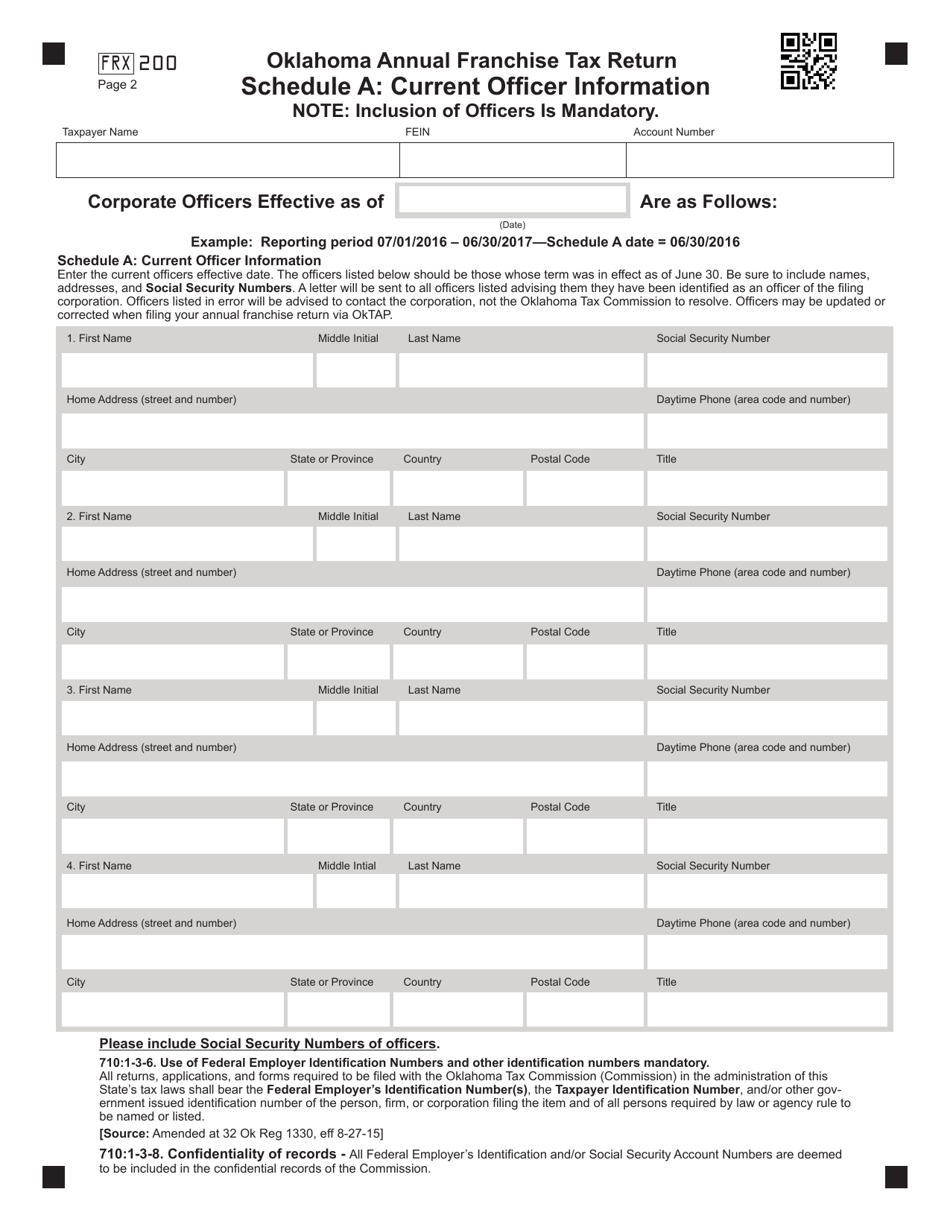
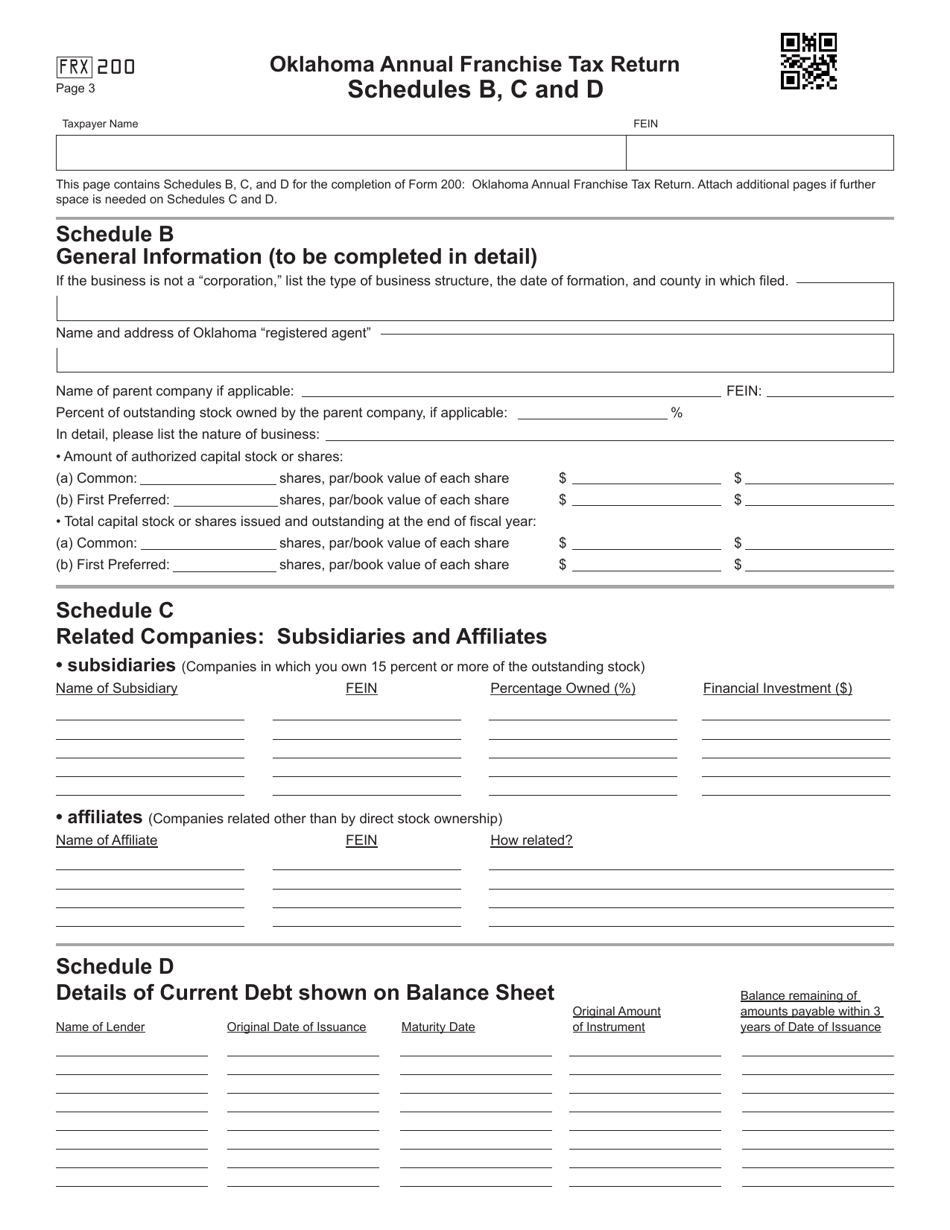
The Oklahoma Form 200 is the state income tax return used by C corporations doing business in Oklahoma. It is straightforward on the surface, but the instructions document contains enough edge-case language that filing it without reading carefully will cost you money. I spent three years handling Oklahoma corporate returns before I learned that a single line on the back page can change your entire liability calculation. You can download the current year Form 200 and its accompanying instructions directly from the Oklahoma Tax Commission website at oklahoma.gov/otc. The instructions PDF typically runs about 40 to 60 pages depending on whether credit schedules and worksheet addendums are included. The commission updates the forms annually, usually releasing revised versions in late January or early February ahead of the April 15 filing deadline. Always verify you are using the most recent version, because line numbers shift slightly from year to year and referencing an outdated form against current instructions is an easy way to make a costly error. Before I explain how to actually fill it out, you need to understand one thing that nobody emphasizes enough. The Oklahoma Form 200 does not simply ask you to plug in your federal taxable income and move on. Oklahoma requires several addbacks and subtractions that most people miss on their first attempt. The starting point is your federal taxable income as reported on your federal Form 1120, but then you have to adjust for Oklahoma-specific modifications.
The most common addback is for federal net operating loss deductions. If you claimed an NOL carryforward on your federal return, Oklahoma generally requires you to add that amount back unless the loss originated from an Oklahoma-source transaction. Another frequent adjustment involves depreciation. Oklahoma does not conform to all the federal bonus depreciation provisions, so you may need to add back the portion of your federal depreciation that came from bonus or special depreciation deductions taken on your federal return. Here is a specific problem I ran into that illustrates how easy it is to mess this up. A client of mine had a federal Form 1120 that showed a significant state tax subtraction on Schedule A, line 24. The amount was large enough that it materially reduced their Oklahoma taxable income. When I reviewed their Oklahoma return, I noticed they had carried that subtraction forward from a prior year where they had overpaid Oklahoma corporate income tax. The issue was that the original overpayment had been the result of an estimated tax payment that was allocated incorrectly between multiple Oklahoma county filings. I caught it during a routine reconciliation, but it had gone uncorrected for two tax years. The workaround was to file an amended Oklahoma return for the earlier year to correct the county allocation, then adjust the current year's subtraction accordingly. It took about four hours of work and required cross-referencing three different years of filings. The correction saved them roughly $18,000 in overstated tax liability. The credits section of the Oklahoma Form 200 is where things get complicated. Oklahoma offers several business credits, including the research and development credit, the job training credit, and various industry-specific incentives. Each credit has its own separate schedule and its own set of eligibility requirements. The R&D credit in particular requires you to complete Schedule 200-RD, and the calculations there depend heavily on how you define qualified research expenses under Oklahoma law, which does not always align perfectly with the federal definition. One nuance that trips people up is that Oklahoma allows a carryforward for excess credits, but the carryforward period is limited to ten years, not indefinitely like some other states.
Estimated tax payments are another area where mistakes happen regularly. If your Oklahoma corporate income tax liability for the current year is expected to be $500 or more after subtracting withholding, you are required to make estimated tax payments. The due dates for Oklahoma estimated payments align with the federal schedule: April 15, June 15, September 15, and December 15. You can use Form 200-ES to calculate and remit your estimated payments. The penalty for underpayment is calculated using the same methodology as the federal underpayment penalty, but Oklahoma uses its own daily composite rate for the computation, which changes quarterly. Most accountants I know just use the annualized income installment method to minimize penalty risk when revenue is uneven throughout the year. One thing worth noting about the Oklahoma Form 200 Instructions is that they do not provide exhaustive examples for every scenario. You will often need to cross-reference with federal instructions or consult Publication 1021, which is the Oklahoma Tax Commission's guide to corporate taxation. That publication covers topics like income apportionment for multistate corporations, which is relevant if your business operates in more than one state. Oklahoma uses a single-sales-factor apportionment formula for most businesses, meaning your Oklahoma taxable income is determined by dividing your total sales by your total sales everywhere and multiplying that fraction by your total taxable income. This is simpler than the three-factor formula some other states use, but it only applies if you meet the thresholds for singe-factor apportionment. There are situations where the Oklahoma Form 200 is simply the wrong tool. If you are filing as an S corporation, you do not use Form 200. S corporations in Oklahoma file Form 200S, which is an informational return where the income passes through to shareholders. If you are a partnership or LLC taxed as a partnership, you file Form 106 with Oklahoma. Getting the entity classification right matters because the penalties for filing the wrong form can be steep, and the Oklahoma Tax Commission has been known to assess administrative penalties for frivolous or incorrect filings.
Get the Full Details
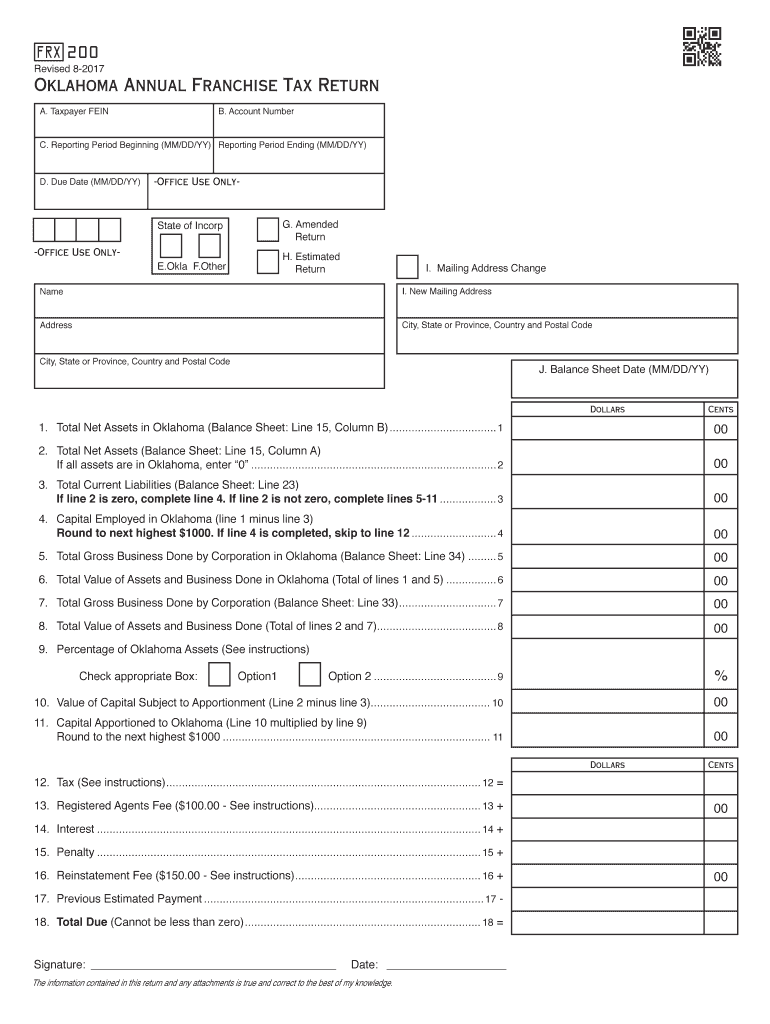
The filing deadline for Form 200 is the 15th day of the fourth month after the end of your tax year, which for calendar-year corporations means April 15. If that date falls on a weekend or holiday, the deadline shifts to the next business day. Extensions are available by filing Form 200EXT, which gives you an automatic six-month extension to file, taking the deadline to October 15. However, an extension to file is not an extension to pay. Any tax owed should still be paid by the original April 15 deadline to avoid interest charges, which accrue at the Oklahoma composite rate from the original due date until the date of payment. I have found that the most efficient way to handle Oklahoma Form 200 filing is to maintain a running reconciliation spreadsheet throughout the year rather than waiting until April to figure out what adjustments are needed. Track your addbacks and subtractions month by month, reconcile them against your federal return as you finalize each quarter's numbers, and flag any credit carryforwards or limitation issues well in advance. This approach reduces the actual preparation time for the return to roughly two to three hours for a standard corporation with a straightforward operations structure, compared to six or seven hours if you are starting from scratch at filing time. The Oklahoma Tax Commission also offers an electronic filing option through their myOCREWS system, which is the online portal for business tax filings. E-filing is faster, provides immediate acknowledgment of receipt, and reduces the chance of errors from handwritten entries. Paper filings are still accepted, but they take longer to process and leave more room for clerical mistakes. If your corporation has a complex multistate presence or significant credit carryforwards, electronic filing is the safer choice simply because the system validates certain fields before acceptance.