Working Through Oksendal Without Losing Your Mind
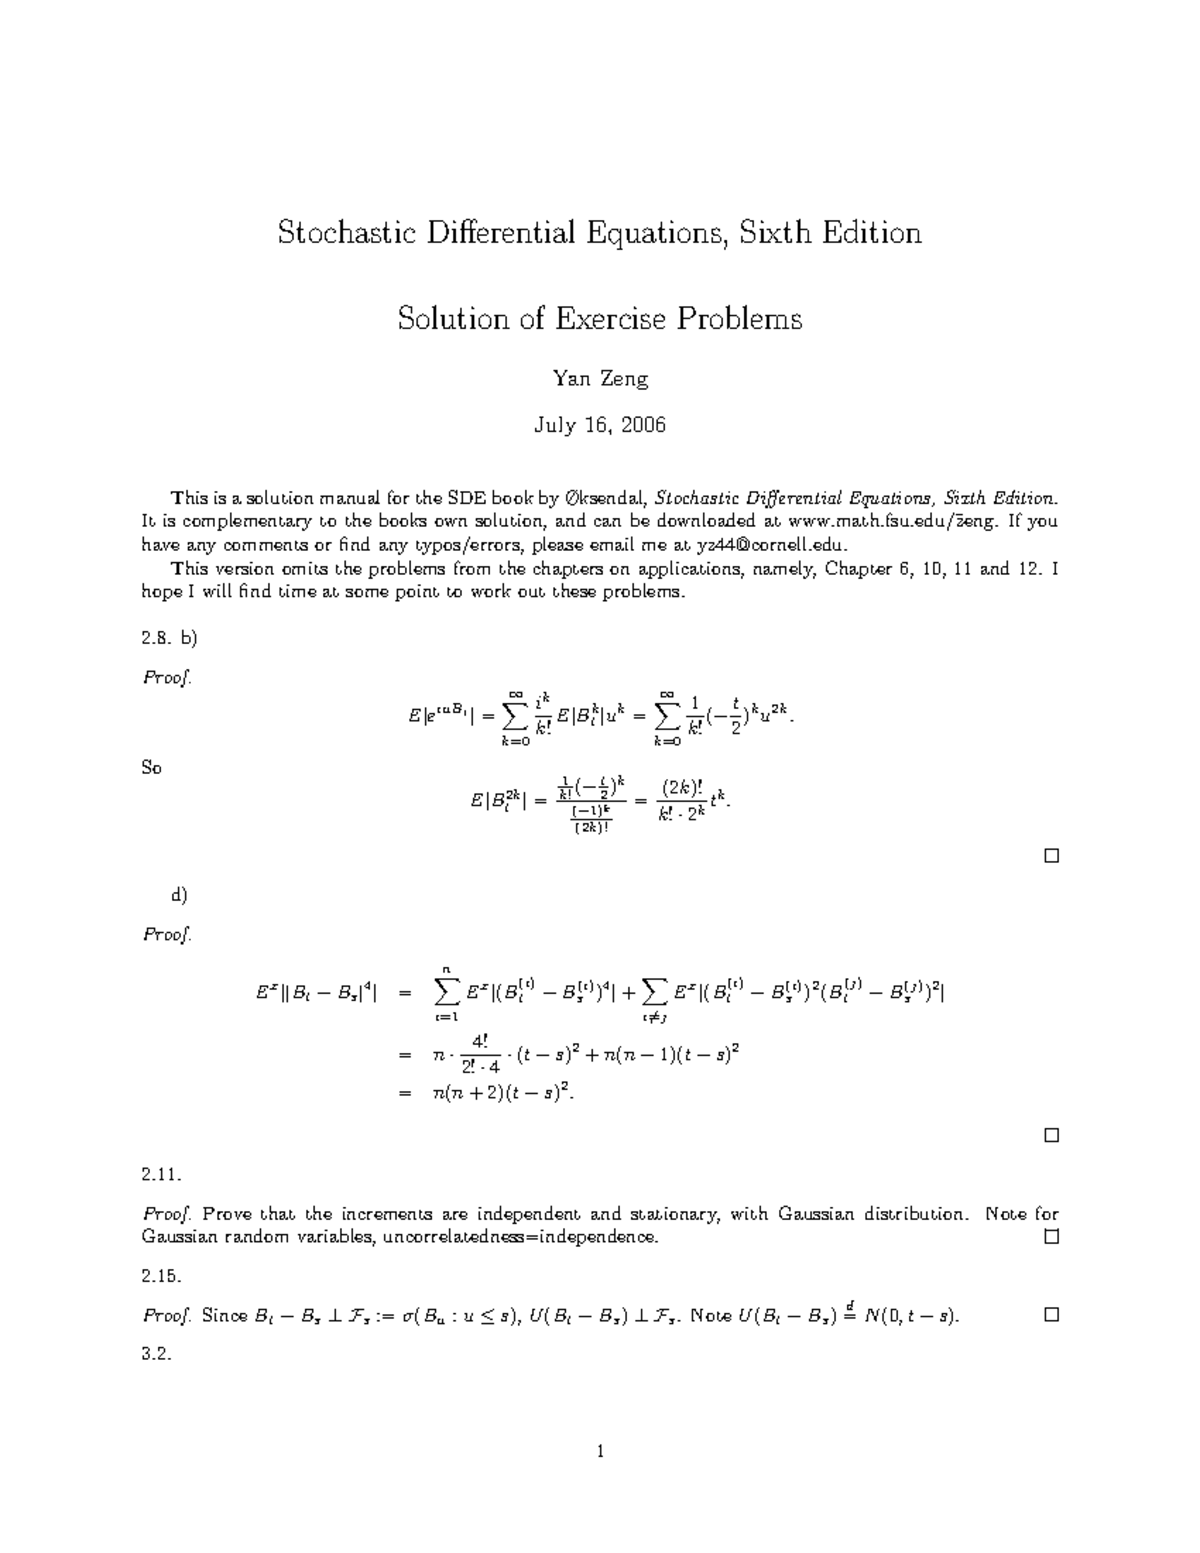
If you are studying stochastic calculus at the graduate level, you will almost certainly run into Oksendal's textbook. The problems at the end of each chapter are where the real learning happens, and they are not trivial. I spent years grading student work on these exercises and helping researchers apply the material, so I have seen every mistake people make when they try to work through them alone. The Oksendal Stochastic Differential Equations Solutions Manual is not a single universally published book. That is the first thing you need to understand. The textbook itself, published by Springer, does not come with an official comprehensive solution guide for every exercise. What exists are student-created PDFs circulated through university repositories, unofficial compilation websites, and occasionally lecture notes from professors who have assigned the text. The quality varies enormously between them. I learned this the hard way during my first year as a teaching assistant. I handed students an unofficial solution set I found online for Chapter 5 problems on Ito integrals. Two students later pointed out that the solution to Problem 5.3 had a sign error in the integration by parts step that propagated through the final answer. The rest of the chapter looked fine, but that one mistake was subtle enough that anyone checking their work without deriving the solution independently would never catch it. I stopped distributing any unverified solution sets after that.
How to Actually Use a Solutions Manual for This Book
The most effective approach is to attempt every problem yourself before consulting any solution. Write out the full derivation on paper. Only then open the manual and compare your steps, not just your final answer. The value is in catching where your application of Ito's lemma diverged from the standard approach, not in confirming that your result matches. When you find a discrepancy between your work and the manual, resist the temptation to assume the manual is wrong immediately. The most common error I see is students making a sign mistake or dropping a factor of 1/2 in a Taylor expansion, then spending ten minutes convinced the published solution is incorrect. Verify your own arithmetic first. Recalculate the second derivative term in Ito's formula explicitly. Check whether you applied the correct diffusion coefficient. For geometric Brownian motion problems specifically, pay attention to whether the manual uses the Stratonovich or Ito interpretation. Oksendal works exclusively in the Ito framework, but some unofficial solution sets pull methods from other textbooks that use Stratonovich calculus, and the conversion between them introduces an extra drift term that a careless reader will miss. I found two different manuals online that gave different answers for the same expected value problem because one implicitly converted between frameworks and the other did not.
Common Pitfalls in the Earlier Chapters
Chapters 1 through 3 cover the probability theory foundation, martingales, and the basic construction of the Ito integral. Students tend to rush through these sections because the calculations look familiar from standard real analysis courses. That is a mistake. The subtlety in stochastic calculus lives entirely in how measure-theoretic concepts apply to processes rather than static random variables. If your understanding of convergence in L2 is shaky, you will struggle enormously with Chapter 4 when the actual SDE theory begins. One specific concept that trips people up repeatedly is the distinction between adapted processes and predictable processes. Oksendal defines the Ito integral for adapted processes satisfying an integrability condition, but several of the later problems implicitly require you to verify predictability when applying representation theorems. I have seen students skip this verification and write down results that look correct until a careful reader checks the measurability assumptions. Another issue appears in the Feynman-Kac section. The connection between parabolic PDEs and expectation representations over diffusion processes is powerful, but students frequently misidentify which boundary conditions correspond to which stopping times. When the domain is unbounded or the coefficients grow faster than linearly, the standard Feynman-Kac theorem does not apply without additional growth restrictions on the solution. A few unofficial solution sets I encountered glossed over these technical conditions entirely and presented formulas as universally valid.
Get the Full Details
What the Manual Cannot Replace
No solutions manual, official or otherwise, will teach you to handle pathological cases. There are SDEs with coefficients that violate the Lipschitz condition yet still admit weak solutions, and there are cases where strong uniqueness fails while weak uniqueness holds. These edge cases appear in advanced problem sets and in research applications, and no standard solutions manual covers them adequately. If you are working on something beyond the textbook exercises, you need to go to the primary literature directly. Ikeda and Watanabe remains the definitive reference for existence and uniqueness questions that go beyond Oksendal's treatment. Yamada and Watanabe's 1971 paper on strong solutions is short enough to read in an afternoon and clarifies several assumptions that Oksendal states without full justification. Matsusaka's work on weak solutions fills additional gaps. These are not optional reads if you plan to use stochastic differential equations in actual research. For numerical methods, which appear in later chapters and in many applied contexts, the Euler-Maruyama scheme is standard but often insufficient. The Milstein scheme adds a correction term involving the derivative of the diffusion coefficient, and it converges strongly with order 0.5 instead of the Euler method's inferior practical performance. Several homework problems reference this without deriving it, and students who skip the derivation end up confused when their simulation results do not match theoretical expectations.
Finding Reliable Solutions
If you need an Oksendal Stochastic Differential Equations Solutions Manual, start with your course instructor. Many professors maintain solution sets for assigned problems and distribute them through official course portals. These are always more reliable than anything found on file-sharing sites. If your course does not provide solutions, check whether the department has archive copies from previous semesters. Mathematics departments often keep these materials accessible for current students. University library databases sometimes contain graduate student theses that work through substantial portions of Oksendal as supplementary material. These tend to be more detailed and more carefully checked than anonymous PDFs posted online. A search through ProQuest or your institution's digital repository using keywords like "stochastic differential equations exercises" and "Ito calculus problems" can surface relevant documents. When using any solution resource, cross-reference at least two independent sources whenever possible. If two manuals disagree on a problem, derive the solution yourself and determine which one is correct. This process is slower than simply copying an answer, but it is the only method that actually builds competence in stochastic calculus.
A Practical Workflow That Works
Work in focused blocks of about forty-five minutes on a single problem before switching topics. Stochastic calculus requires holding multiple layers of notation in your head simultaneously, and constant context switching increases error rates significantly. Keep a running list of which problems you could not complete and revisit them the next day with fresh notation on a clean sheet of paper. Many students resolve a stubborn problem this way simply because their initial attempt contained a notational confusion that became invisible through repeated re-reading of the same page. Form a small study group if you can find two or three other people working through the same material. Explaining your derivation to someone else forces you to confront gaps in your reasoning that you would otherwise overlook. I found that the students who struggled most were not those who worked alone, but those who worked alone and never verified their results against an external source. The material is dense but coherent once you stop treating each chapter as a separate subject. Martingale theory, Ito integration, and SDE existence proofs are all connected through the same underlying measure-theoretic structure. When you see those connections explicitly, the problem sets become much more manageable and the solutions manuals serve their intended purpose rather than becoming a crutch.