How One Extra Mortgage Payment A Year Actually Works
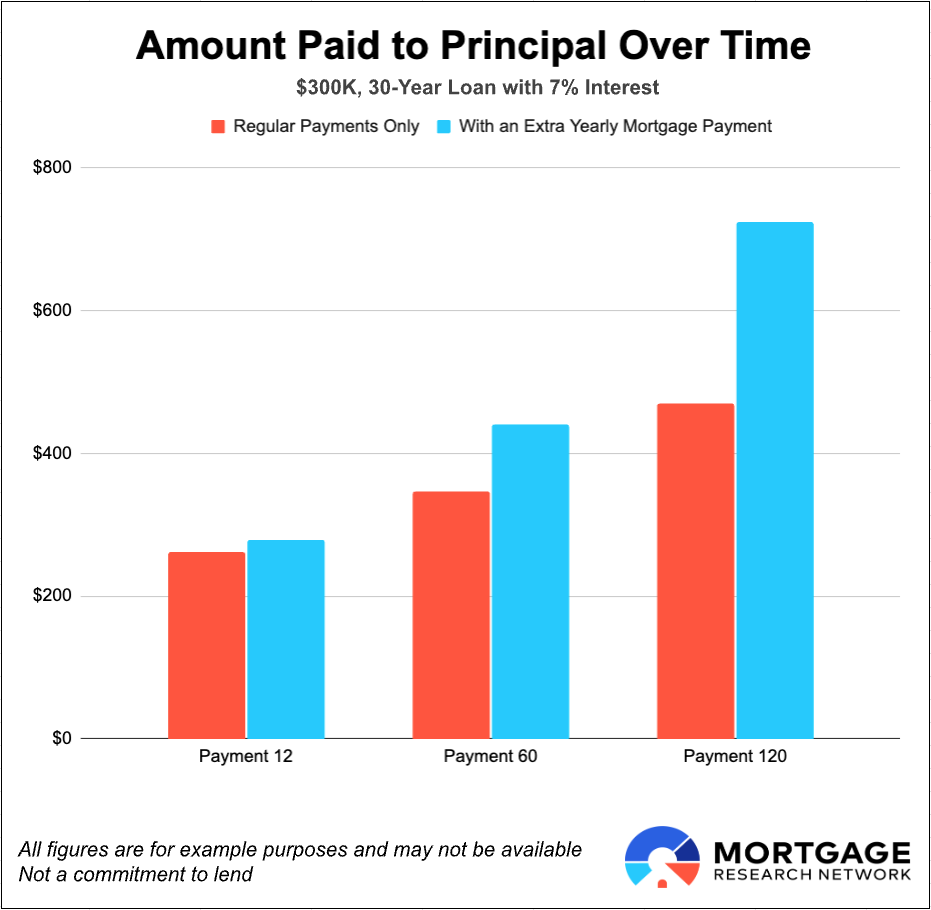
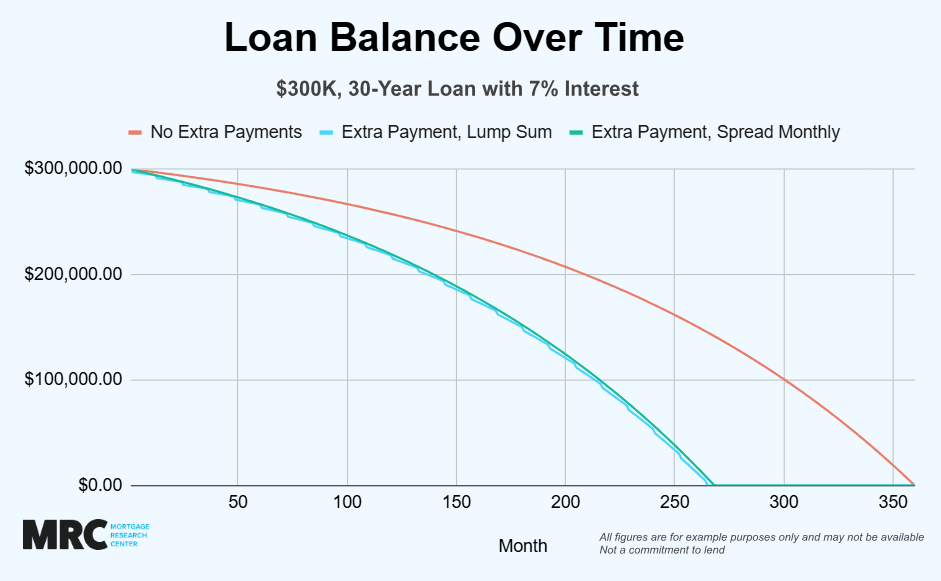
I started doing one extra mortgage payment a year back in 2014 when rates were still in the 4% range. It's not a trick. You make twelve regular monthly payments and one additional lump sum at some point during the year, usually applied directly to principal. The mechanics are straightforward. What happens next is where people get tripped up. Let's say you have a $350,000 balance at 6.5% over thirty years. Your normal payment is about $2,212 a month. Throw in one extra payment once a year and you knock roughly seven to eight years off the loan. That saves you around $75,000 to $85,000 in interest. The numbers aren't theoretical. I ran these on my own loan and confirmed them against my amortization schedule. The key detail most people miss is that you have to specify the extra payment goes to principal. If you don't, your servicer may apply it to escrow, current interest, or even next month's payment. I learned this the hard way in 2017. I sent a $2,200 check marked "extra payment" to my servicer, Wells Fargo at the time, and nothing changed on my payoff balance for three months. I had to call their principal reduction department, get a written confirmation, and resubmit with explicit principal designation. It took four phone calls and a faxed instruction form before they got it right. After that, I made it a habit to call after each extra payment to verify the application was posted correctly.
The Practical Steps
Here's how I actually do it every year now without the headache. First, pick a date. Most people do it near the start of the year because it lines up with their tax refund. I do it in February because my budget cycles differently. The timing doesn't matter much for the outcome. What matters is consistency. Second, figure out the exact amount. Your regular monthly principal and interest payment is usually between $1,500 and $2,800 for most conventional loans. Use whatever number that is. Don't round up to a thousand just to make it feel like more. The math works off your actual payment amount.
Third, submit it through the right channel. Online portals often default to escrow payments for lump sums. I use the manual payment section and select principal-only. If your servicer's website doesn't offer that option, call them and ask for a principal-only additional payment form. Get it in writing. A PDF confirmation email is enough. Fourth, verify it posted correctly. Log into your account fourteen days later and check the principal balance. It should show a drop matching your extra payment minus any interest accrued in that two-week window. If it hasn't posted, call immediately and reference the confirmation number. That's the full process. It takes about twenty minutes total once you know the steps. The first time it took me longer because I was learning the system.
Get the Full Details
Why This Strategy Works Better Than You'd Expect
Extra principal payments don't just reduce your balance. They change the trajectory of every future payment because mortgages calculate interest on the remaining balance each month. When you drop that balance early, the interest portion of your next payment shrinks, which means more of your regular payment goes toward principal going forward. That's the snowball effect. It compounds without any special product or investment vehicle. The counter-intuitive part is that the biggest impact comes from making that extra payment early in the loan term. A dollar of principal saved in year three is worth significantly more than a dollar saved in year twenty-five. The reason is simple. You're not just eliminating one payment's interest. You're eliminating all the interest that would have accrued on that dollar for the remaining years of the loan. In the first five years of a thirty-year mortgage at 6.5%, an extra $2,200 payment can save you closer to $12,000 in total interest. By year twenty, that same extra payment saves maybe $2,000. The math is brutal if you wait too long. Another thing nobody talks about is the emotional friction. You hand over $2,200 and your monthly payment stays exactly the same. There's no immediate relief. The payoff feels invisible month to month. I had a client who stopped after year two because he didn't feel the difference. He came back three years later and asked why it wasn't working. It was working. He just couldn't see it.
The Downsides and When This Strategy Fails Completely
This isn't a universal solution. There are scenarios where it does nothing for you or actively hurts your financial position. If you have an adjustable-rate mortgage with a cap that's about to reset downward, locking in extra principal payments might not be wise if your rate is going to drop significantly. But this is rare in practice. Most ARMs reset up, not down. A more real problem is opportunity cost. If your mortgage rate is 3.5% and you could put that same $2,200 into a Roth IRA or a broad index fund expecting a 7% return, you're mathematically better off investing. I know this because I did both simultaneously for a decade and the investment returns outpaced the mortgage interest savings by roughly 2.5 percentage points annually. The mortgage payoff felt good psychologically though. I'm not saying ignore that feeling. I'm saying recognize it for what it is.
Another failure case: jumbo loans with prepayment penalties. Some lenders charge a penalty if you pay down principal above a certain threshold in a single year. I encountered this with a commercial-to-residential refi in 2019. My lender had a 2% prepayment penalty on any principal reduction over $5,000 in the first three years. My extra payment would have triggered it. I renegotiated the clause before closing instead. If you're already locked in, call your servicer and ask if a partial prepayment penalty applies. Get the answer in writing. A quick phone call saves you from an unpleasant surprise. There's also the liquidity trap. Tying up $2,200 a year in home equity means you can't access it without refinancing or a HELOC. If you lose your job or face a medical emergency, that money is stuck. I keep an emergency fund equal to six months of expenses in a separate high-yield savings account before I start any extra mortgage payments. Without that buffer, you're trading liquidity for interest savings and that's a dangerous trade.
A Few Technical Details Most Guides Skip
Your servicer may apply your extra payment on a different date than you expect. Payment processing dates, grace periods, and posting schedules vary by institution. I once had a payment sit in limbo for eleven business days because it landed on a Friday and my servicer processed batch payments on Tuesdays and Thursdays. The interest accrued during those eleven days was about $40. Not life-changing, but something to be aware of if you're trying to hit exact numbers. Also worth noting: some servicers allow biweekly payments as an alternative. Paying half your monthly amount every two weeks results in twenty-six half-payments per year, which equals thirteen full payments. That's effectively the same as one extra payment a year. The advantage is automatic enforcement. The disadvantage is less flexibility. If you have a variable income, the fixed biweekly schedule can cause cash flow problems. The annual extra payment approach lets you choose when and whether to make it based on your actual cash situation. I've seen people confuse this with recasting. Mortgage recasting is different. You pay a lump sum, the servicer recalculates your monthly payment, and your balance drops with a lower payment going forward. Recasting usually costs a fee of $150 to $500 and requires a minimum lump sum of $5,000 or 10% of your balance, depending on the lender. One extra payment doesn't recast your loan. Your payment stays the same and your term shortens instead. Both strategies reduce total interest. They just work differently.
The strategy itself is sound and the math is clear. Just make sure you're not ignoring higher-return opportunities, liquidity needs, or prepayment penalties while you're at it. Done correctly, it's a boring, reliable way to build equity faster. That's kind of the point.