How the One Extra Mortgage Payment Per Year Strategy Actually Works
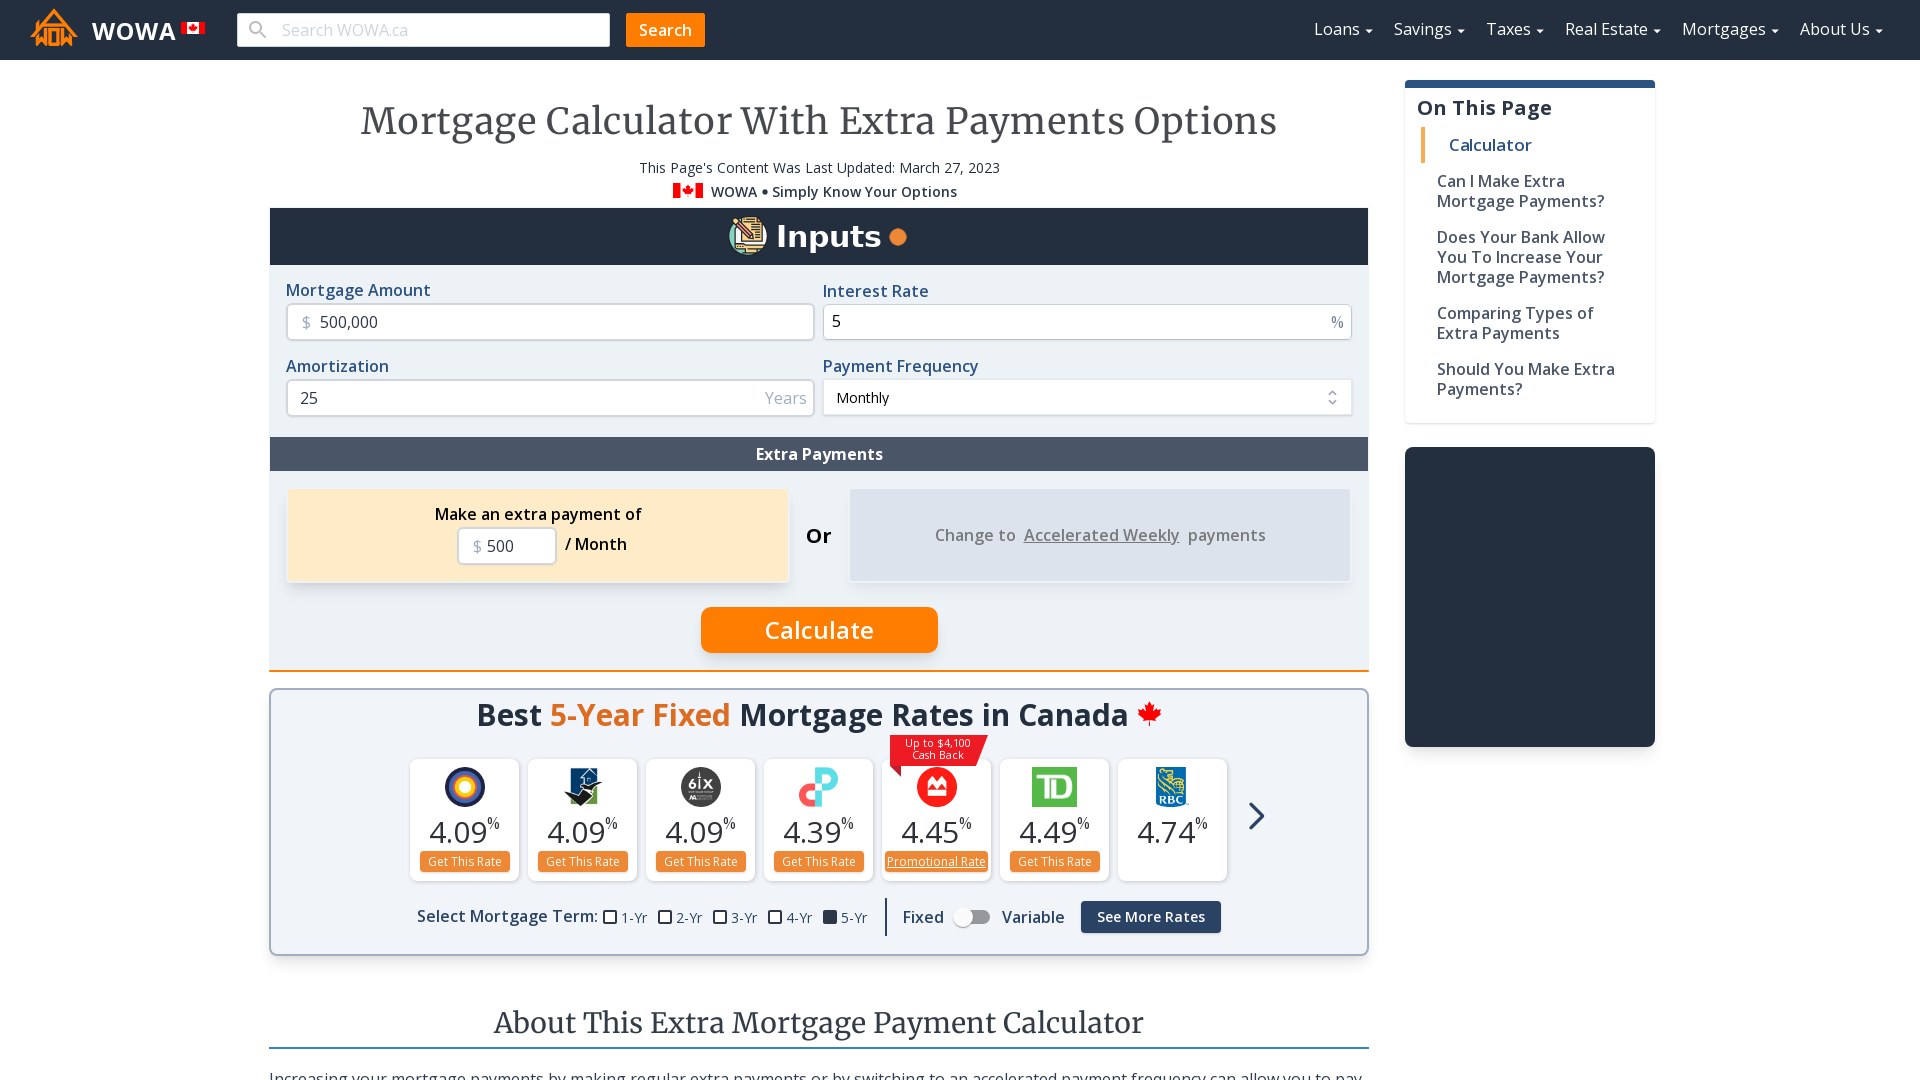
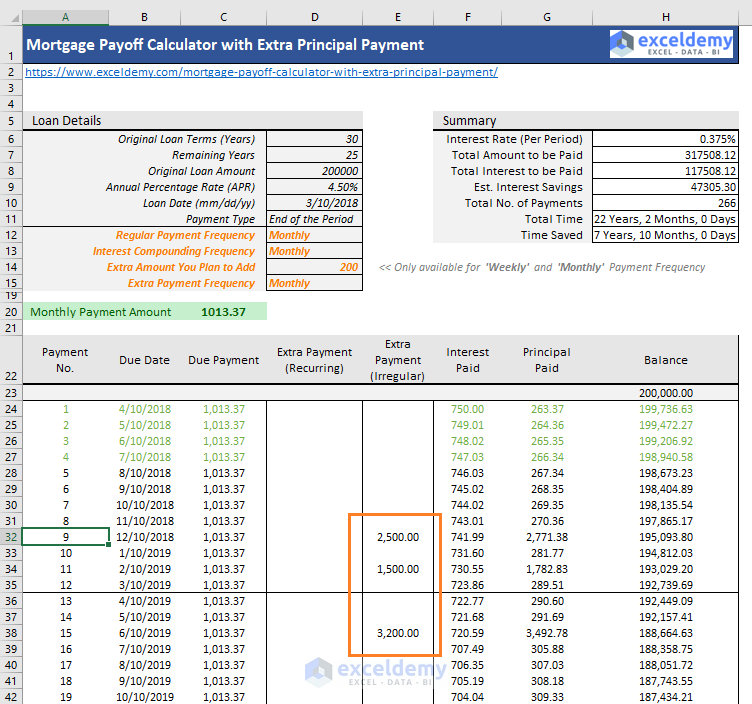
The basic premise is simple enough that anyone with a bank account can grasp it. You pay one additional full mortgage payment each year, applied directly to your principal balance. That single extra payment compounds over time, shaving years off your loan term and thousands off total interest paid. What most people don't realize is that the mechanics of how that payment gets applied matter far more than the strategy itself. These tools take your current loan balance, interest rate, remaining term, and monthly payment, then project what happens when you slip in one extra payment annually. The output tells you how many months you save and how much interest you eliminate. I built a simple spreadsheet for my own use back when I was helping clients run these projections for refinancing decisions, and I've stuck with it since. The commercial versions online are fine, but they rarely account for the messy details that actually show up on your statement. The formula these calculators use is standard amortization logic. Your regular payment each month covers interest first, then principal. When you add an extra payment, it bypasses the interest queue entirely and reduces the principal balance directly. A lower principal means less interest accrues the following month, which creates a ripple effect through the rest of your loan. That's why the savings accelerate toward the end rather than spreading evenly across the loan life.
Here's a practical example. Say you have a $300,000 mortgage at 6.5% over 30 years. Your monthly payment comes to about $1,896. If you make one extra payment every January, the calculator will show you save roughly 4.2 years and around $31,000 in interest. The numbers shift depending on where you are in the loan though. Starting at year one produces the maximum benefit. Starting at year twenty barely moves the needle because most of your early payments already covered the cheap interest. The amortization schedule doesn't care about your intentions. I ran into a specific problem last year when a client sent me her one extra mortgage payment per year calculator results showing dramatic savings, but her actual statements told a different story. The gap came down to how her servicer handled the extra payment. She was paying through an online portal that defaulted the extra amount into an escrow account instead of applying it to principal. The calculator assumed proper application. Her servicing department did not. I had her call them and set up a principal-only suppression override, which is the technical term for ensuring future one-time payments route to principal without touching escrow. It took three phone calls and exactly forty minutes of hold time. After that, the calculator projections matched her real results within a two-month variance. This is the part nobody puts in the marketing materials. Your mortgage servicer may not automatically apply extra payments to principal the way you expect. Some companies will apply them pro-rata between interest and principal. Others will stash them in a suspense account until your next regular payment date. You need to verify this explicitly, not assume it. Call your servicer and ask whether a separate one-time payment gets applied principal-first by default or whether you need to flag it. The answer determines whether your calculator numbers are even close to accurate.
There are also edge cases where this strategy underperforms or fails entirely. If you have an adjustable-rate mortgage with a rate cap, making extra principal payments might not help if your rate resets higher and resets the effective interest burden upward. The calculator won't factor in rate resets because it runs on static assumptions. Same issue with loans that have prepayment penalties. Some mortgages charge a fee if you pay down principal faster than a certain threshold within the first three to five years. That penalty can wipe out most of the interest savings the extra payment generates. Check your note for a prepayment clause before you commit. Another common blind spot is the tax implication. Mortgage interest deductions on Schedule A only apply to qualified interest, and reducing your principal balance faster reduces the interest you can deduct each year. If you itemize and this deduction matters to your tax situation, the after-tax cost of your mortgage is lower than the stated rate. A 6.5% mortgage in the 24% bracket is closer to 4.94% on an after-tax basis. Run the calculator with your marginal tax rate factored in if you want the real picture. Most online versions don't offer that input field. The strategy also breaks down if your cash flow is irregular. The model assumes you can reliably produce one extra payment every twelve months. If you're living paycheck to paycheck or running a business with seasonal income, you'll miss the window some years and the compounding effect stalls. I'd rather see someone make one extra payment every other year consistently than try to do it annually and bail out after nine months. Consistency beats intensity here.
Get the Full Details

For the best results, time your extra payment to coincide with a month where your principal portion is already starting to dominate. That typically happens later in the loan term, but the math gets less compelling at that point. There's a tension you have to accept: earlier payments save more interest but require more discipline when the loan is new and your balance hasn't budged yet. Later payments are easier psychologically but the savings diminish rapidly. Most people don't stick with it long enough to see the real acceleration happen. If you want a free tool that handles the core calculation without selling you anything, there are several solid options out there. The Bureau of Consumer Financial Protection maintains a mortgage calculator that lets you adjust for additional payments. Bankrate and NerdWallet both have versions with principal prepayment sliders. None of them are perfect, but they cover the basics adequately. For anything beyond a standard fixed-rate conforming loan, you should probably just build your own spreadsheet or work with a fee-only advisor who can model your specific loan terms. One thing worth noting is that the one extra payment per year approach is mathematically identical to increasing your monthly payment by roughly 8.3%. Dividing twelve months by thirteen payment periods gives you that fraction. Some people prefer the psychological win of seeing one big payment hit principal at once rather than a slightly larger amount deducted from every monthly check. Both produce the same result. Pick whichever behavior you can sustain without stress.
The numbers work in your favor if your loan is still early and you can commit to the habit. They work less well if your rate is already low and your balance is small, or if your servicer is going to misapply the payment without you noticing. Verify the application method first. Then run the numbers through a calculator. Then commit to the schedule. Skipping the verification step is the most common mistake I see, and it's the one that costs people the most over time.