Getting Started With Optimal Blue
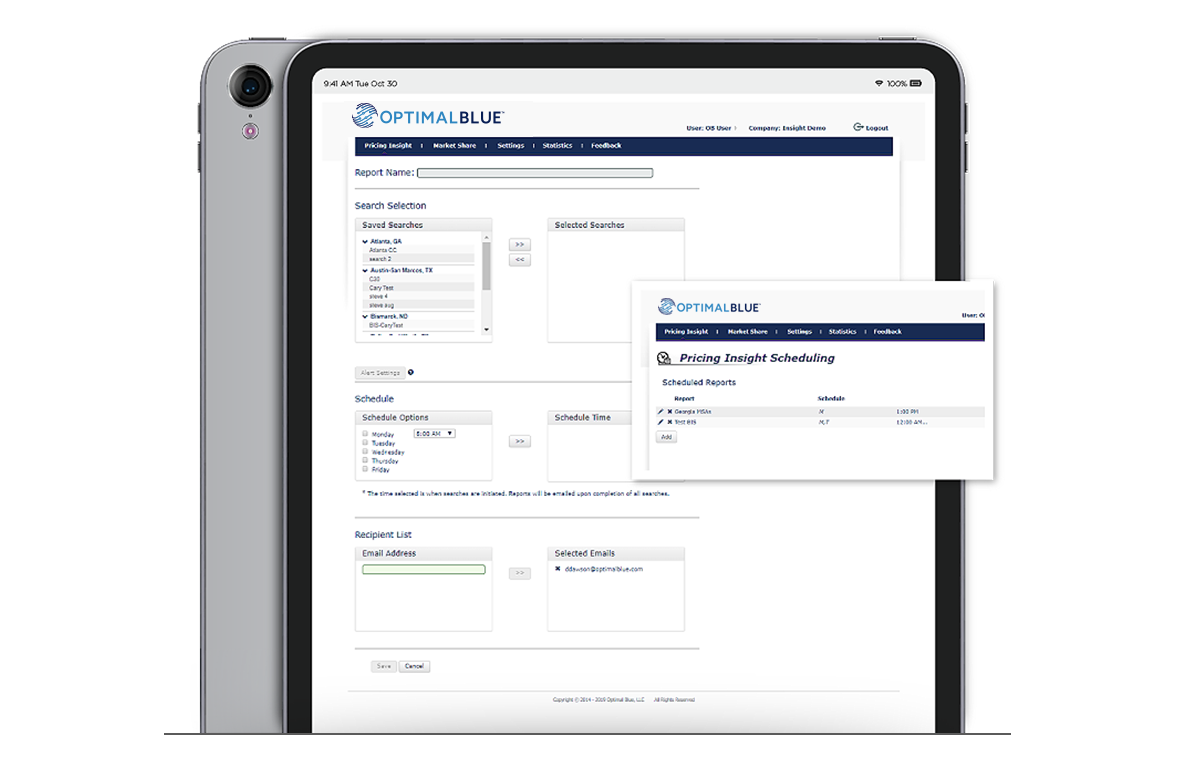
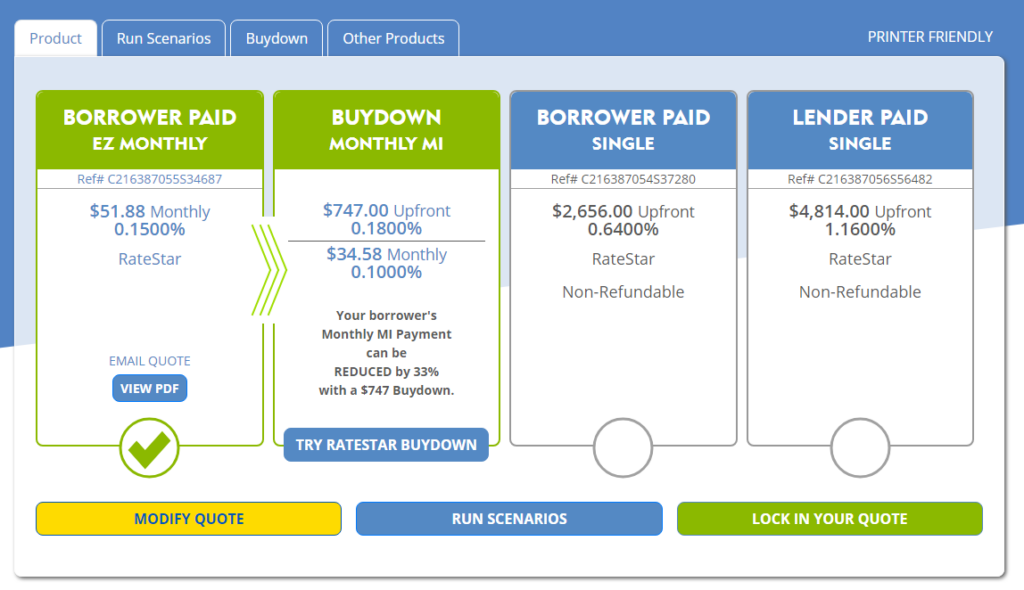
If you are an insurance agent or broker looking to quote health plans efficiently, Optimal Blue is one of the platforms you will encounter most often. It is a marketplace aggregator that pulls from multiple carriers and lets you compare plans side by side. The interface is functional. It is not the prettiest thing you will ever use, but it does what it says. The core workflow is straightforward: enter the zip code, client age, tobacco status, coverage level preferences, and then run quotes. Results populate with premiums, deductibles, provider networks, and formulary tiers. You can save comparisons, generate certificates of coverage, and submit applications directly through the platform. For agents who quote high volumes, this centralization saves time compared to logging into individual carrier portals one by one.
Optimal Blue User Guide
Here is how the process actually works in practice, beyond what the marketing materials say. After you log in, the first decision point is whether you are running quotes for Medicare Advantage, Medicare Supplement, Part D, or individual marketplace plans. These are separate tools within the same dashboard, and the data fields shift depending on which track you select. Do not skip setting the correct plan year and product type early. I wasted about twenty minutes once because I had the wrong Medicare product selected and the entire results set was irrelevant. The platform does not warn you when your filters are misaligned. When you pull quotes, pay attention to the carrier mix. Optimal Blue aggregates from dozens of carriers, but availability changes by county and by year. Some carriers drop out between renewal seasons. If you built a client relationship around a specific insurer and they leave the platform, you need to know before you present options. I learned this the hard way during a 2024 renewal cycle when a mid-tier carrier exited the platform unexpectedly. My clients were comparing plans based on outdated information. The workaround was to cross-reference each carrier's current participation status directly on the carrier's own website before finalizing any recommendations. It adds about five minutes per quote run, but it prevents embarrassing situations. The certification and application module is where things get slightly complicated. You can generate certificates of coverage with one click, which is genuinely useful when you need to mail documents to clients. The application submission process works for most standard cases, but there are edge cases. If a client has a pre-existing condition that requires medical underwriting, or if you are dealing with a complex Medicare Special Needs Plan, the automated application flow may not capture all the necessary details. In those situations, I fall back to carrier-specific portals or paper applications. Optimal Blue handles the bulk of routine quoting well, but it is not a universal replacement for direct carrier systems.
One thing beginners miss is how the provider network search works. The network lookup is decent for major metropolitan areas, but in rural counties the data can be sparse or outdated. I have seen cases where a hospital system was listed as in-network on Optimal Blue but had actually left a plan's network six months prior. Always verify network participation directly with the provider's billing office when it matters. The platform gives you a starting point, not a guarantee. The reporting side is another area where the platform shows its real value. You can export quote data, track client interactions, and generate production summaries. The export format is CSV, which means you can manipulate it in Excel or import it into your CRM. Agents who do not use the reporting features are leaving productivity gains on the table. A well-organized export can cut your end-of-month administrative work from two hours down to roughly fifteen minutes. There are also some less obvious features worth knowing. The platform allows you to set default preferences for your office, so you do not have to reconfigure the same filters for every quote run. You can create client profiles that auto-populate basic information. There is a notes field attached to each quote, which is useful for tracking client conversations without switching between tabs. These small details add up over hundreds of quotes per year.
Get the Full Details

Customer support is available through phone and chat, but response times vary. During open enrollment periods, expect delays. I typically bookmark the help documentation and check the knowledge base before reaching out. Most common issues have already been addressed there. The support team is competent when they get to you, but patience is required during peak seasons. The pricing model for agents is generally commission-based, meaning you do not pay a subscription fee to use the quoting tools. You earn commissions through placed business. This is standard for the industry. However, the application and certification tools may have different access requirements depending on your licensing and accreditation status. Make sure your account is fully verified before you rely on the platform for critical submissions. I have seen agents hit dead ends mid-quote because their accreditation was incomplete. Ultimately, Optimal Blue is a solid quoting and comparison tool for insurance agents. It is not flawless, and it will not replace every carrier portal you need. But for day-to-day quote generation, plan comparison, and basic application workflows, it covers most needs efficiently. The key is understanding its limitations and building verification habits around network data, carrier participation, and complex client scenarios. Treat it as a first step, not the final word.