Reading the Tape Before the Close
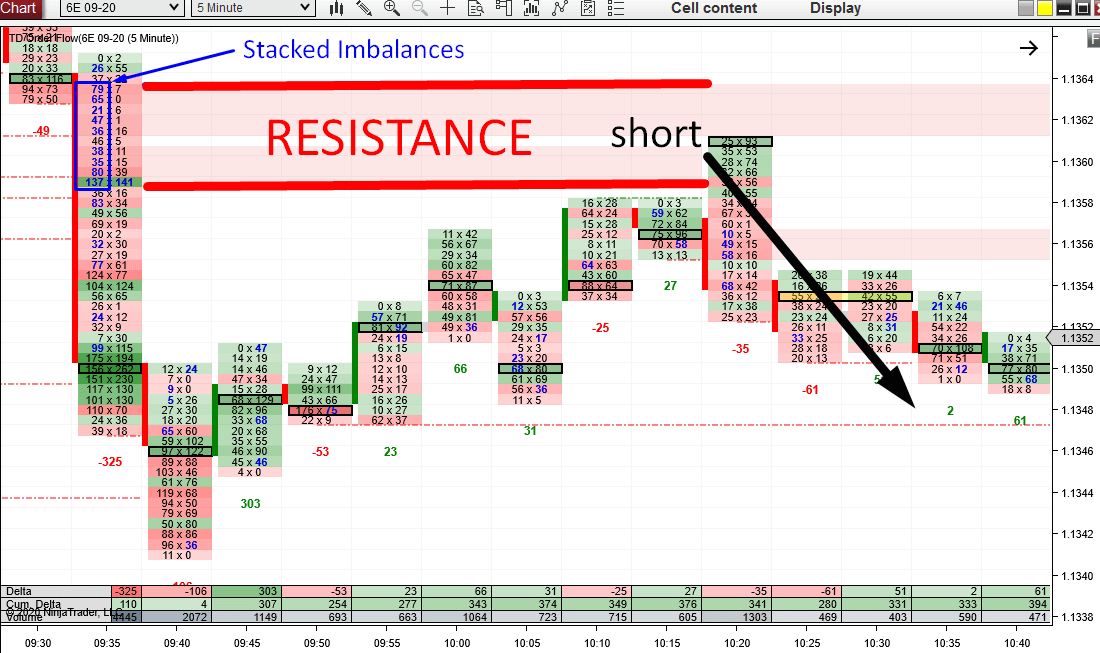
I used to obsess over order imbalance strategies the way most retail traders obsess over moving average crossovers. That changed after I blew through three accounts in two years trying to trade pre-market prints I didn't fully understand. The strategy itself isn't complicated, but the execution requires you to think about what's actually happening inside the exchange, not just what the Level 2 screen shows you. Order imbalance happens when there's a meaningful disparity between buy and sell orders at a specific price level during the call auction phase before market open or at scheduled points during the day. Exchanges like NASDAQ and NYSE publish these imbalances at regular intervals. The core idea is simple: if there's significantly more buying interest than selling interest at a given price, the opening print should be pushed higher to clear the queue. In practice, it's nowhere near this clean.
The Order Imbalance Trading Strategy Explained
The standard approach involves tracking the imbalance ratios published by exchanges during the pre-market call period. You're looking for imbalances where the buy-side or sell-side quantity exceeds the other by roughly three to one or more. A 3:1 ratio or higher is generally considered significant. When you see that, you're betting the indicative equilibrium price will move toward the side with more pressure. Here's the part nobody tells you in the beginner guides: the published imbalance numbers are stale the moment you see them. The exchange updates them every 10 to 15 seconds, but by the time your data feed delivers the snapshot and your eyes register it, the queue has already shifted. I learned this the hard way in 2022 when I was trading SPX Imbalance data. The strategy would show a massive buy-side imbalance on a tech stock at 9:28 AM, I'd pull the trigger on a long position at around 9:30, and the stock would open flat or slightly down. The imbalance had flipped between the moment I saw it and the actual auction. The workaround was to only take trades when the imbalance had been consistent across at least three consecutive snapshots. If the same side was stacked up three times in a row, I'd enter. Single spikes? Ignore them. They're mostly noise or algorithmic positioning that gets torn down before the bell. The timeframe matters too. Most imbalances you care about show up between 9:00 and 9:29 AM ET on the NASDAQ. After that, the exchange stops publishing them in the same format because the auction mechanics shift. Some brokers and data providers continue to display imbalance-like data during regular trading hours, but those aren't the official call auction imbalances and they work differently.
You also need to understand what the imbalance number actually represents. It's not the total volume sitting on the books. It's the quantity of shares at the indicative price that cannot be executed because there aren't enough counterparties on the other side. A buy imbalance of 5 million shares doesn't mean 5 million buyers are waiting. It means that at the current indicative price, there are 5 million more buy orders than sell orders that could fill. The rest of the order book beyond that price level is a separate calculation entirely.
Get the Full Details

What Separates the People Who Make Money on This
Amateurs look at the raw imbalance number and trade it immediately. Professionals look at the imbalance relative to average daily volume, relative to the stock's typical pre-market range, and relative to the implied move from futures and options pricing. A 10 million share buy imbalance on a micro-cap with a 200,000 share average daily volume is a screaming signal. The same imbalance on Apple is background noise. The market doesn't care about absolute numbers. It cares about context. Another thing that trips people up is that large imbalances don't always predict directional moves in the expected direction. Sometimes a huge buy-side imbalance results in a lower open. This happens when the imbalance is driven by institutional block orders that aren't actually aggressive. A fund might submit a massive buy order at the opening auction price because they need to fill a specific allocation target, not because they're calling the direction. Market makers and automated liquidity providers see that block order inflating the buy side, adjust their quotes accordingly, and the actual price discovery goes the other way. I ran into this repeatedly with certain ETFs during rebalancing weeks. The SPY imbalance data would show ridiculous buy-side stacks on certain component stocks, but the opens would consistently gap down because the real selling pressure was hiding in the dark pools and not reflected in the published imbalance figures. You should also factor in what happens after the open. Imbalance strategies are typically intraday plays with a very narrow window. If you hold past the first 15 minutes, you're no longer trading the imbalance. You're trading the stock on its own merit, which is a completely different decision framework. I used to hold positions for an hour or two hoping the imbalance thesis would play out over a longer timeframe. It never did. The edge decays within minutes, sometimes seconds.
The data source you use will determine whether this strategy is even feasible for you. Retail platforms like Thinkorswim or Webull show basic imbalance data, but the latency and completeness aren't sufficient for anything beyond casual observation. Professional traders use Cboe TotalView or direct exchange feeds. If you're serious about this, you need something that gives you the imbalance numbers with minimal delay and the historical context to backtest against. There are several commercial platforms that specialize in this data. I used TradeTech's X-Trade platform and earlier versions of TickStory for backtesting. The cost runs a few hundred dollars a month, which sounds steep until you calculate how many losing trades you'd avoid by having accurate data instead of guessing from a delayed retail feed.
Building a Practical Framework
Start with a watchlist of 50 to 100 liquid stocks. Anything below 1 million shares in average daily volume is going to give you false signals because the imbalance numbers get distorted by a single large order. Filter out earnings days. Imbalance data around earnings is almost useless because the normal auction dynamics are overridden by the information event itself. You want a clean environment where supply and demand are the only variables moving the price. Set up alerts for imbalances that exceed a threshold you define based on the stock's typical profile. For a large-cap name like Microsoft, you might only care about imbalances above 20 million shares. For a mid-cap, maybe 2 million is enough. The exact numbers depend on your backtesting, but the principle is the same: the signal has to be abnormal for that particular security, not just large in absolute terms. When an alert fires, check three things before entering. First, has the imbalance held steady across multiple snapshots? Second, is the overall market direction aligned or neutral? A massive buy-side imbalance on a stock when the S&P is gapping down 1% is a lot less compelling than when the index is flat. Third, is there any news on the stock? If there's a press release or analyst upgrade sitting behind the imbalance, you're not trading the imbalance anymore. You're trading the news, and the risk-reward profile is completely different.

The entry itself should be mechanical. Place a market order or a limit order within the spread at the open. Don't try to anticipate the exact opening price and place a limit order way out in the weeds hoping to get filled. You'll miss too many trades. The strategy relies on participation rate, not perfection on entry price. A slightly worse entry on a trade you actually take beats a perfect entry on a trade you didn't take because your limit was too far from the market. Exit discipline is where most people fail. Set a time-based exit and a price-based exit. If the trade hasn't moved in your favor within 15 minutes, close it. If it hits your stop or your target, close it. Do not move your stop loss further away because you believe in the imbalance anymore. The imbalance doesn't care about your belief. It updated five seconds ago and the picture is different now.
When This Strategy Doesn't Work
I need to be blunt about the limitations because most people writing about this don't bother. Order imbalance trading fails constantly. It fails on low-volume days when institutional participation is light. It fails during high-volatility periods like Fed announcements or major economic data releases. It fails on stocks with unusual options activity that skews the auction dynamics. It fails when exchange algorithms change their calculation methodology, which happens more often than retail traders realize. The NYSE changed how they compute and publish imbalances at least twice in the last five years, and each change broke a bunch of strategies that people had been running without knowing why. If you're not set up with proper data infrastructure and you're just glancing at your broker's imbalance numbers on a phone app, you're not trading a strategy. You're gambling with a fancy label. The people who make consistent money on this have co-located or near-co-located data feeds, automated screening tools, and the ability to execute in milliseconds, not minutes. For the average retail trader, the viable approach is more observational. Use the imbalance data to inform your pre-market analysis. Note which stocks have significant imbalances. Watch how they open. Learn the patterns. But don't expect to punch in and out of positions faster than the institutional players who built their entire operation around being first to react to these numbers. A more practical alternative for traders without institutional-grade infrastructure is to use the imbalance data as a directional bias rather than a trigger. If you see a sustained buy-side imbalance on a stock you already trade, lean slightly long on your normal setups. Don't create a special trade just because the imbalance said so. Fold it into your existing framework. The edge is thinner, but the risk is also thinner, and you're not trying to out-speed firms that spend millions on infrastructure you can't replicate.