Why overpayments happen and how to track them
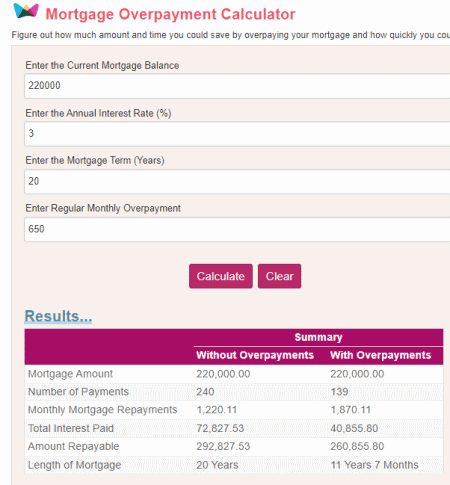
Overpayments show up everywhere — vendor invoices, payroll runs, subsidy distributions, loan disbursements. You send out more than the contract or agreement calls for, and the money sits somewhere between "we'll catch it" and "we won't bother recovering it." The reason I bother with an Overpayment Calculator is that most of these cases are buried in spreadsheets with no clear paper trail. You find them when someone asks for a reconciliation three months later and the numbers don't add up. The basic mechanics are straightforward. You take the amount actually paid, subtract the amount that should have been paid according to the governing document, and you're left with the overpayment. The trick is that "should have been paid" changes depending on the context. Vendor contracts might include volume discounts that weren't applied. Payroll might include overtime that wasn't authorized. Grant programs might allow indirect costs calculated at a rate that was superseded mid-fiscal-year.
How to use an Overpayment Calculator correctly
When I built my first proper calculator for this, I kept running into the same problem: the tool would flag an overpayment but not tell you whether it was recoverable. That distinction matters enormously. A vendor overpayment where the goods were delivered and accepted is legally and practically recoverable. An employee expense reimbursement that was slightly inflated due to a rounding difference on a per diem rate usually isn't worth the paperwork to chase. The calculator needs to separate signal from noise. Here's what the calculation itself looks like when you sit down to use one: Step 1: Pull the actual payment record — date, amount, reference number, payee. Step 2: Pull the contractual or authorized amount — this might be a line item on a purchase order, a salary band, a grant agreement, or a fee schedule. Step 3: Subtract authorized from actual. Step 4: Categorize by type — vendor, employee, grant, loan. Step 5: Flag based on thresholds. Anything under a certain dollar amount or percentage gets marked for review rather than automatic recovery.
I learned the hard way that step two is where everything falls apart. The authorized amount isn't always a single number. Sometimes it's a formula. Sometimes it's tiered. I spent two weeks reconciling a vendor overpayment only to realize the contract had a escalation clause that adjusted the base price based on a commodity index. The invoice used the old index value. The calculator flagged it as an overpayment. It wasn't. We were actually underpaying. That cost us a supplier relationship and three weeks of corrective entries. The workaround I use now is to attach the source document directly to each calculation entry. Not a summary line. Not a note saying "see PO." The actual PDF or scan of the relevant page, stored in the same folder structure as the calculator output. It takes ten extra seconds per entry and saves hours during audit season.
Get the Full Details
Edge cases that break most calculators
Partial payments are the most common failure point. You pay half of an invoice, then the vendor adjusts the price and sends a revised invoice. The second payment covers the adjustment but the calculator still thinks the original amount was the authorized baseline. I've seen this in accounts payable software where the system holds the original PO amount in a lockbox field and never updates it when amendments go through. The fix is to force a recalculation trigger on every PO amendment, not just on the payment side. Cross-period overpayments are another trap. You overpay in Q1, discover it in Q3, and try to offset it against a Q3 invoice. The calculator might show the net position as zero and write it off. But if your accounting treats Q1 and Q3 differently — say, one is budgeted and the other isn't — you've just moved a problem from one bucket to another without solving it. Document the original error date separately from the recovery date. Two fields. One line. It makes the audit trail legible. Multi-currency overpayments deserve special attention. If you paid a foreign vendor in their currency but your contract is in dollars, the overpayment amount depends on which exchange rate you use for the comparison. Spot rate on payment date? Average monthly rate? Contractually agreed rate? Pick one and stick with it. I use the spot rate on the payment date because it's the most defensible and the easiest to verify. If your organization uses something else, make that explicit in the calculator documentation so auditors don't spend a day arguing about methodology.
What a proper Overpayment Calculator should include
Beyond the basic subtraction, a useful tool needs a few more features. Threshold management is essential — set minimums for auto-flagging so minor rounding errors don't clog your review queue. Recovery tracking is next — once you identify an overpayment, the calculator should generate a recovery action log with dates, responsible parties, and outcomes. Audit trail is non-negotiable. Every calculation should be timestamped with who ran it and what source data was used. Without that, you're just producing numbers that no one can defend. I recommend keeping the calculator as a separate working file from your main accounting system. Export your transaction data weekly, run the overpayment check in the calculator, then import the flagged items back into your GL as adjustments. This separation gives you a clean checkpoint where you can review, debate, and resolve before anything touches the official books. Doing it inside the GL system tends to produce hasty flagging and even hasty resolutions because you're working against the clock to close the period.
Limitations you need to accept
An Overpayment Calculator is a detection tool, not a recovery tool. It will tell you where money went wrong. It won't negotiate refunds, file reclaimed payment requests, or update vendor master records. You still need human judgment for those steps. The calculator also struggles with discretionary payments — tips, bonuses, allowances — where the "authorized amount" is inherently fuzzy. It works best in environments with clear contractual baselines. If your organization relies heavily on verbal agreements or informal pricing, the calculator will generate more false positives than real findings. In those cases, the workaround is to build a secondary review layer where flagged items get manually validated against whatever informal documentation exists before they enter the formal tracking pipeline. That adds time but prevents the calculator from becoming a complaint generator. The biggest limitation is that calculators don't prevent overpayments. They only find them after the fact. If you want to reduce the root problem, you need to tighten the upstream controls — purchase order accuracy, payment authorization workflows, contract version management. The calculator is the safety net, not the guardrail.
Getting started without custom software
You don't need expensive proprietary tools. A well-structured spreadsheet with three input columns — actual payment, authorized amount, reference ID — and two output columns — overpayment amount and flag status — covers most small-scale needs. Add a data validation dropdown for payment type and a simple IF formula for threshold flagging. I've run this exact setup for six years across three different organizations. It catches overpayments that would otherwise sit undiscovered for quarters. For larger operations, dedicated AP reconciliation modules in ERP systems can handle the volume, but they often lack the flexibility to handle non-standard payment types. I've seen people maintain a separate calculator alongside their ERP for exactly that reason. Hybrid approaches tend to work better than any single tool trying to do everything. The core insight that most people miss is that overpayment detection is a data hygiene problem, not a math problem. Clean source data produces clean results. Messy source data produces messy results that look like answers but aren't. Spend your time fixing the inputs. The calculator will do the rest.