What the Pennsylvania Life, Health and Accident Insurance Exam Actually Tests
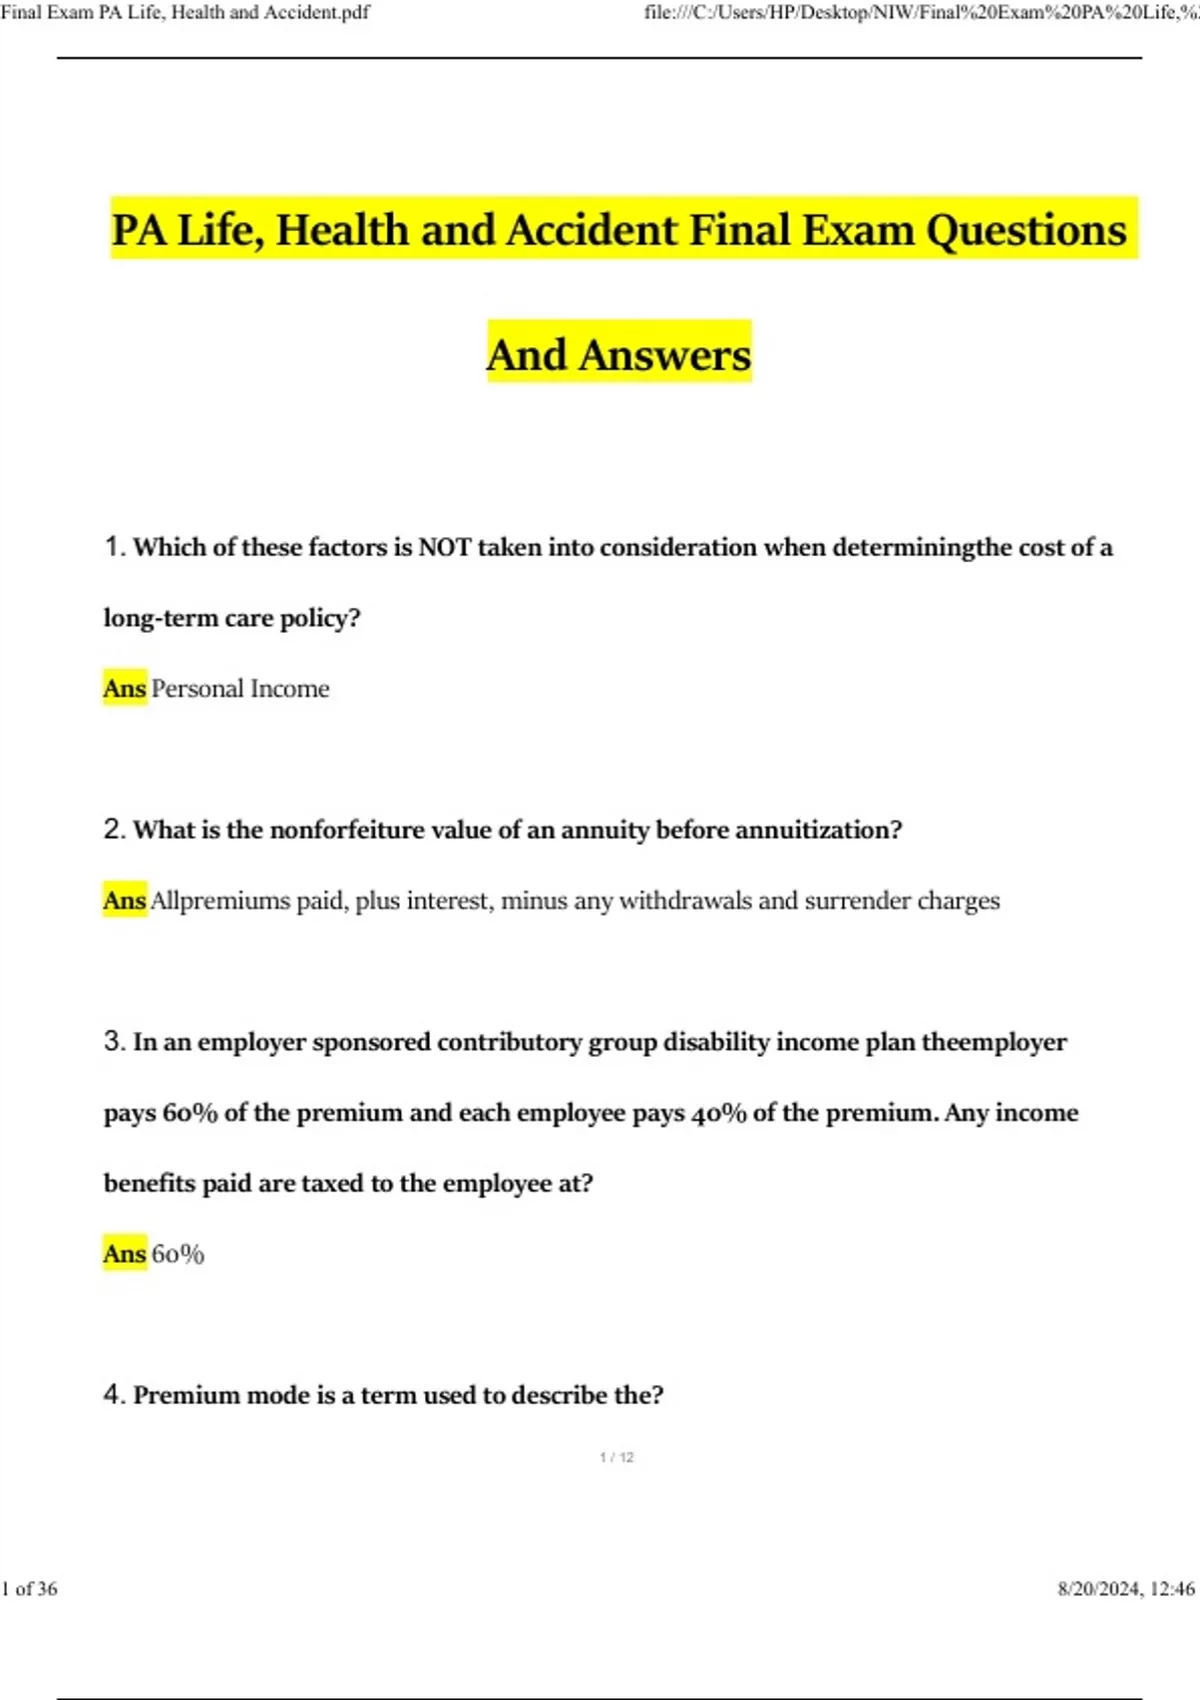
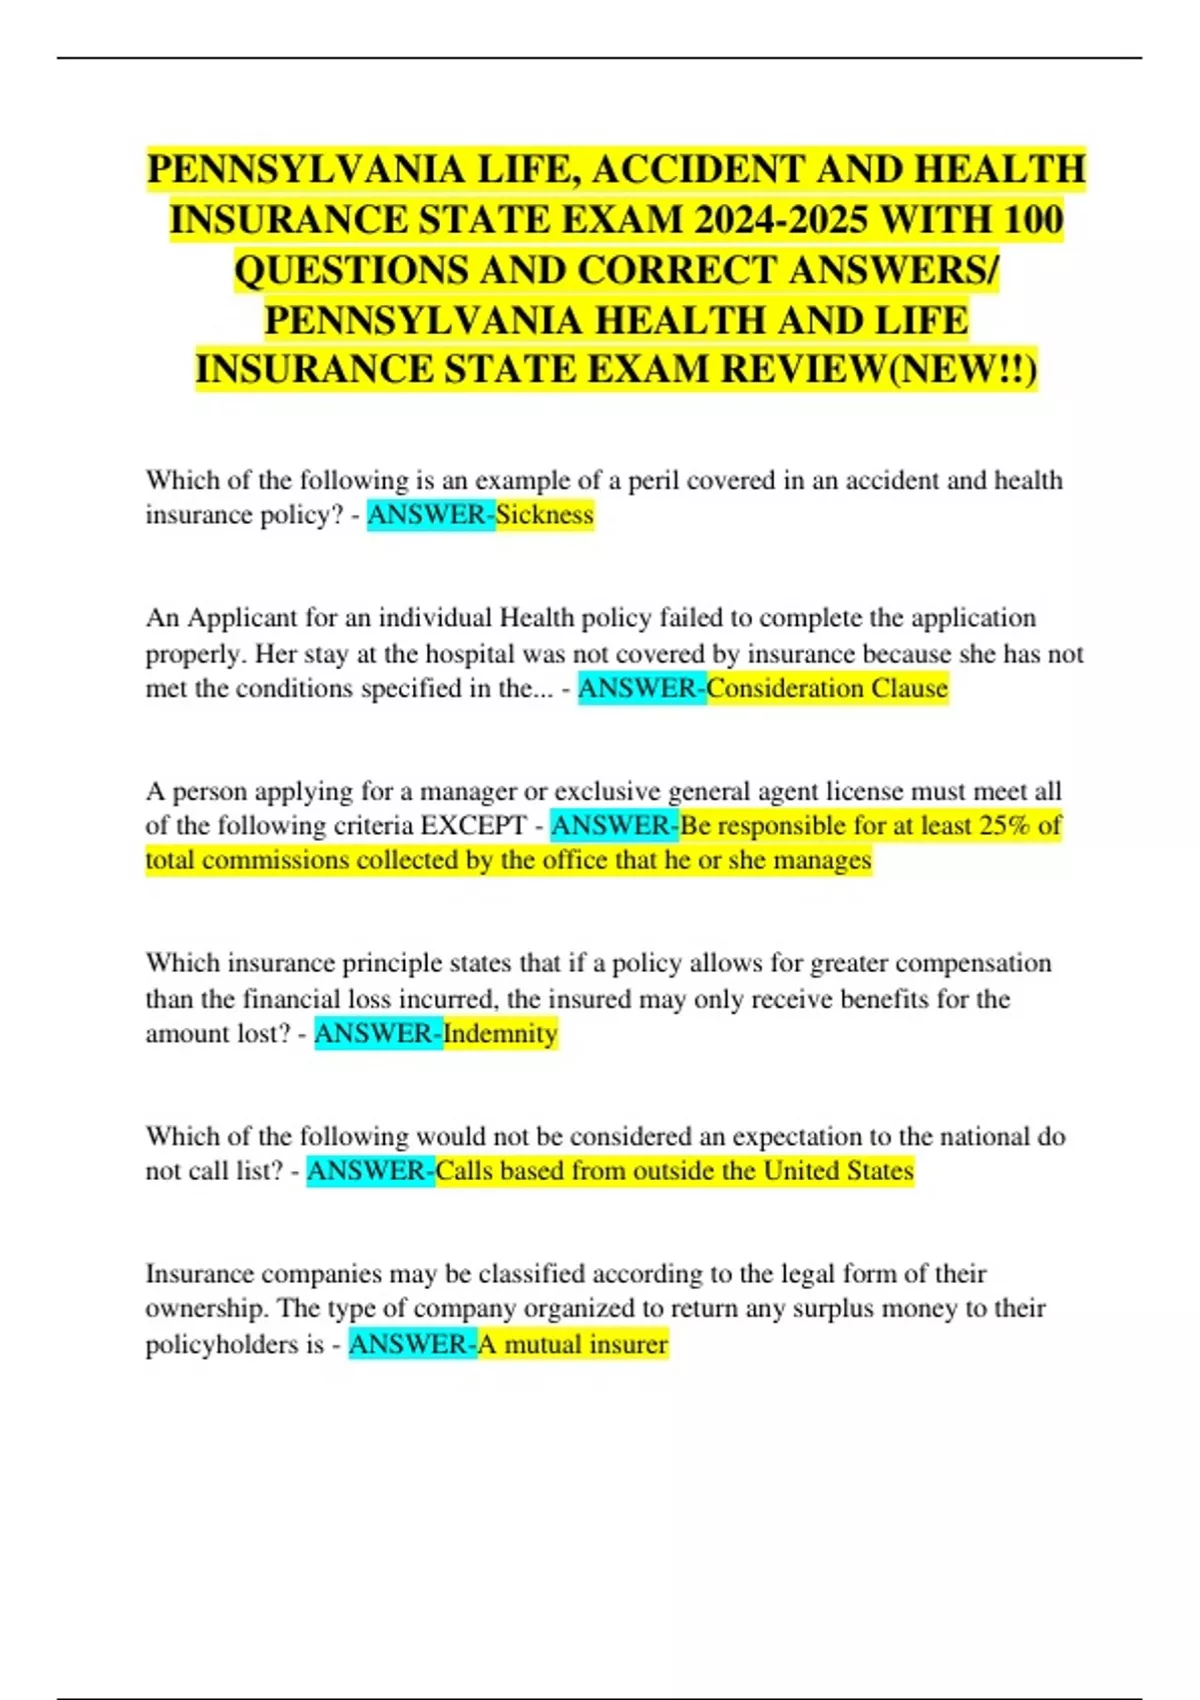
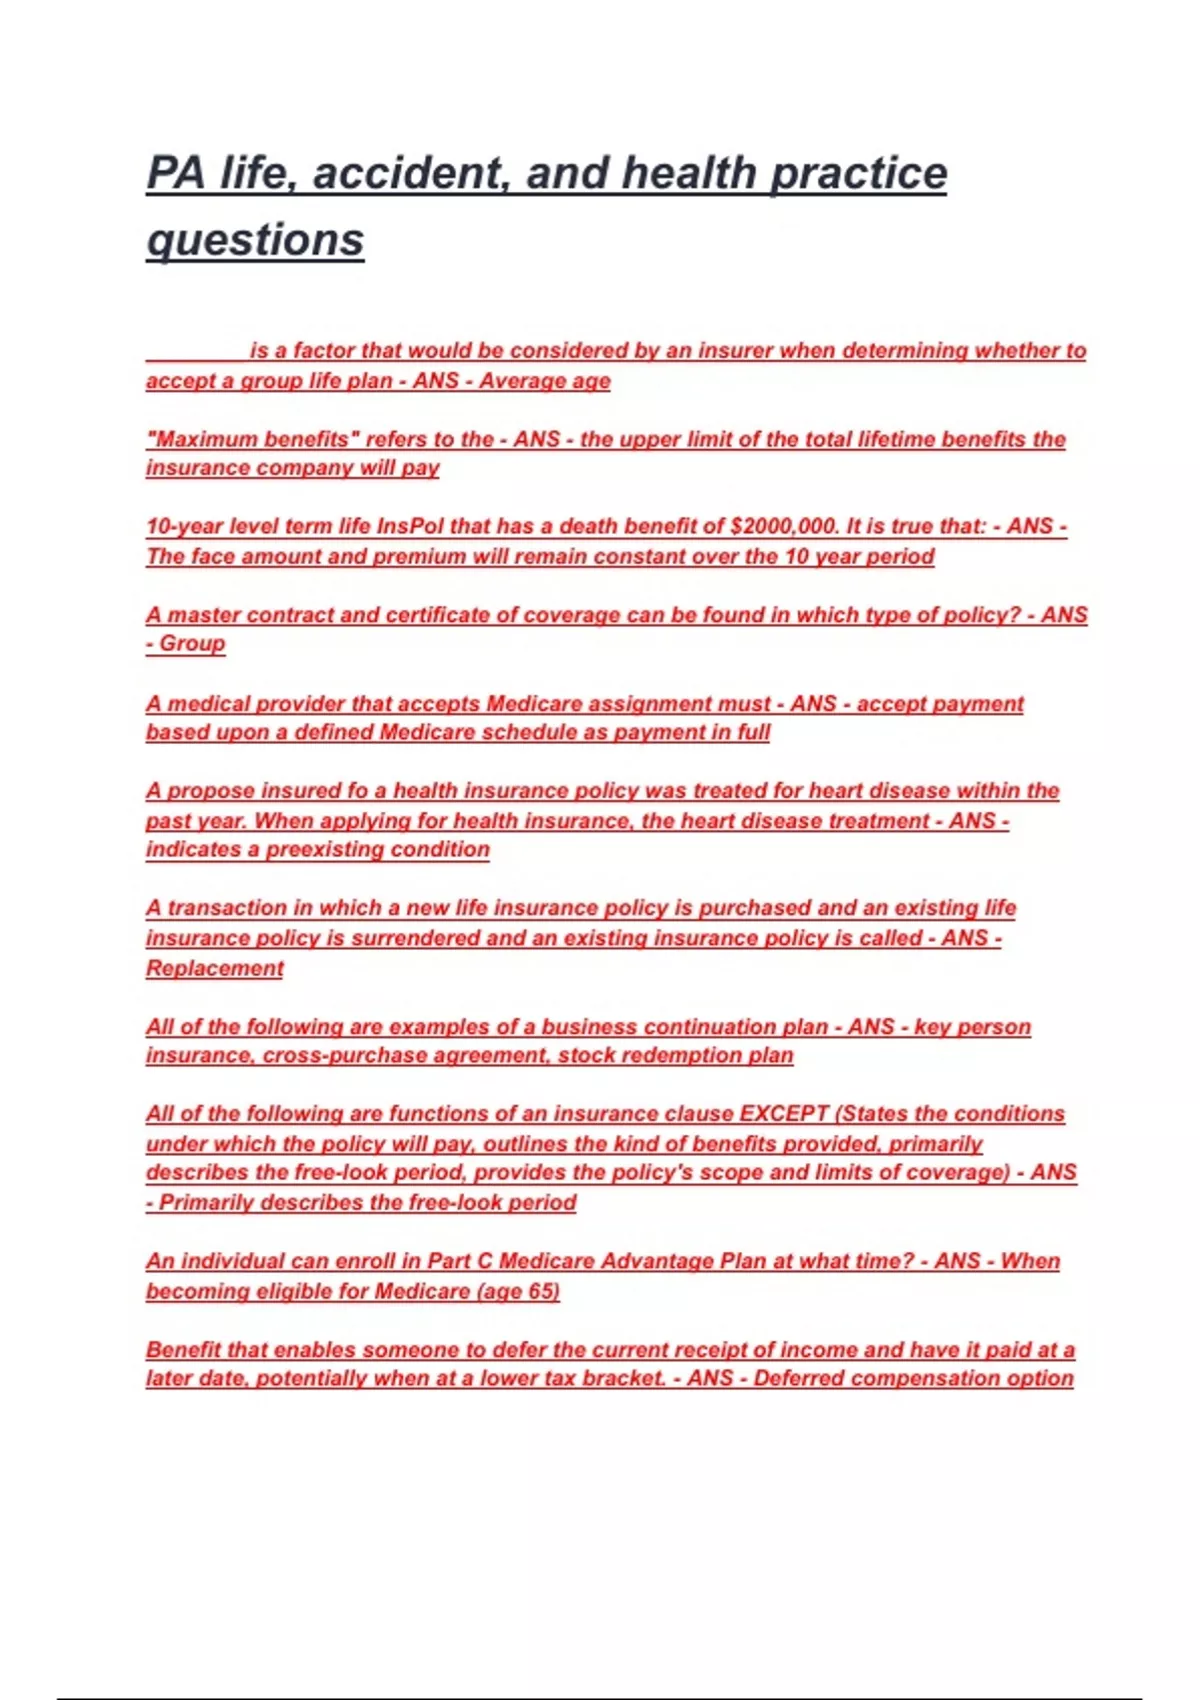
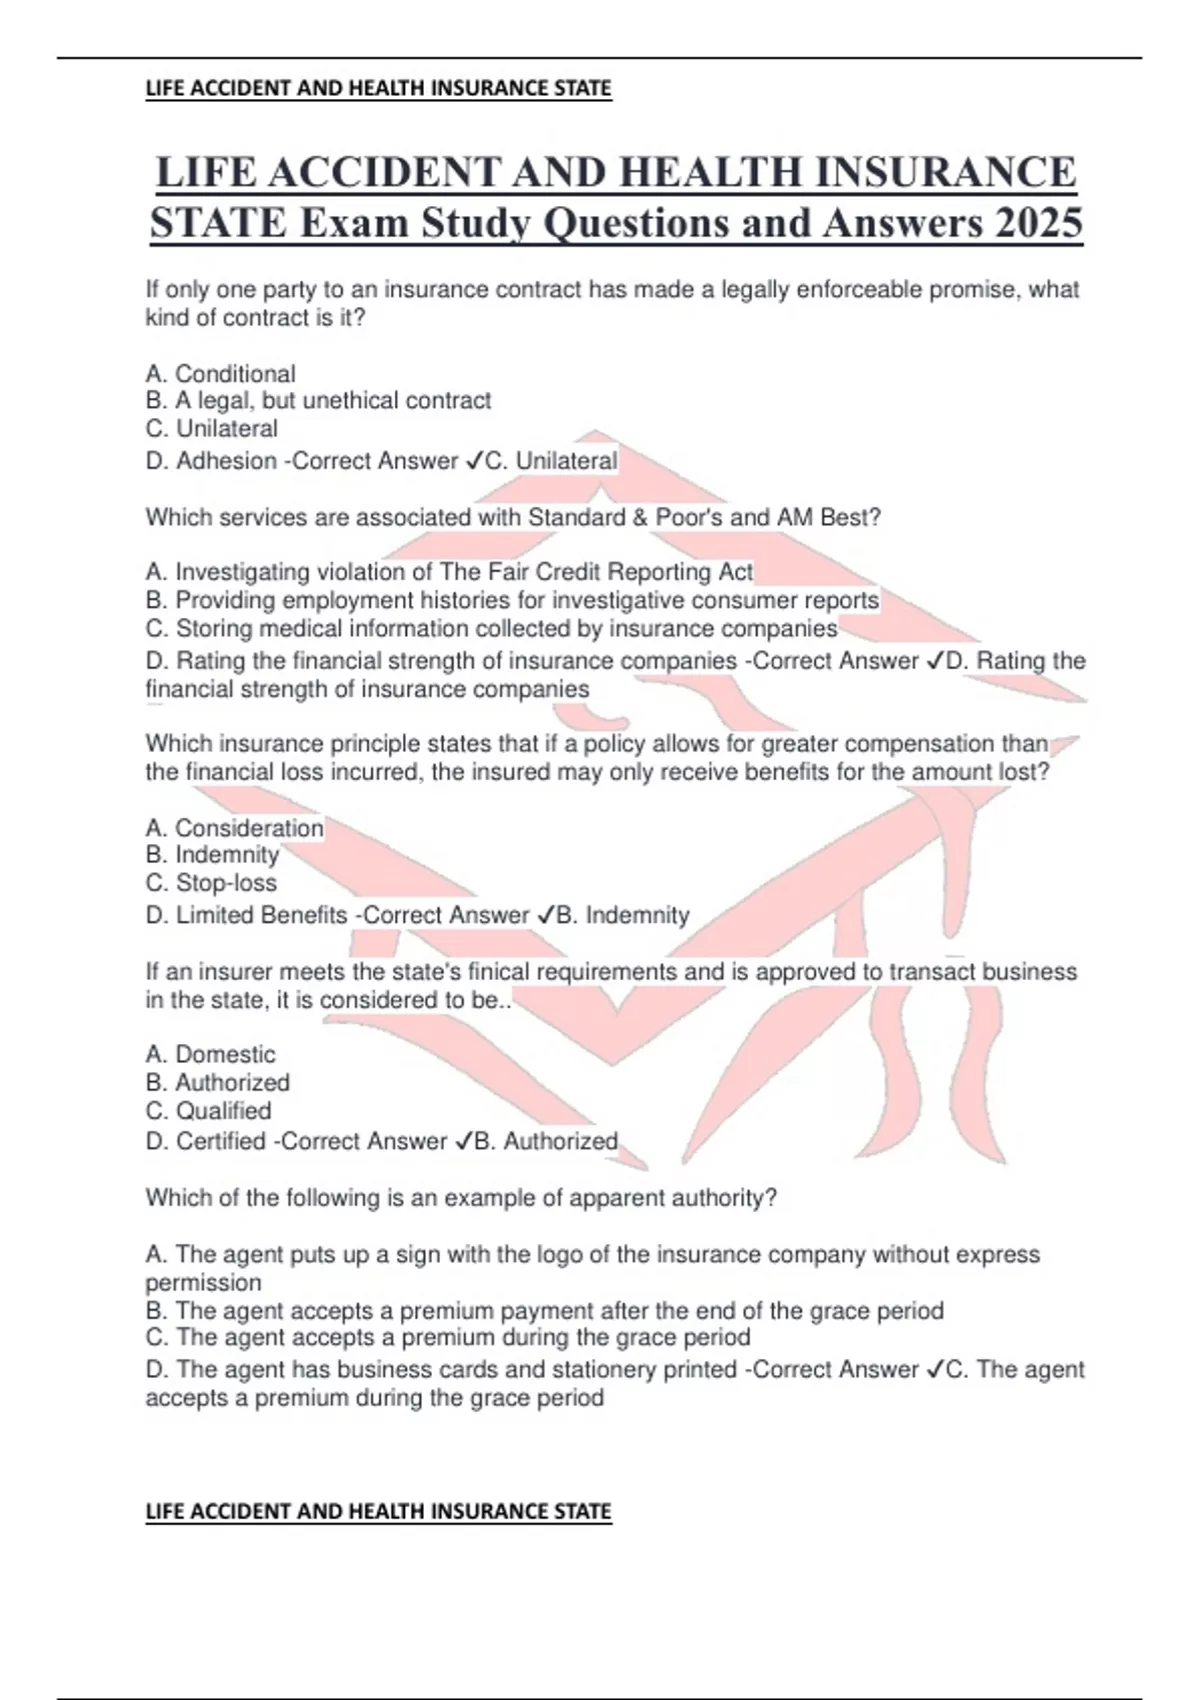
The Pennsylvania Life, Health and Accident Insurance Exam is your gateway to selling insurance in the state. It covers life insurance, health insurance, and accident insurance specifically under PA regulations. Most people treat it like a standard standardized test, but it has its own quirks that catch people off guard if they aren't paying attention. The exam itself is administered by Pearson VUE after you complete the required pre-licensing education. You need a score of at least 70% to pass. The questions are multiple choice, usually around 100 to 120 depending on the line of authority you're testing for. Here is the thing nobody tells you straight. Studying for the PA Life Health And Accident exam using materials designed for other states will get you in trouble. Pennsylvania has specific provisions in its insurance code that differ from the NAIC model in meaningful ways. I spent an afternoon trying to memorize sliding scale premium tables that turned out to be completely irrelevant to the PA exam because they were from a Florida prep course I grabbed cheap. That hour would have been better spent on Pennsylvania-specific claim settlement practices. The real content you need to know falls into a few buckets. Life insurance fundamentals, policy provisions and riders, health insurance basics including Medicare supplement and long-term care, and the accident component which mostly ties into disability income products. Pennsylvania also tests you on their specific unfair trade practices and insurance fraud provisions. Those sections tend to be straightforward if you read them, but most people skip ahead because they seem dry.
One counter-intuitive insight about this exam is how heavily it weights policy provisions over product mechanics. You will see more questions asking about the incontestable clause, the grace period, the reinstatement provisions, and the misstatement of age provision than you will on complex mortality table calculations. These provisions carry significant dollar amounts in real claims, so the state cares that you know them. The mortality table questions that do show up are usually basic illustrations, not actuarial-level math. Another thing beginners miss is the way Pennsylvania structures its combined exam. If you are taking the Life and Health line together, expect to spend about two and a half hours in the testing center. The question distribution skews slightly toward health because it is the broader category. Health includes everything from individual medical policies through Medicare parts A through D, Medicaid interactions, and long-term care insurance. Many candidates underestimate the Medicare section. The Medicare questions alone can account for roughly fifteen percent of the entire exam, and they require knowing current year program details, not just generic concepts.
How I Actually Passed Mine After the First Try Didn't Work
My first attempt was a disaster. I scored 63. I had studied the course materials cover to cover and felt confident going in. The problem was I hadn't done enough practice questions under timed conditions. The exam pace is faster than the prep courses make it feel. When you see 100 questions in front of you and roughly ninety minutes to complete them, you are looking at about thirty-six seconds per question on average. Thirty-six seconds including the ones where you have to eliminate two wrong answers before picking between the remaining two. Under pressure, people circle the first answer that looks right and move on. That is how you miss questions on policy replacement rules, which have a specific sequence of steps in Pennsylvania. The specific edge case I hit was a question about the free look period for annuity contracts in Pennsylvania. The standard free look is ten days for most insurance products, but annuities have a different window depending on whether they are issued within or outside the state. I had memorized the general rule and got the question wrong because I didn't account for the interstate provision. The workaround was to stop memorizing standalone rules and start building comparison tables. I made a one-page reference sheet that lined up every time limit, clause type, and disclosure requirement side by side. Free look periods, grace periods, incontestability periods, claim filing deadlines, and premium refund windows all go on that same sheet. When you see them grouped together, the patterns become obvious. After my retake, I switched strategies completely. Instead of re-reading the textbook, I took practice exams back to back until I could consistently score above 80%. Then I reviewed every wrong answer and wrote down why I got it wrong. Was it a knowledge gap? Did I misread the question? Was it a distractor I fell for? The misreading and distractor errors were far more common than actual knowledge gaps. On the actual retake, I missed maybe four or five questions total.
Get the Full Details
What the Exam Costs and How to Register
You need to complete a state-approved pre-licensing education course before you can schedule the exam. The course cost runs anywhere from fifty to two hundred dollars depending on whether you go online or in person. The exam fee itself is separate and typically runs around one hundred to one hundred twenty dollars paid directly to Pearson VUE. Pennsylvania also requires you to submit a license application through the state's licensing system with a background check, which adds another fee. Factor in roughly two hundred fifty to three fifty total out of pocket if you count everything. Scheduling through Pearson VUE is straightforward. You create an account, pick a testing center near you, and choose a time slot. Pennsylvania has Pearson VUE centers in major cities like Philadelphia, Pittsburgh, Harrisburg, and Allentown. If you live in a rural area, you might need to drive an hour or so to reach the nearest center. Plan your travel accordingly. Showing up twenty minutes early is recommended because you will need to provide two forms of identification, one of which must be a government issued photo ID.
A Few Things the Exam Won't Tell You That Matter
The exam will certify you to sell insurance, but it does not teach you how to actually write a policy. Passing this exam means you know the rules. It does not mean you know how to handle a client who needs to convert a term policy during their grace period, or how to explain the difference between a Medicare Advantage plan and a Medigap policy to someone who is confused. Those skills come from on the job training and mentorship. The exam is a compliance gate, not a comprehensive education in insurance practice. Also worth noting: Pennsylvania requires continuing education to maintain your license. You need thirty hours every two years, with at least two hours dedicated to ethics. If you plan to sell annuities, there is an additional four hour annuity training requirement separate from your CE. These are not optional. The state tracks CE completion through NIPR, so if you let it lapse your license goes inactive and you cannot sell anything until you reinstate, which involves a separate fee and possibly retaking the exam depending on how long it has been inactive. Some candidates ask whether there is a way to take the exam entirely online at home. Pennsylvania currently requires in-person testing at an approved Pearson VUE center for the Life, Health and Accident line. Remote proctoring is not available for this particular exam as of now. Check the Pearson VUE website for any updates, but don't count on it changing soon.
Bottom Line on Preparation
The Pa Life Health And Accident Insurance Exam is passable with focused effort if you target the right material. Prioritize Pennsylvania-specific content over generic insurance principles. Spend more time on practice questions than on passive reading. Build those comparison tables for policy provisions and time limits. And accept that your first practice exam score is not predictive unless it is consistently above 80%. The actual exam day conditions are different enough that you want a cushion built in. Most people who fail do so because they were overconfident after reading the textbook, not because the content was impossible. Treat it like a practical compliance test and you will be fine.