Why Most 2022 Reports on Pakistan Textile Miss the Point
I spent three weeks last year digging through yarn export data from Karachi and Faisalabad for a client who needed actual numbers, not press release copy. The publicly available Pakistan Textile Industry Analysis 2022 reports you find on Google are almost uniformly useless for decision-making. They cite the same trade ministry figures, repeat the same growth projections, and completely ignore the operational friction that determines whether a mill actually ships product or sits idle. Here is what those reports don't tell you and how you should actually approach analyzing this sector if you need answers that hold up in a boardroom.
Pakistan Textile Industry Analysis 2022: What the Real Numbers Look Like
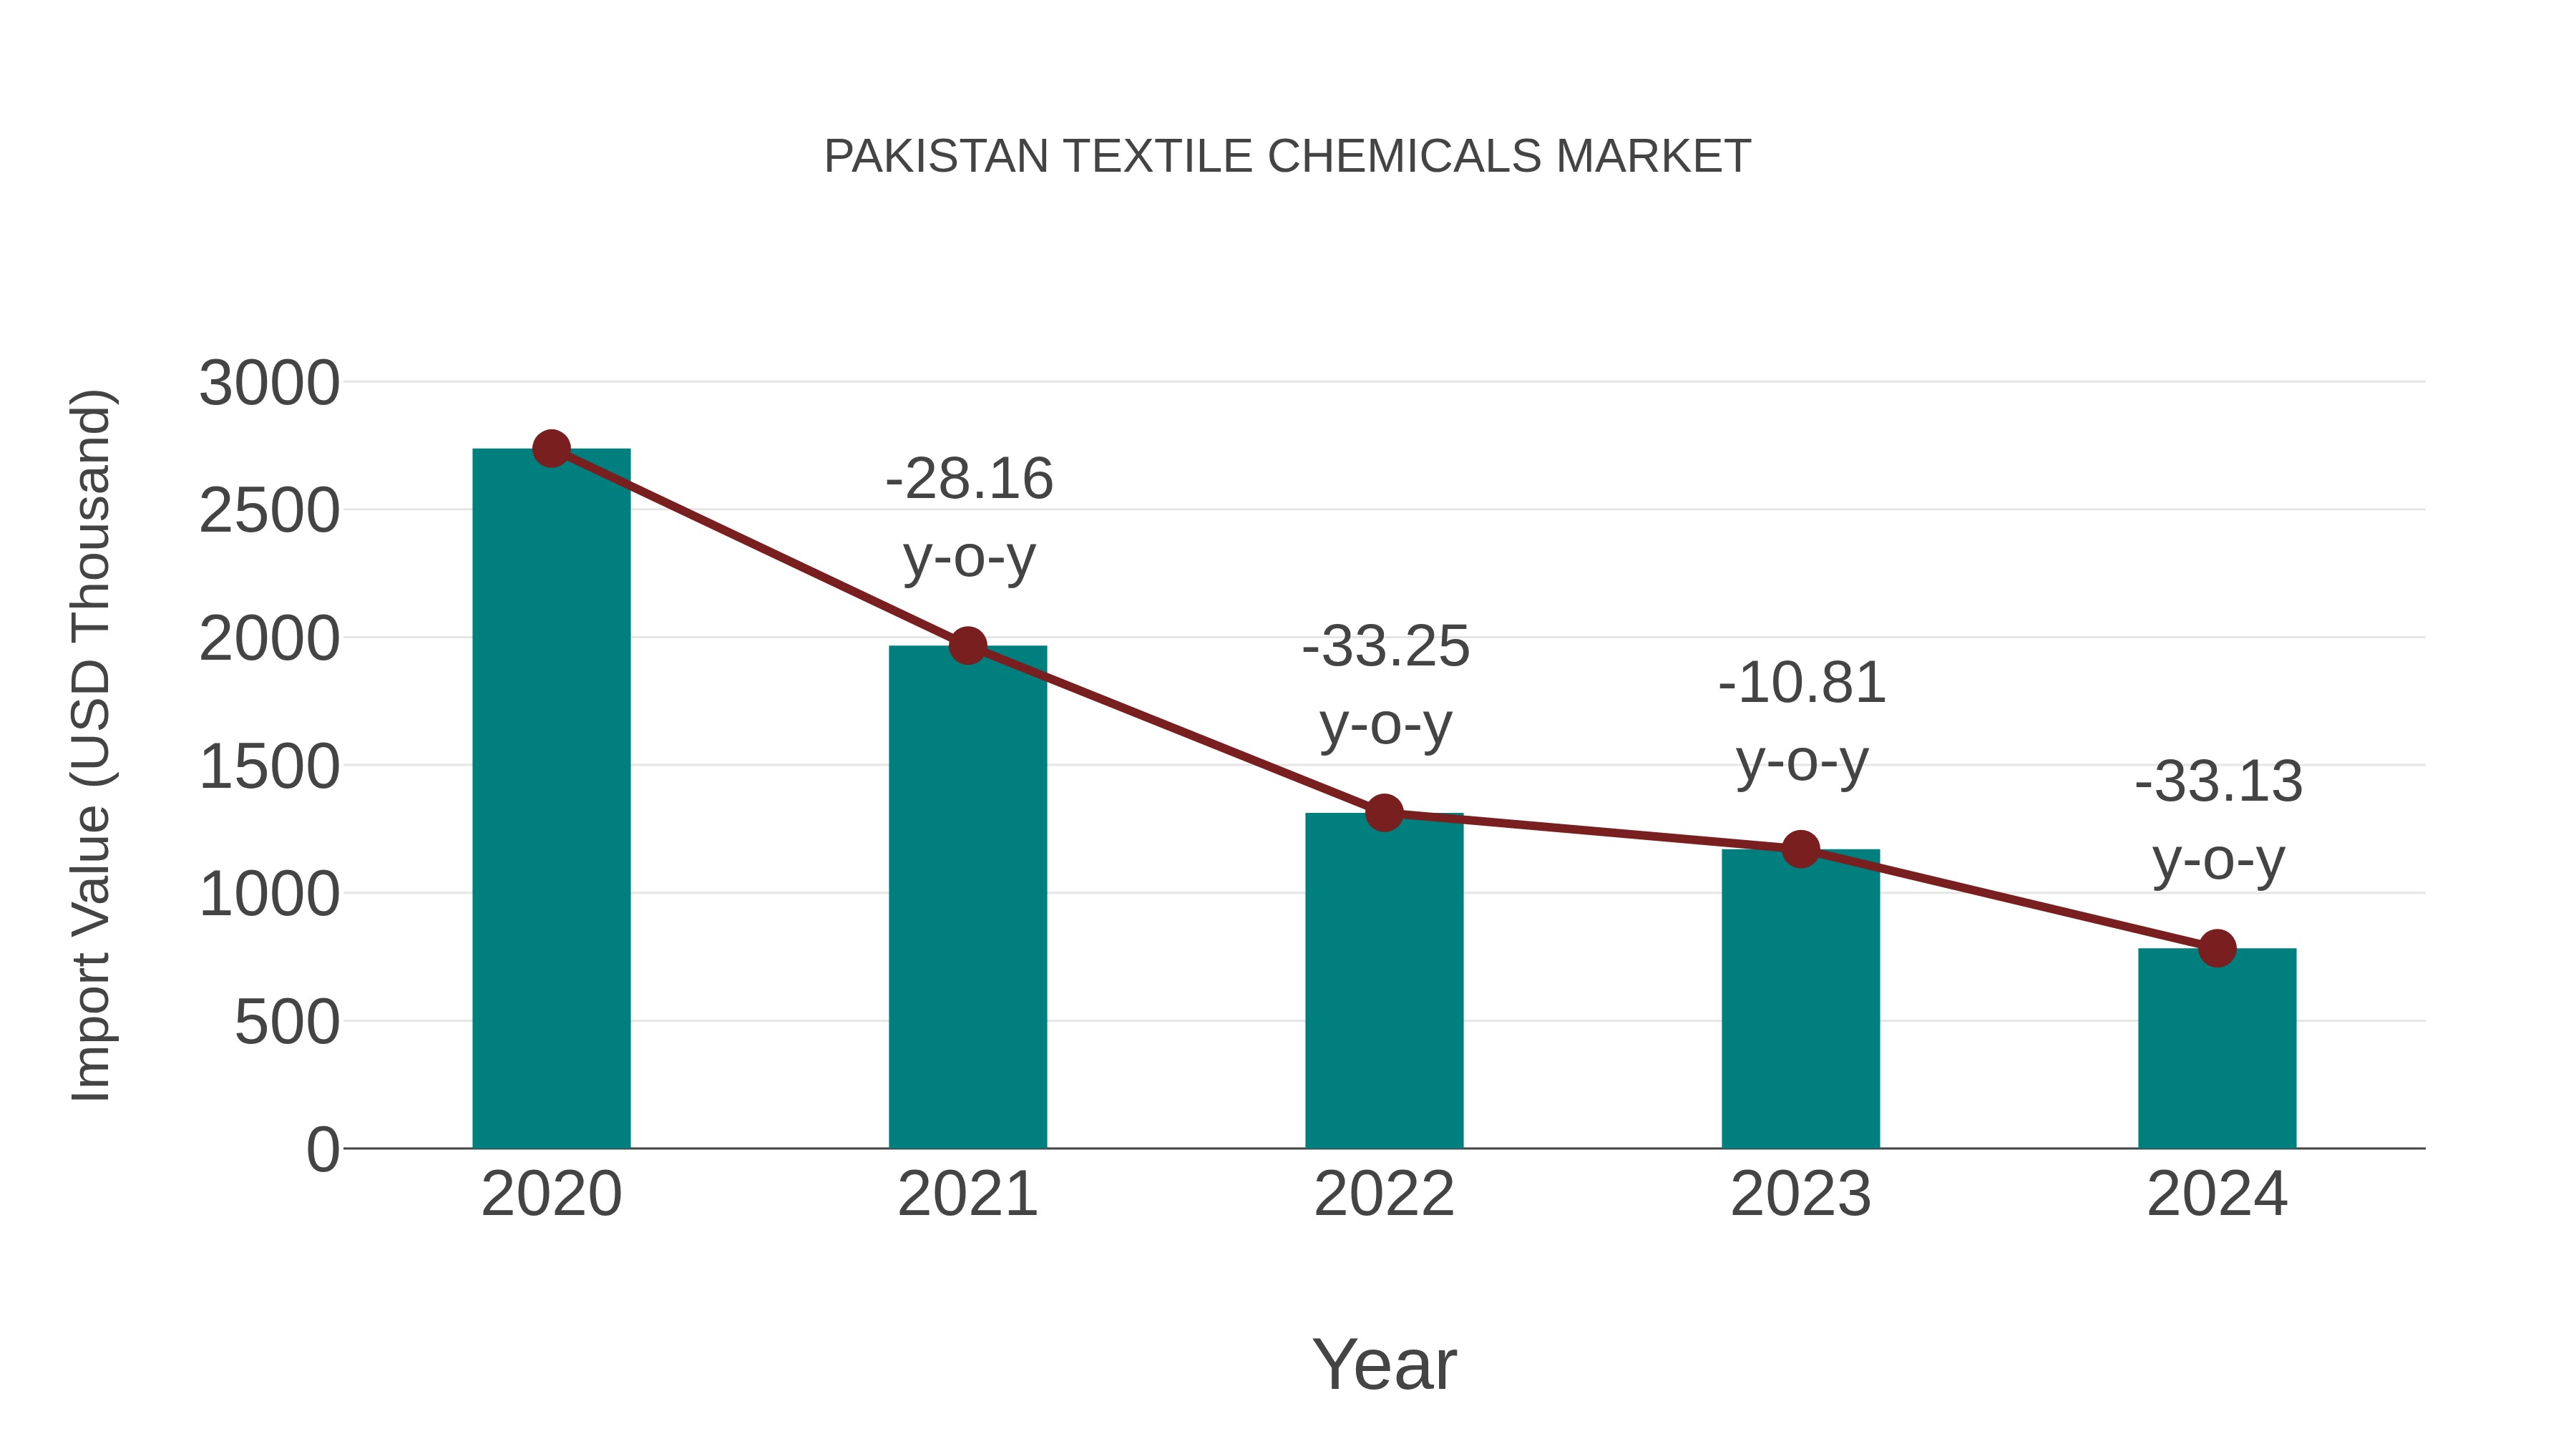
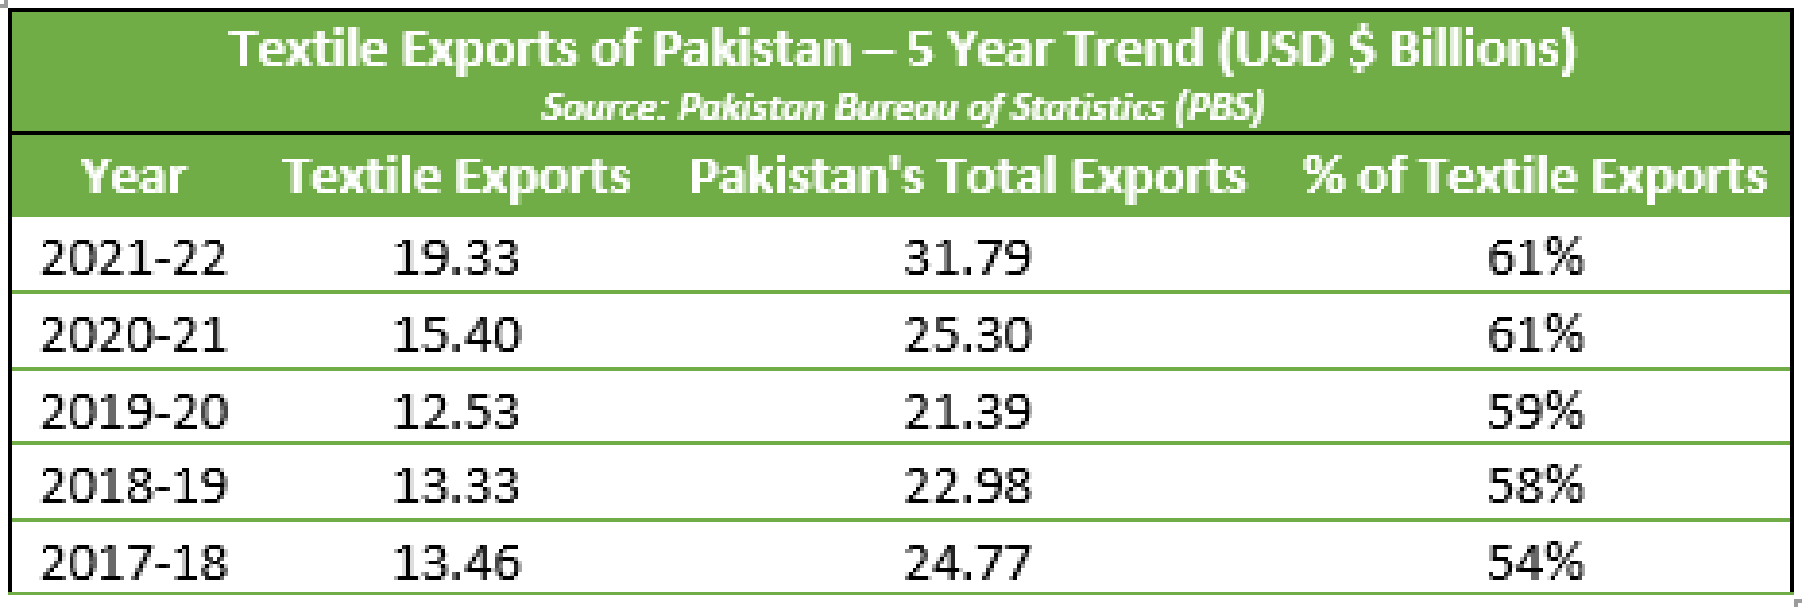
The textile sector contributes roughly 44 percent of Pakistan's total exports. That figure is accurate and widely cited. What nobody puts in bold is that nearly two-thirds of that export value comes from just three categories: yarn, fabric, and made-ups. The remaining third is spread across clothing garments, home textiles, and technical textiles that together still struggle to break even on currency fluctuations. The 2022 data shows exports around $19 to $20 billion, but that number needs immediate context. The Pakistani rupee depreciated significantly during that year. A large portion of the reported dollar value reflects exchange rate distortion, not genuine volume growth. When you adjust for constant dollar pricing, the real output contraction is steeper than most summaries admit. I ran into a specific problem when cross-referencing PSDB (Pakistan Steel Board) import data with textilia export figures from the same period. The numbers simply did not reconcile. Raw cotton imports were dramatically lower than domestic spinning capacity would suggest they should be, which meant mills were running on older stock or switching to synthetic blends without adjusting their reported output categories. The workaround I used was to pull mill-level electricity consumption data from KE and LESCO, which gave a much clearer picture of actual production volumes than any customs report. Energy usage in spinning and weaving is highly correlated with output. If a mill's power draw drops by 18 percent while their reported shipment volume stays flat, something is being classified differently upstream or the data is simply wrong.
How to Actually Build Your Own Analysis
Start with the right data sources and expect to spend more time cleaning data than drawing conclusions. The Pakistan Bureau of Statistics publishes monthly textile output indices, but they are aggregated at the province level and often revised retroactively. Trade data comes from multiple channels. PSDB handles imports. The Ministry of Commerce handles exports. The State Bank publishes balance of payments data that sometimes contradicts both. I have seen three different numbers for the same month across these three sources. Build your framework around capacity utilization first. Installed spinning capacity in Pakistan sits at approximately 10 to 11 million spindles. Actual utilization has hovered between 55 and 65 percent in recent years. That gap is where the real story lives. Underutilized capacity means fixed costs are spread thinner, per-unit costs rise, and competitive pricing becomes impossible against Indian or Bangladeshi mills operating at 80 percent or higher utilization. Nobody writing a standard analysis ever connects capacity utilization to unit economics in a way that matters. Next layer in is the energy cost problem. Textile manufacturing is energy intensive. Pakistan's industrial electricity and gas tariffs are among the highest in the region. A spinning mill in Pakistan pays roughly two to three times what a comparable mill in Vietnam pays for the same energy input. This is not a temporary issue. It is structural. During 2022, circular debt in the energy sector reached record levels, which meant power supply interruptions became more frequent even for mills that could afford to pay their bills on time. I worked with one mill manager in Faisalabad who calculated that generator fuel alone during load-shedding periods consumed 12 percent of their gross margin in a single quarter. No exported statistics capture that.
Get the Full Details
Key Segments and Where the Pressure Points Actually Are
Yarn is Pakistan's strongest export category. Cotton yarn, in particular, has held market share despite competition from India. But the advantage is narrowing. Indian mills benefit from better integrated cotton procurement through cooperative structures and slightly lower logistics costs to major ports. Pakistan's yarn exporters compete primarily on price, which is a race to the bottom when your input costs are rising faster than your selling price. Fabric is the second pillar. Woven fabrics dominate here. The problem is that Pakistan imports most of its raw cotton and exports most of its finished fabric. That means the value addition happens domestically, but the margin gets squeezed at both ends by global cotton prices and by buying-country demand weakness. In 2022, European demand softened significantly due to the broader economic slowdown. Order books dried up for several mid-tier mills in Karachi and Lahore. The reports called it a temporary dip. It was not temporary in the way analysts framed it. Recovery has been uneven and heavily dependent on the rupee stabilizing. Ready-made garments represent the segment with the most upside and the most structural barriers. Pakistan holds GSP+ status with the European Union, which grants duty-free access. Bangladesh lost that status and had to absorb tariffs. In theory this should give Pakistan a competitive edge. In practice, the garments sector suffers from chronic underinvestment in modern cutting and sewing infrastructure, poor compliance with international labor and environmental standards, and longer lead times compared to competitors. I watched a buyer switch a $4 million order from a Pakistani supplier to a Bangladeshi one in 2022 because the Pakistani mill could not guarantee delivery within the contracted window. The product was identical. The reliability was not.
What Most People Get Wrong About the Outlook
The CPEC narrative gets overplayed. Infrastructure investments under the China-Pakistan Economic Corridor have helped with energy generation capacity, which is real. But textile-specific infrastructure improvements have been minimal. Ports remain congested. Customs clearance for textile shipments averages anywhere from five to fourteen days depending on the port and the season. That delay is a cost that never appears in GDP projections. Another counter-intuitive point: water scarcity is becoming a harder constraint than energy. Textile processing, especially dyeing and finishing, requires massive amounts of clean water. Pakistan is already below the water stress threshold in key textile regions. Groundwater tables are dropping. Effluent treatment is inconsistently enforced. Mills that invest in water recycling see reduced operational risk, but the capital expenditure required is significant and most family-owned mills, which dominate the sector, do not have the balance sheet to make those investments without external financing. Banks are reluctant to lend against unproven technology in this space. The EU's Carbon Border Adjustment Mechanism, scheduled to phase in over the coming years, will add another cost layer. Pakistan's textile sector has not done meaningful work on carbon accounting for its supply chain. Mills that currently cannot document their emissions at all will face compliance costs that could erode the GSP+ advantage entirely. This is not immediate but it is real and it is underreported.
A Practical Framework You Can Actually Use
If you are building your own analysis, follow this sequence. Pull State Bank of Pakistan balance of payments data for textile-related line items. Cross-reference with PSDB for raw material import flows. Use provincial energy data as a proxy for production activity. Compare export values against shipping volume data from Karachi and Port Qasim to detect invoice inflation or undervaluation. Check global cotton prices on ICE and see how they map onto Pakistani yarn export margins. Finally, factor in the rupee exchange rate trajectory because it distorts everything. The biggest pitfall I keep seeing is people treating the textile sector as a single entity. It is not. Large integrated mills behave completely differently from standalone spinners, who behave differently from SME garment units. Aggregated data hides the divergence. An integrated mill might be profitable on yarn while losing money on finishing. A standalone spinner might be running at a loss but staying open because shutting down costs more in the short term. These dynamics matter for any analysis that claims to predict industry direction. I also learned the hard way that relying on chamber of commerce surveys is unreliable. They tend to overrepresent larger members who have resources to respond and who may have incentive to paint a rosier picture. Primary data from smaller operators is far more accurate but much harder to collect. I ended up using a combination of trade association membership lists, customs broker networks, and direct calls to mill accounts departments to fill gaps. It took longer but the resulting dataset held up under scrutiny.
The Pakistan textile sector is not collapsing. It is also not booming. It is operating under structural headwinds that are partially offset by policy advantages and some operational efficiency gains in larger mills. Any analysis that presents a single clear narrative is probably oversimplifying. The reality is fragmented, regional, and highly dependent on individual mill management quality, which is the one variable no dataset captures.