Why people start throwing extra money at their mortgage
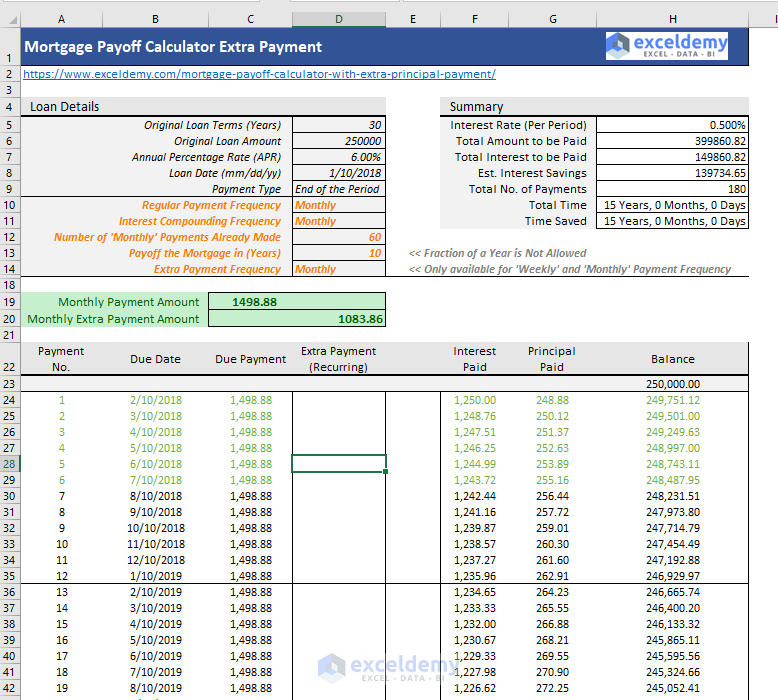
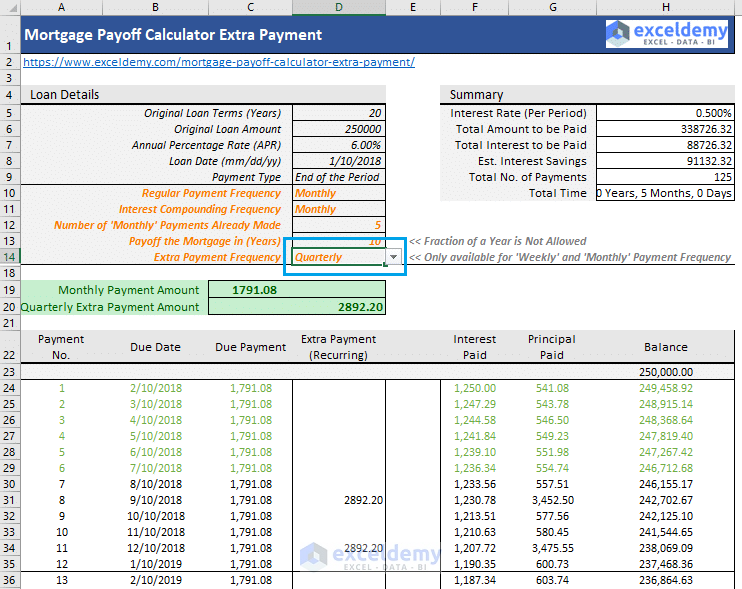
I get a lot of emails from people who just realized they're paying roughly the same amount each month but most of it goes to interest for the first decade of a 30-year loan. That's not a scam, it's just how amortization works. You can speed things up by paying down the principal faster, but most people don't actually know how to track it or whether it's worth the effort. A Pay Extra Principal Calculator is what most of us use to figure out the math before committing. The mechanics are simple enough that you could do it by hand, but doing it manually for multiple scenarios is where people give up. Here's the basic flow: you take your remaining principal balance, apply your extra payment to it immediately, recalculate the next month's interest on the reduced balance, then subtract the new interest from your regular payment to see how much more of your normal payment goes toward principal. Repeat that for every month going forward. The key thing most online calculators get wrong or that users misunderstand is how the extra payment interacts with the amortization schedule. Your regular monthly payment doesn't change. What changes is the split between interest and principal within that same payment. When you throw extra money at the principal, the interest portion shrinks the following month because it's calculated on a smaller balance. Your payment stays fixed, so the difference is what accelerates the payoff.
Basic Pay Extra Principal Calculator walkthrough
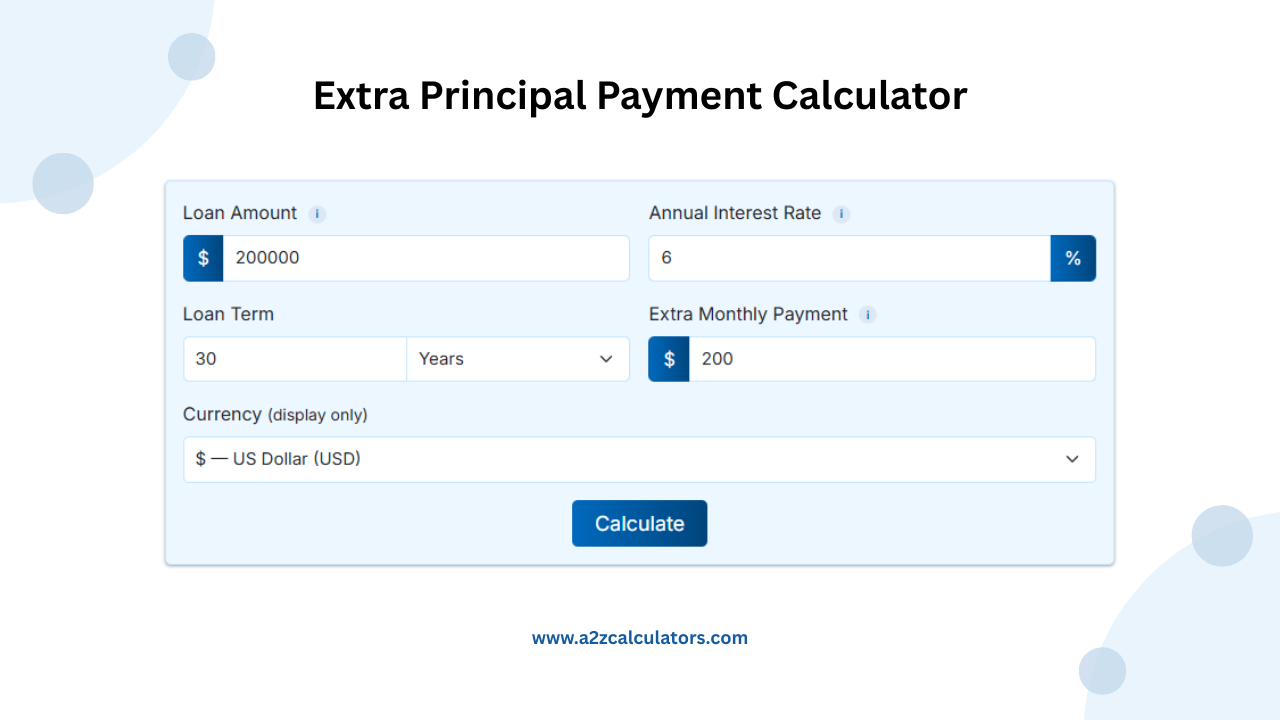
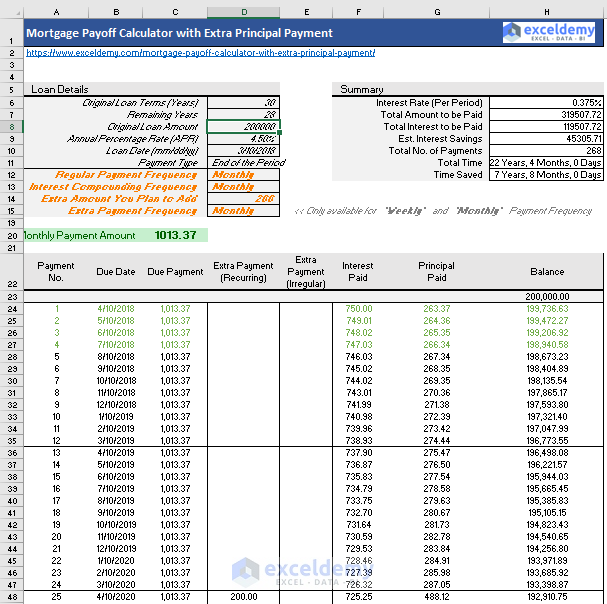
Enter your current loan balance, interest rate, and remaining term. Then enter the extra amount you want to pay per month or as a lump sum. The calculator runs through the new amortization schedule and shows you the difference. The output you actually care about is the total interest savings and how many months or years you shave off the loan. Everything else is just noise. Let me give you a concrete example. Say you have a $350,000 mortgage at 6.5% for 30 years. Your regular payment is about $2,212 per month. Throw an extra $500 toward principal every month and the calculator will show you shaving roughly 7 years off the loan and saving somewhere around $65,000 to $75,000 in total interest depending on exactly when during the month the payment posts. Those numbers shift based on how your lender applies the payment, which brings me to the part nobody warns you about.
The edge case that cost me three weeks
A few years back a client came to me with a refinance situation. They'd been making extra principal payments for over a year and thought they were on track to kill the loan early. The calculator numbers looked great. Then I pulled the actual statements and found the payments weren't going to principal at all. The lender was treating the extra as a "future payment credit" and applying it only when the regular due date arrived, which meant the interest was still compounding on the full balance the entire time. It took me six weeks to get the lender to change their application method. The workaround was straightforward but annoying. I had my client call the lender and specifically request that all extra payments be designated as "principal only" rather than "additional payment." Some lenders require a separate form. Others will just apply it wherever they feel like. You have to ask, and you have to get it in writing if possible. After that change, the calculator numbers finally matched reality and we were back on track.
Get the Full Details

Things most people miss about extra principal payments
The first thing beginners don't understand is that there's a difference between paying extra monthly and switching to a biweekly payment plan. A true biweekly plan means you pay half your monthly payment every two weeks, which results in 26 half-payments per year instead of 24. That's one full extra payment per year without any active decision-making. Most people conflate the two approaches and end up surprised when their calculator results don't match their actual payments. The second thing is the compounding effect of timing. If you make an extra principal payment in month one of a 30-year loan, you're saving interest on that money for 360 months. If you do it in year twenty, you're only saving it for 120 months. The dollar amount saved is dramatically different even though the payment size is identical. This is why putting extra principal on early matters more than most calculators make obvious. The output tells you the total savings but doesn't always highlight how much of that value is front-loaded versus back-loaded.
When extra principal payments are actually a bad idea
I need to be blunt about this because most calculators won't tell you. If you have a mortgage with a prepayment penalty, you need to check the terms before running any numbers. Some loans charge a penalty if you pay down more than a certain percentage in a given year. I've seen penalties of 2% on the amount paid above the threshold. On a $50,000 extra payment, that's $1,000 you just handed to the lender for the privilege of paying them early. The calculator will still show you interest savings, but once you factor in the penalty, the math flips negative for the first few years. Another scenario where extra principal makes sense less often is when you have higher-interest debt elsewhere. If you're carrying credit card balances at 18% or personal loan debt at 12%, paying extra on a 6.5% mortgage is mathematically irrational. The calculator will show you mortgage savings, but you're leaving money on the table elsewhere. Pay down the high-interest debt first, then redirect those payments to the mortgage principal. There's also the liquidity tradeoff. Money you throw at your house principal is locked in home equity. You can't easily access it without refinancing or a HELOC, and both of those involve new closing costs and potentially higher rates. If you're considering a large extra payment, ask yourself whether that cash would serve you better as an emergency fund or invested in something liquid. A mortgage paydown is a safe return, but it's not necessarily the best return for your situation.
How to actually use a Pay Extra Principal Calculator effectively
Run the base scenario first with no extra payments. Write down the total interest and payoff date. Then run the scenario with your intended extra amount. The difference between those two outputs is your actual benefit. Don't just look at the projected savings in isolation. A calculator showing "$80,000 in savings" sounds impressive until you realize your monthly payment would need to increase by $400 to achieve it, and you can't actually afford that increase. The most useful thing you can do with these calculators is run sensitivity analysis. Test what happens at $200 extra per month, then $400, then $600. You'll find the point where the savings curve starts flattening out relative to the cash you're committing. For most borrowers, the optimal extra payment isn't the maximum they can afford. It's the amount that leaves enough breathing room for unexpected expenses while still meaningfully changing the payoff timeline. That breakpoint varies wildly from person to person.
What to do if your lender doesn't support extra principal easily
If your lender's system is clunky or they resist principal-only designations, you have options. Some borrowers set up a separate savings account and deposit the extra amount each month, then make a single large principal payment once or twice a year. This avoids monthly administrative friction and often results in larger, more meaningful chunks going to principal. The tradeoff is that you're deferring the interest savings until the larger payment actually posts, so the total benefit is slightly lower than making smaller extra payments monthly. But the difference is usually marginal compared to the hassle of fighting with a lender's payment system every single month. Another approach is to recast the loan if your lender allows it. You make a large lump-sum principal payment and the lender-calculates your monthly payment based on the new balance and remaining term. Your monthly payment drops significantly, which improves your cash flow and debt-to-income ratio. This is different from paying extra monthly because it permanently changes your payment structure rather than just shortening the payoff date. Some lenders charge a fee for this, typically a few hundred dollars, but the cash flow benefit can be worth it if you're payment-constrained.