Understanding How Early Payoff Calculators Actually Work for Home Equity Loans
A Pay Off Home Equity Loan Early Calculator is essentially a projection tool. You plug in your remaining balance, your interest rate, your current payment schedule, and then throw extra money at it to see what happens. The output shows you reduced total interest and a shorter term. Most people treat the results like gospel and just start making payments accordingly. It works, but there are enough traps that treating it as literal truth can cost you time and money. The basic mechanics are straightforward. The calculator takes your amortization schedule and recalculates it based on an accelerated payment amount. Each additional dollar you pay goes directly against principal, which reduces the compounding interest over the remaining life of the loan. That is the entire mechanism. What most people miss is that the calculator assumes a uniform principal balance and a standard accrual method, which is almost never the case in practice.
Using a Pay Off Home Equity Loan Early Calculator
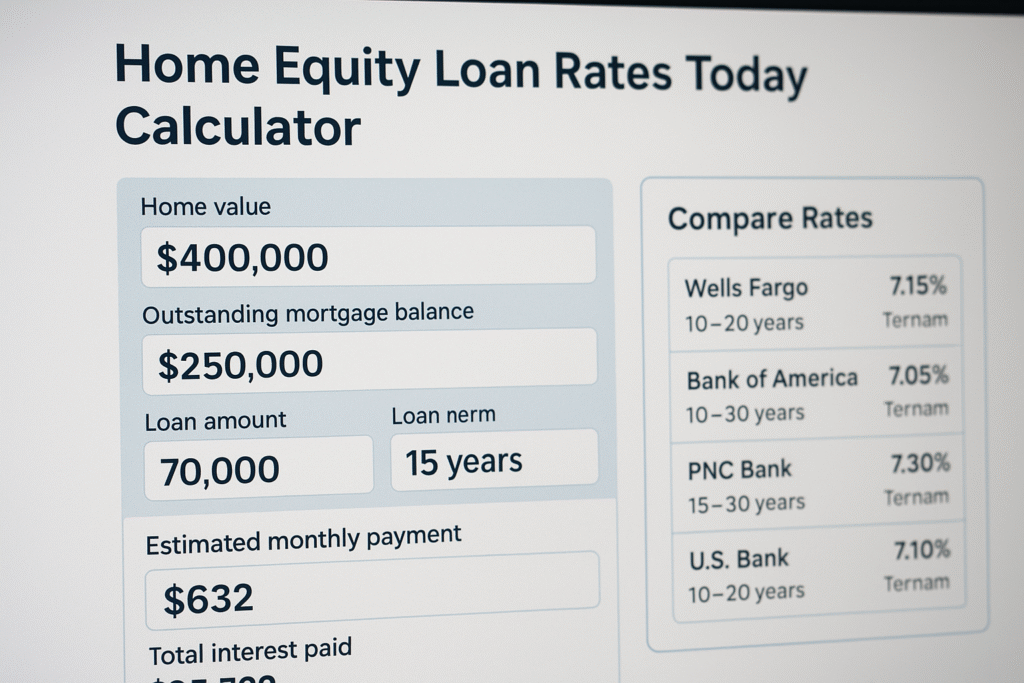
You will need a few pieces of information before opening any tool. Your current remaining principal balance. Your annual percentage rate. The number of months left on your original term. Your minimum monthly payment. And the specific type of your home equity product, which matters more than most people realize. Home equity lines of credit work differently from home equity loans. A HELOC in draw phase with an interest-only minimum payment will produce wildly different payoff projections than a closed-end second mortgage with a fixed amortization schedule. The calculator can handle both, but the accuracy depends entirely on whether you input the right product type. Pick the wrong one and your projected payoff date could be off by several years. Enter your data into whatever calculator you are using. Make sure the tool lets you specify your extra payment as either a one-time lump sum or a recurring additional monthly amount. The distinction matters because a one-time $10,000 payment hit at month three produces a completely different outcome than $350 extra per month over the same period, even if the total additional principal is similar. Recurring payments stay consistently ahead of the curve. One-time payments create temporary drops in balance that the interest calculation has to re-absorb over the following months.
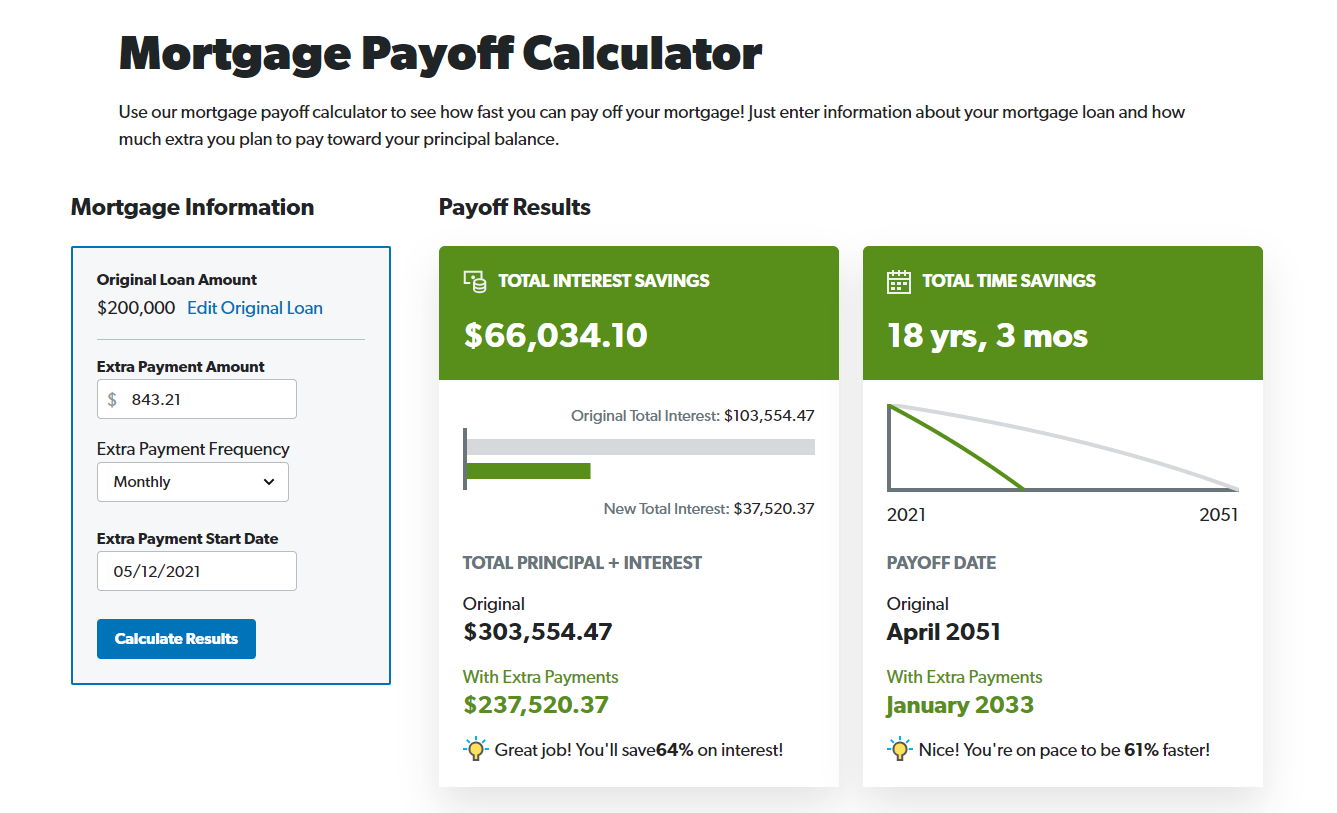
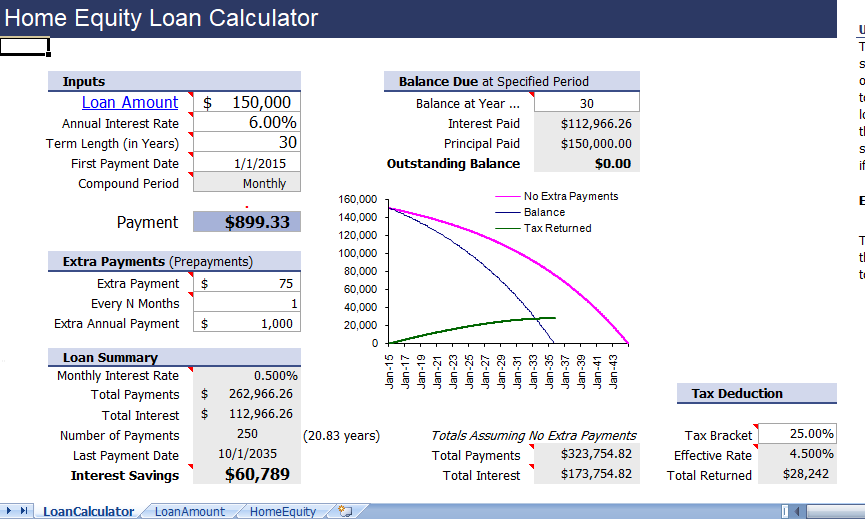
Review the output. Look at the new payoff date and the total interest savings. Compare at least two scenarios. Running the base case without extra payments alongside a scenario where you add 20 percent to your monthly payment usually reveals whether the acceleration is worth the cash flow impact. If the difference between the two scenarios only saves you four months and $800 in interest, you might want to direct those funds elsewhere instead of tightening your monthly budget.
Get the Full Details

What the Calculator Gets Wrong
Every calculator I have seen assumes simple daily or monthly accrual on the principal balance. Most home equity loans use a daily balance method with a 360-day year. The calculator will approximate this, but the approximation drifts over time. On a 15-year loan at 8 percent with a $50,000 balance, the daily-method error can accumulate to roughly $200 to $400 in total interest over the life of the loan. That is small, but it is real, and it means your calculator result is a floor, not an exact figure. Prepayment penalties are the biggest blind spot. Some home equity loans carry a penalty clause that charges you a percentage of the prepaid balance if you pay off a large portion within the first three to five years. I ran into this on a refinancing project last year. The calculator showed the borrower would save nearly $6,000 in interest by paying off the balance at month 30. The loan documents had a 2 percent prepayment penalty for any balance paid within the first five years. That penalty wiped out most of the projected savings and added another $1,000 on top. The calculator had no field for prepayment penalties because it cannot read your specific promissory note. The workaround is simple but easy to forget. Pull your original closing documents and search for the prepayment clause. It is usually buried in the early pages, not in the payment schedule. Check for any minimum balance requirements too. Some lenders require you to maintain a certain percentage of the original drawn amount as a condition of early payoff, and violating that can trigger default language.
Another limitation involves billing cycles and payment timing. If your lender processes payments on a 15th-of-the-month cycle and you make an extra payment on the 3rd, that extra money sits in a suspense account until the next billing cycle. During those 12 days, your balance still accrues interest on the full amount. The calculator does not model this delay. Over multiple extra payments per year, the cumulative effect of missed timing can add 1 to 3 months to your actual payoff date compared to the tool's projection. You can reduce this by scheduling extra payments a few days before your regular due date so they apply immediately to principal.
Pitfalls That Cost People Money
The most common mistake is assuming that making extra payments on a home equity loan automatically reduces payments on the first mortgage or primary debt. It does not. Each loan is a separate obligation. Paying down the second lien frees up some equity, but it does not change the payment amount or term of the first mortgage. The only way to affect the first mortgage is through refinance or a formal modification, and those carry their own costs that the calculator will not factor in. People also confuse payoff quotes with balance statements. Your monthly statement balance is not the amount required to pay off the loan today. Lenders charge interest daily, so the true payoff amount includes accrued interest from the last statement date through the payoff date. If you plan to close a payoff transaction, call the lender and request an official payoff quote. This is a two-business-day process at most lenders. Use that number, not the statement balance, as your reference point. The difference on a $40,000 loan can be $50 to $150 depending on your billing cycle. There is also a tax consideration that some calculators do not address. Interest on home equity debt is deductible under current IRS rules only if the funds are used to buy, build, or substantially improve the taxpayer's home. If you took the home equity loan for debt consolidation or general expenses, the interest may not be deductible. Paying it off early eliminates a deduction that could offset the savings from reduced interest. This is niche, but it matters for higher-income borrowers in the top tax brackets. A $5,000 interest saving might be partially negated by a lost $1,200 deduction if you are in the 24 percent bracket.
When the Calculator Is Useless
Variable-rate home equity products break the basic calculator model. If your rate adjusts quarterly or monthly based on the prime index, any projection beyond the current adjustment period is speculative. You can run the numbers on today's rate, and it will show you a reasonable estimate for the next six to twelve months. After that, the output is noise. The only way to model a variable loan is to build a spreadsheet that pulls in current index values and applies your contract's margin and caps. A standalone calculator cannot do this. I usually tell people with adjustable home equity loans to use the tool as a worst-case scenario bound rather than a prediction. Run it at the current rate and at the maximum allowed rate to get a range. That range is more useful than any single number. Lender-specific quirks also defeat generic tools. Some lenders apply extra payments to future installment dates rather than reducing principal immediately. Others require you to submit a separate request to designate a payment as principal-only. If your lender does this, your accelerated payoff projections will not materialize until you navigate their specific process. The calculator assumes a frictionless world where every extra dollar hits principal on the day you pay it. Reality is rarely that clean. The honest takeaway is that a Pay Off Home Equity Loan Early Calculator is a planning instrument, not a guarantee. It gives you a framework for decision-making. It tells you roughly how much faster you can get out of debt and what interest savings to expect. But the actual numbers depend on your loan documents, your lender's processing rules, and the interest rate environment. Use it to explore scenarios, not to set expectations with precision. Pull your paperwork. Verify prepayment terms. Call for an actual payoff quote when you are ready. The calculator gets you to the starting line, but the details in your contract determine where you finish.