How to Actually Use a Pay Off Mortgage Faster Calculator
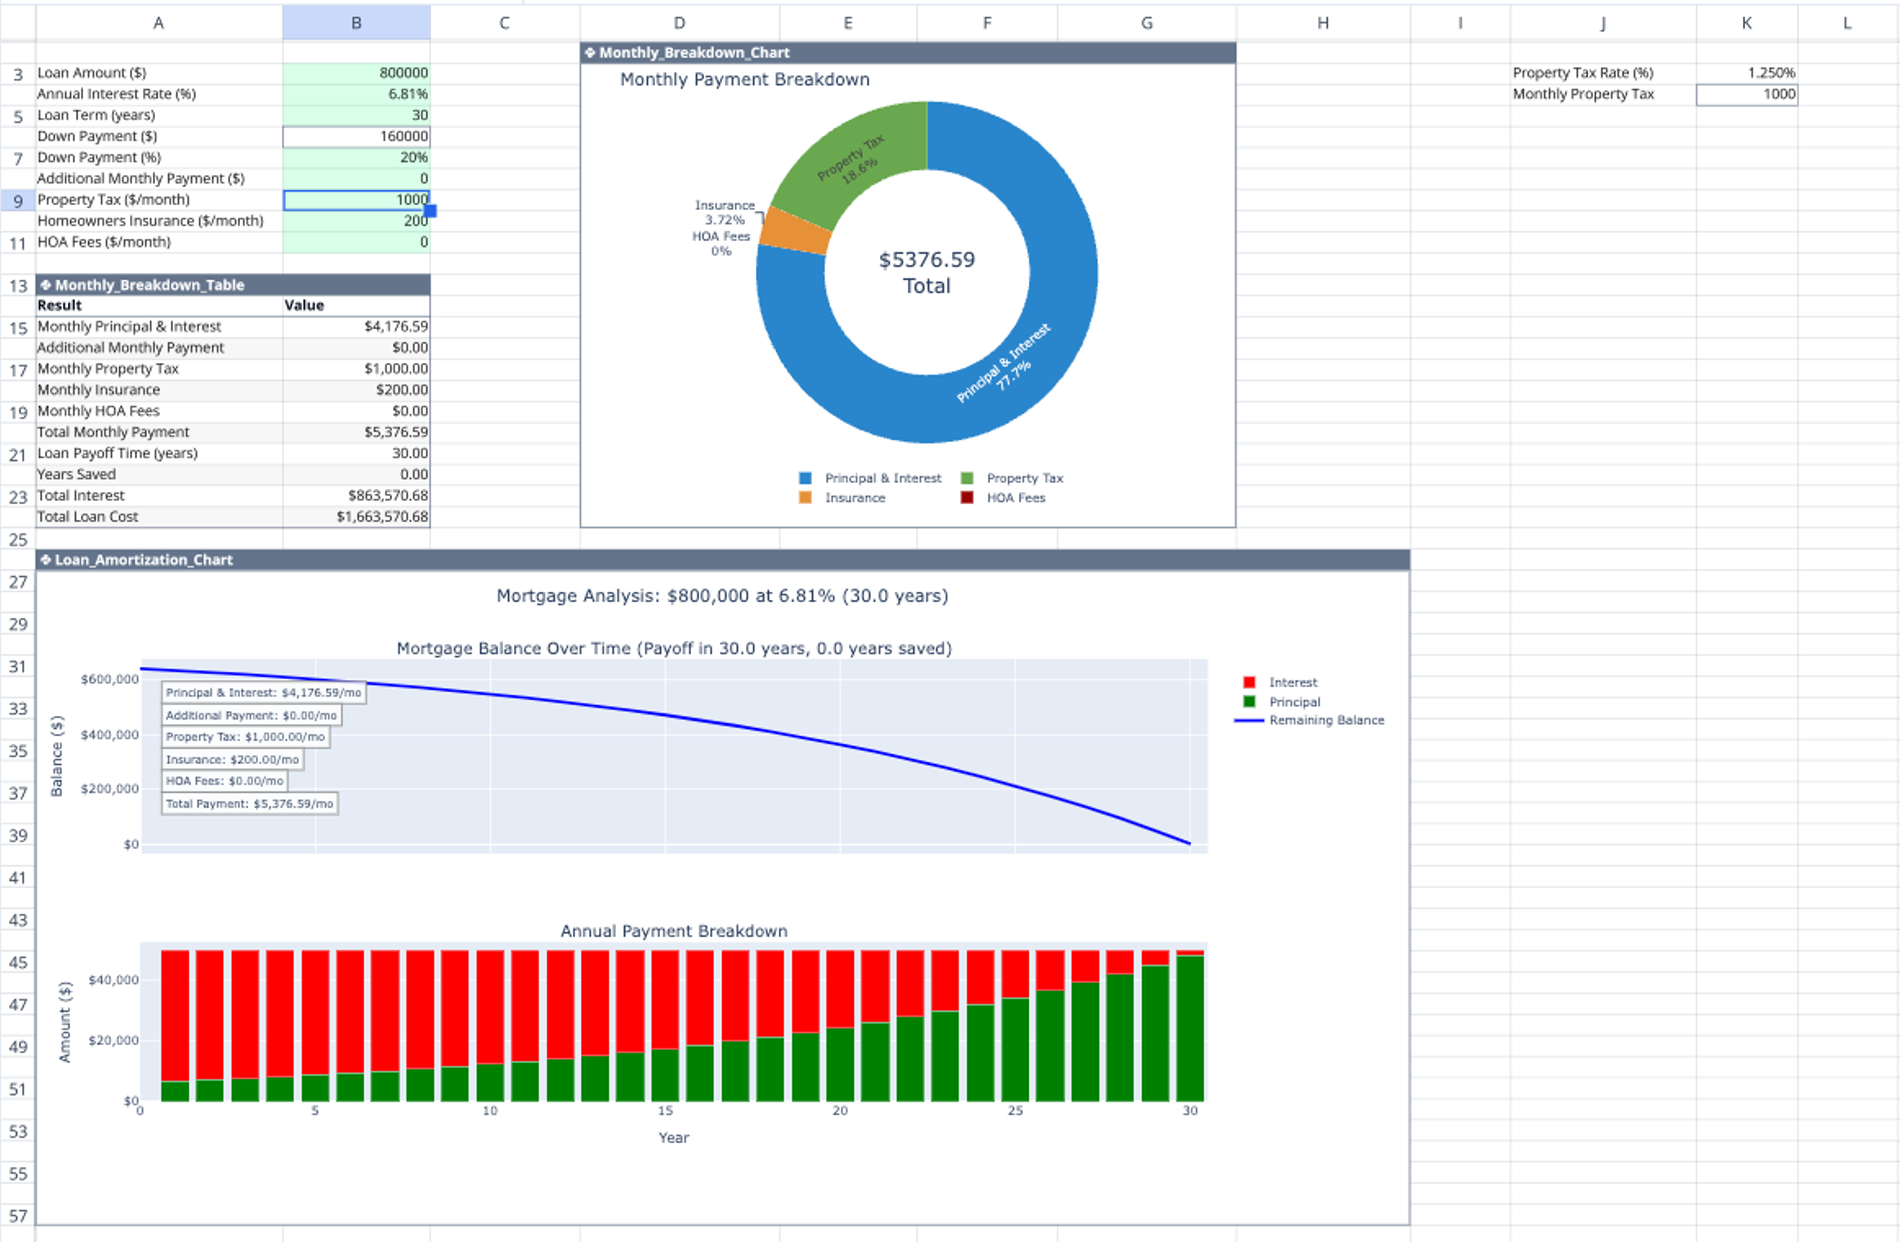
I've watched people obsess over mortgage payoff timelines for years, mostly because the standard amortization schedule makes it look like you'll be paying interest for decades. A Pay Off Mortgage Faster Calculator strips that nonsense away. You plug in your remaining balance, your interest rate, your current monthly payment, and optionally the extra amount you plan to throw at the loan each month. The tool recalculates the payoff date and shows you how much interest you save. That's it. But there are enough edge cases that trip people up, so I'm going to walk through the whole thing. The calculator runs two parallel amortization schedules. The baseline schedule uses your current payment and term to show the full path to zero balance. The accelerated schedule takes your same base payment, adds the extra amount you specify, and compounds those additional payments against the principal every single month. Because mortgage interest is calculated on your outstanding balance, cutting into principal faster creates a cascade effect — each month you owe slightly less interest, which means more of your regular payment goes toward principal, which means you pay down the loan even faster. It's a positive feedback loop, and the calculator displays it visually. Most tools also show you a side-by-side comparison of total interest paid under both scenarios. That number is the one people care about. On a typical $300,000 loan at 6.5% over 30 years, adding just $200 per month shaves about 5 years off the term and saves roughly $38,000 in interest. The exact figures depend on where you are in the loan lifecycle. Early on, that extra payment hits hard because most of your original payment was going to interest anyway. Near the end of the term, the same extra amount matters less because you're already paying down principal.
Running a Calculation: Step by Step
Open the calculator. Enter your current remaining principal balance — not the original loan amount. If you borrowed $350,000 three years ago and your balance is now $327,400, use $327,400. A lot of people still input the original figure and get confused when the results look wrong. Next, enter the annual interest rate as it sits on your note. Don't round it down to make the numbers look nicer. If your rate is 5.75%, type 5.75, not 5.5 or 6. Then put in your current monthly principal and interest payment. Some calculators ask for the total PITI payment including taxes and insurance — make sure yours is asking for just the principal and interest portion. Those extra $200 in escrow don't accelerate your payoff. Finally, enter the additional amount you want to pay each month. This is where most people freeze. They want to pay off the house faster but don't know what number is realistic. I usually tell people to start small. $100 extra per month is something most budgets can absorb without major lifestyle changes. If you get a raise or bonus, bump it up. The calculator will update instantly. Once all fields are filled, hit calculate. You'll get a new payoff date, total interest paid under the accelerated schedule, and the interest savings compared to staying on the original path. Some calculators also break down how each extra dollar compounds over time, which is useful if you're trying to explain the concept to a skeptical spouse.
A Real Problem I Ran Into With These Calculators
Here's the thing nobody tells you: most online calculators assume your extra payment happens on the same day every month and gets applied immediately to principal. In reality, mortgage servicers have different policies about how they handle partial payments or extra principal chunks. I ran into this when a client of mine was making $500 extra payments every January and February — his tax refund window — and the calculator kept showing him a payoff date that was months earlier than what actually happened. The issue was that his servicer treated those large irregular payments as escrow adjustments rather than principal reductions because they didn't meet the minimum extra payment threshold for principal-only processing on his particular loan type. He ended up having to call them and explicitly request that each payment be designated as principal-only, which took three months and a few frustrating phone calls to sort out. The workaround was straightforward once I knew it. I had him enter his extra payment as a smaller but consistent monthly amount instead of large biannual bursts, then set up automatic payments for that amount. The calculator result aligned almost perfectly with what his actual payoff schedule looked like after the change. If you're making irregular extra payments, either adjust your input to match your servicer's actual processing rules or just stick to consistent monthly additions. The math works cleanly when everything is predictable.
Get the Full Details

Counter-Intuitive Things Beginners Miss
First, making extra payments toward a high-interest mortgage isn't always the best move mathematically. If your mortgage rate is 3.5% and you have investment accounts earning 7-8% on average, pouring extra money into your mortgage is essentially locking up capital at a guaranteed 3.5% return. That's a suboptimal allocation for most people. The calculator will show you the payoff timeline, but it won't tell you whether that timeline actually makes financial sense given your broader portfolio situation. Run the numbers against your other debt obligations too. Credit card debt at 19% should always be wiped out before you think about accelerating a 4% mortgage. Second, the shape of your payoff acceleration curve matters more than people realize. Making one large extra payment annually — say, your entire tax refund — is less efficient than spreading that same total amount across 12 monthly payments. Why? Because each dollar of principal reduction starts saving you interest from the moment it's applied. A $3,000 payment made in January sits reducing your balance for 12 months. The same $3,000 split into $250 monthly payments has your principal dropping incrementally throughout the year, so you're saving slightly more interest overall. The difference isn't massive — usually a few hundred dollars on a typical loan — but it's real and it compounds over time. Third, some calculators don't account for biweekly payment structures, which are another common acceleration strategy. Instead of one monthly payment, you make half that amount every two weeks. You end up making 26 half-payments per year, which equals 13 full payments instead of 12. That one extra payment per year goes entirely to principal and can knock a few years off a 30-year loan. If your calculator doesn't support biweekly mode, just divide your monthly extra payment by two and double the frequency in your head.
Where These Calculators Fall Short
The biggest limitation is that they assume your interest rate is fixed. If you have an adjustable-rate mortgage, the calculator becomes useless past the initial fixed period unless you also estimate what your rate might do. ARMs can reset up or down, and a rate jump from 4% to 7% would completely change your payoff timeline. The tool can't predict that for you. Another gap: most calculators ignore prepayment penalties. A handful of loans, particularly some jumbo mortgages or investor properties, carry penalties if you pay down principal faster than a certain threshold. Check your loan documents for a prepayment clause before you start hammering your balance. If one exists, you might need to structure your extra payments to stay within the allowed window, which changes the math significantly. Calculators also don't factor in tax implications. Mortgage interest deductions on Schedule A can be worth something, especially in the early years of a loan when interest dominates your payment. Paying off your mortgage faster means less deductible interest each year. For someone in a high tax bracket with a large loan, that deduction could represent thousands in annual tax savings. The calculator won't tell you to weigh that against the interest you're saving. Do the math yourself if it matters to your situation.
What to Look for in a Good Calculator
Pick one that shows an amortization schedule, not just a summary. A list of month-by-month balances lets you verify the numbers and spot inconsistencies. It also helps if you ever need to dispute a statement from your servicer or explain the payoff amount to a refinance lender. Look for a tool that lets you compare multiple scenarios — different extra payment amounts side by side. Being able to see that $150 extra saves $22,000 in interest while $300 extra saves $38,000 helps you pick a number that fits your budget without feeling arbitrary. The best calculators also let you model irregular payments, not just fixed monthly additions. Life isn't predictable. You might get a promotion one year and want to boost payments, then have a rough year and pull back. A rigid calculator that only handles one scenario won't capture that. Find one where you can adjust the extra payment each month or enter custom payment dates and amounts.

Getting Started
Open any Pay Off Mortgage Faster Calculator online, enter your real numbers, and run the baseline and accelerated scenarios. Compare the payoff dates and interest totals. Then decide whether the accelerated path fits your cash flow. If it does, set up the automatic additional payment with your servicer before you forget. Most servicers have a portal where you can schedule recurring extra principal payments. Do it there rather than sending separate checks each month — it removes the human error factor and keeps the compounding clean. If your servicer doesn't support automated extra payments, write the extra amount on a separate check marked principal only and mail it on the same day each month. Consistency is what makes the math work.