How Paying Extra On A Mortgage Actually Works (And What Most Lenders Will Try To Do Anyway)
You send $400 extra each month to your mortgage servicer and think you've knocked $400 off your principal. Three statements later, your balance looks exactly the same. The payment wasn't stolen, it wasn't misapplied, it just sat there waiting to offset your next regular due date. That's what happens when you don't tell your lender explicitly where the money should go. Most servicing platforms default to treating any additional payment as a prepayment of future installments rather than a direct principal reduction. This matters because a payment applied to future interest doesn't change your amortization schedule. A principal payment does, and it does so immediately. The difference between those two paths can add thousands in total interest cost over the life of the loan.
The Mechanics of Paying Extra On A Mortgage
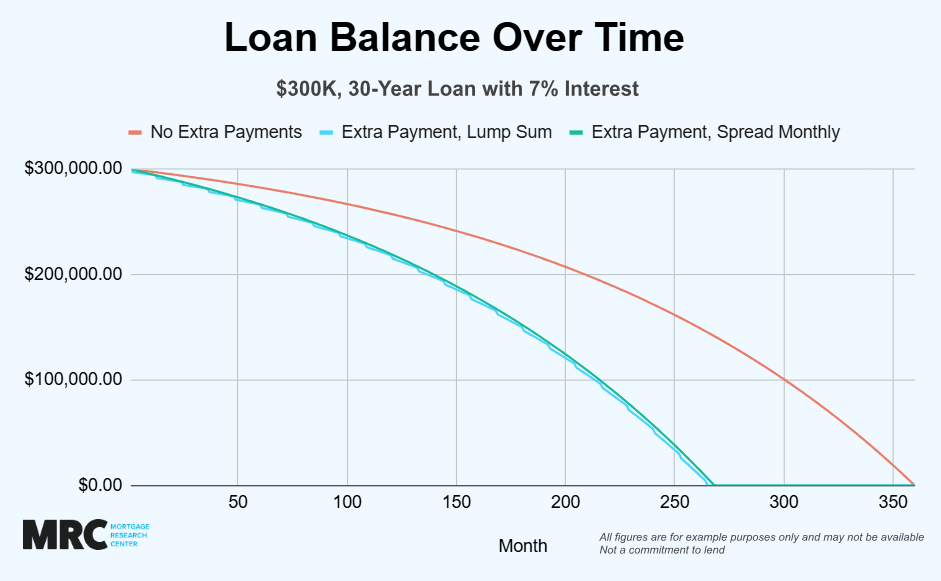
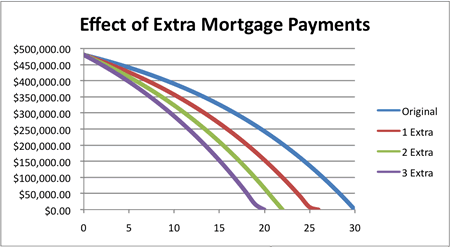
There are three ways this actually plays out in practice. The first is the one-click extra payment through your lender's portal, which is convenient until you realize it's being held as an undesignated credit. The second is a paper check with a written notation that says "principal only" attached to your regular payment. The third is a direct phone call where you request the payment be applied to principal and get a confirmation number. Option three is the only one that reliably produces results without follow-up. Once the payment clears as principal, the math changes your amortization table. Your next scheduled payment stays the same dollar amount, but a larger share goes to principal and a smaller share to interest. The loan term shortens. Total interest paid decreases. This is the basic mechanism, and it's why people bother with it at all. The catch is that your specific loan type determines how much this actually helps. A fixed-rate 30-year conventional loan with a 6.5% rate will respond very differently than an adjustable-rate mortgage with a cap on payments, or a government-backed loan with unique prepayment restrictions. Before you set up any recurring extra payment, pull your original promissory note and check what it says about prepayments. Some loans have a clause that limits the amount you can prepay in a given year without penalty or special notice.
What Nobody Tells You About Principal Payments
Here's the part most calculators skip: paying extra is only valuable if you hold the loan long enough for the interest savings to compound. If you refinance in three years, most of those extra payments go nowhere fast because the new loan wipes out your principal balance anyway. You've spent money you could have invested elsewhere, and your new rate might be lower. The math flips depending on how long you plan to stay in the home. Another detail that trips people up is the timing of when your servicer applies the extra payment. Some lenders take 30 to 45 days to reflect a principal-only payment on your statement. During that window, you're technically carrying an extra balance that could earn interest in an investment account instead. It's not a dealbreaker, but it's worth factoring in if you're optimizing for the absolute best outcome. I also learned about a reporting nuance that almost cost me a deduction. When you make extra principal payments that exceed certain annual thresholds, your servicer is supposed to send you a Form 1098 that reflects the total interest paid, but the form sometimes underreports if large principal prepayments were made mid-year. I caught this after filing and had to submit a corrected statement to the IRS with my own records. Always reconcile your 1098 against your actual payment history before you file, especially if you've been making consistent extra principal payments.
Get the Full Details

A Real Problem I Faced And How I Fixed It
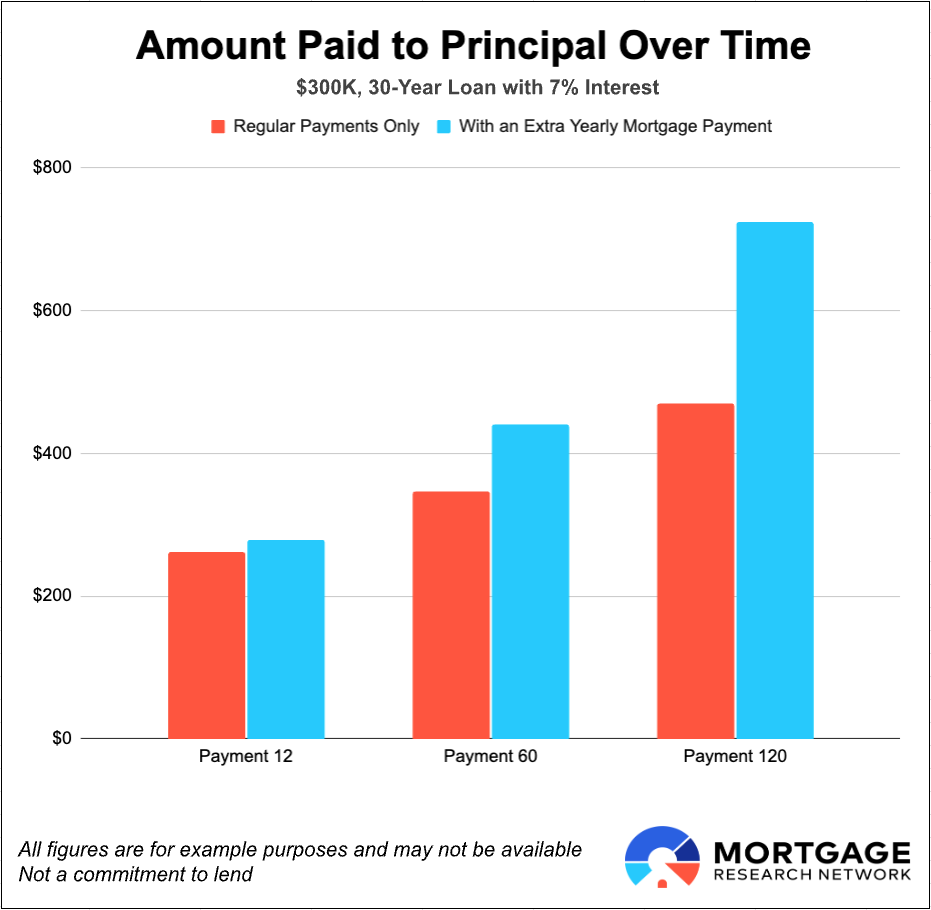
Three years into my mortgage, I set up a recurring automatic extra payment of $300 per month through the lender's online portal. Everything looked fine on the confirmation screen. Then I pulled my annual statement and noticed my principal balance hadn't moved at all. I called the servicer and discovered the automatic payment was being queued as a prepayment of future installments, not applied to principal. The portal interface made it look like the payment went toward the loan, but the actual allocation was somewhere in the void between "received" and "applied to scheduled payments." The workaround was simple but frustrating. I had to switch from the online portal to mailing a physical check with a handwritten notation on the memo line that said "principal only" and calling the servicer afterward to confirm receipt and correct application. I started keeping a log of every extra payment with the date, amount, and confirmation number. Six months later, the pattern was clean. My principal was dropping by roughly $280 a month, and the amortization shortened by about four years compared to the original schedule. This isn't a unique edge case. It happens frequently enough that I recommend against relying solely on automated extra payments through any major servicer. Automation is fine for your regular payment. For anything beyond that, use manual processes with clear written instructions and confirmation.
When Paying Extra Doesn't Make Sense
There are scenarios where throwing extra money at your mortgage is the wrong move. If your loan is a government-backed FHA or VA loan with specific prepayment penalties in the first few years, you'll eat into your savings before you see any benefit. If you're sitting on high-interest credit card debt at 18%, paying down a 6% mortgage is backwards math. And if you have access to a 401(k) match or other tax-advantaged investment vehicle that returns more than your mortgage rate, the opportunity cost of prepaying can be significant over time. Another limitation people overlook is liquidity. Money paid into your home equity is tied up. You can access it through a refinance or HELOC, but both come with closing costs and qualification requirements. If you face an emergency and your extra payments have built up several thousand dollars in equity, you can't just withdraw it like a savings account. That's a real constraint for people who value financial flexibility. The biggest bottleneck with the strategy is simply consistency. Most people set up extra payments and then drop them when something unexpected happens. The interest savings come from steady, predictable overpayments, not sporadic bursts. If your income is variable, consider a different approach like putting extra funds into a separate high-yield account and making a larger lump-sum payment once a year rather than trying to maintain monthly overpayments that you might have to cancel.
Practical Steps If You Decide To Proceed
Call your servicer first and ask three questions: Can I designate a payment as principal-only? How long does it take to reflect on my statement? Do I have any prepayment restrictions on my loan? Get the answers in writing if possible, or at least note the representative's name and the date of the call. Then set up your extra payments using a method that requires explicit instruction. A mailed check with a clear memo line is the most reliable. If you use an online system, take a screenshot of the confirmation and verify the allocation on your next statement. Don't assume the portal did what it looked like it did. Track your principal balance quarterly. If it's not dropping by roughly the amount you intended, something is wrong and you need to escalate it. Most servicers will correct the error, but they won't fix it unless you notice and report it. This is the part that requires attention, not just setup.
The strategy itself is sound. The execution is where most people lose ground. Paying extra on your mortgage is one of those things that looks simple until you actually try it, then turns out to be a series of small administrative tasks that determine whether it works or not. The math is straightforward. Getting the money to actually reduce your principal is the harder part.