Why You Should Stop Guessing About Extra Mortgage Payments
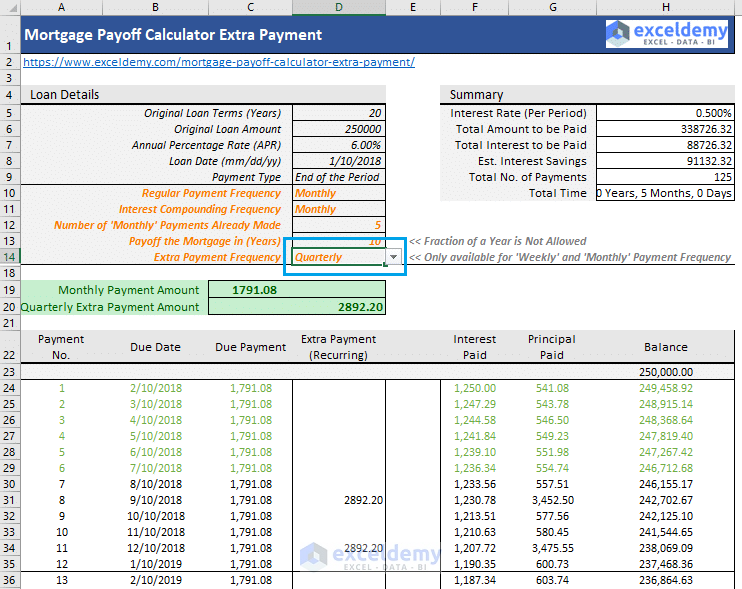
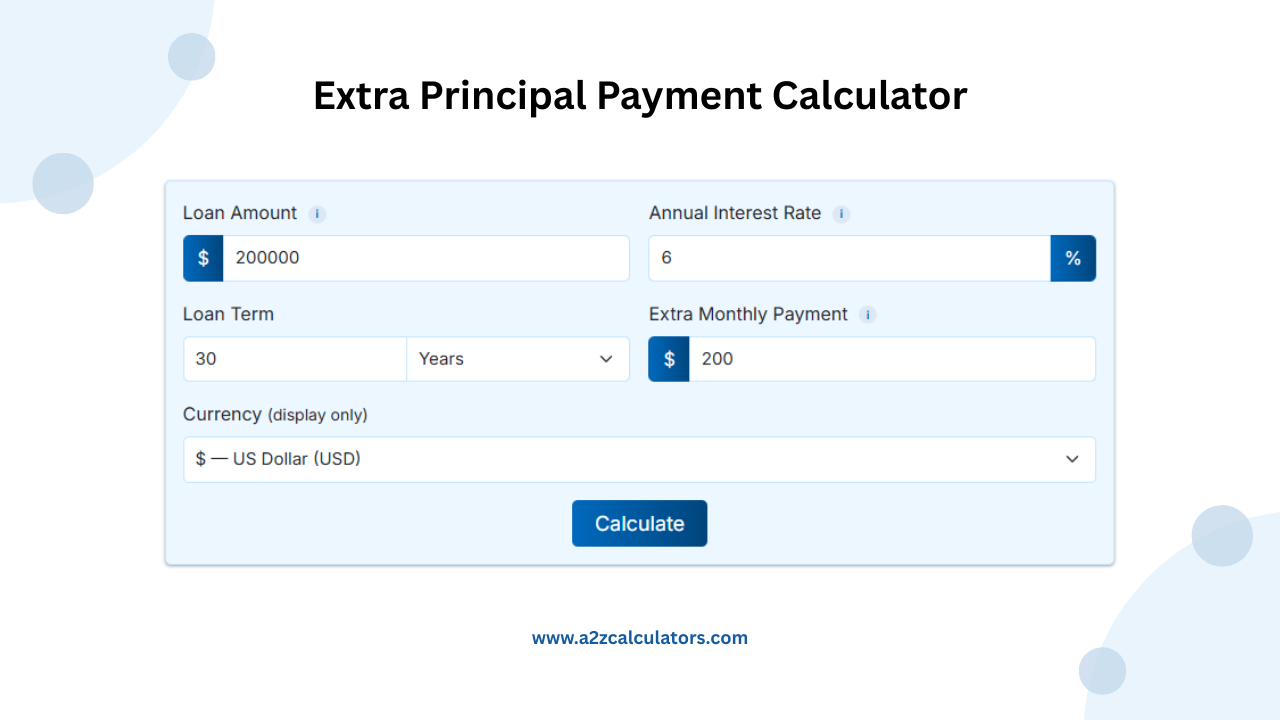
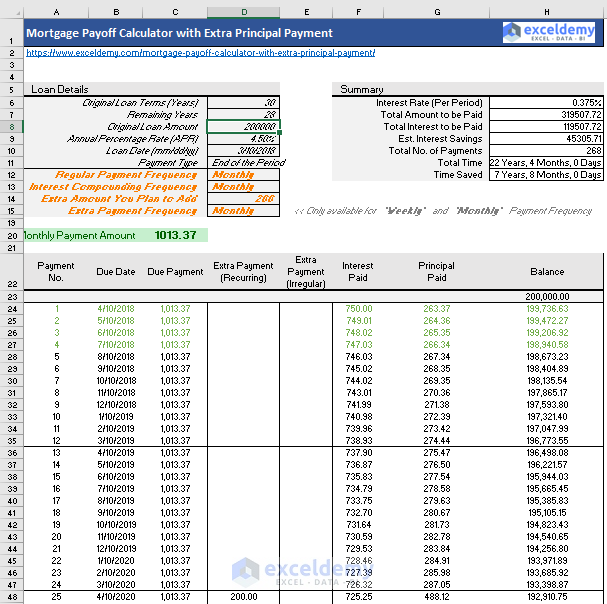
I spent three years working in mortgage servicing before moving to the advisory side, and I still see people making the same mistakes with extra principal payments every single week. Most of them don't even know their loan has prepayment penalties or that their lender is applying their extra payment to the next escrow due date instead of reducing principal immediately. This guide is about making sure your extra payment actually does what you think it does.How a Paying Extra On Mortgage Principal Calculator Actually Works A paying extra on mortgage principal calculator takes your current loan balance, interest rate, remaining term, and the extra amount you want to pay each month or as a lump sum, then shows you the new payoff date and total interest savings. That sounds straightforward, but the devil is in the implementation details that most online calculators ignore completely. The basic formula they're all working from is straightforward amortization math. Your regular monthly payment gets split between interest and principal based on the remaining balance. Interest for the month equals your outstanding balance multiplied by your annual rate divided by 12. Whatever is left of your payment goes toward principal. When you add an extra payment, that entire extra amount goes straight to principal, which then reduces the interest calculated on the next cycle. Over time, this creates a compounding effect where you pay less interest each month, and more of your regular payment goes to principal. Most free calculators online don't account for how your lender actually processes extra payments. They assume your extra money hits the principal on day one of the month. In reality, some lenders take 30 to 45 days to apply it, and during that window you're still paying interest on the full balance. Here is a specific problem I ran into with a client last year that illustrates why this matters. He was using a generic online calculator and thought he was saving $47,000 in interest over 15 years by paying an extra $500 per month on his 30-year fixed at 6.25%. The calculator showed a payoff in 14 years and 3 months instead of 30. When I pulled his actual amortization schedule from the servicer's portal, the real savings came out to $31,200 and the payoff stretched to 17 years and 8 months. The discrepancy came from two things: his loan had a prepayment penalty structure where any payment exceeding 20% of the scheduled principal in a given year triggered a 2% fee on the excess amount for the first five years of the loan, and his servicer was applying his extra $500 to escrow reserves instead of principal because he hadn't set up a separate principal-only payment designation on his account. The workaround was simple but not obvious. I had him send a written payment instruction to his servicer specifying that the additional $500 should be applied solely to principal, then I called the loss mitigation department to confirm they'd flagged it correctly in the system. We also waited until after the fifth anniversary of the loan to ramp up the extra payments, which eliminated the prepayment penalty issue entirely. The recalculated savings with those adjustments came to $41,800, which is still meaningful but nowhere near the original estimate.
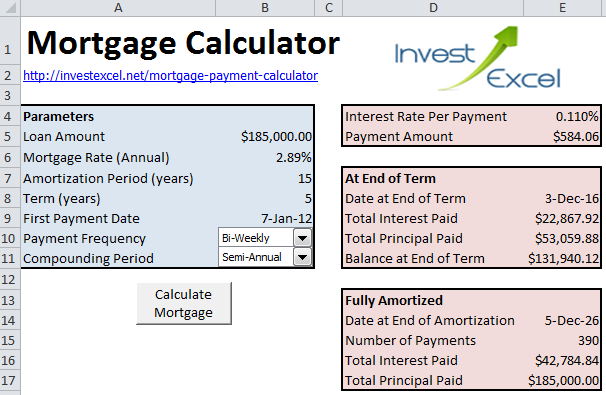
Here are the settings you need to look for when using any calculator: make sure it lets you specify whether the extra payment is monthly or occasional, whether it's a one-time lump sum or recurring, and whether it occurs at the beginning or end of each payment cycle. A payment made on day one versus day thirty of the cycle can shift your total interest by a few hundred dollars over the life of the loan, and some calculators just assume the payment happens at the wrong time by default. The most useful calculators also let you model different scenarios, like paying an extra $200 per month for the first five years and then stopping. Some people do this to build a buffer early and then free up cash later. A proper calculator will show you exactly how much that strategy costs versus just keeping the extra payment going for the full term.