Interest-Only Payment Calculators — How They Actually Work and Where They Break
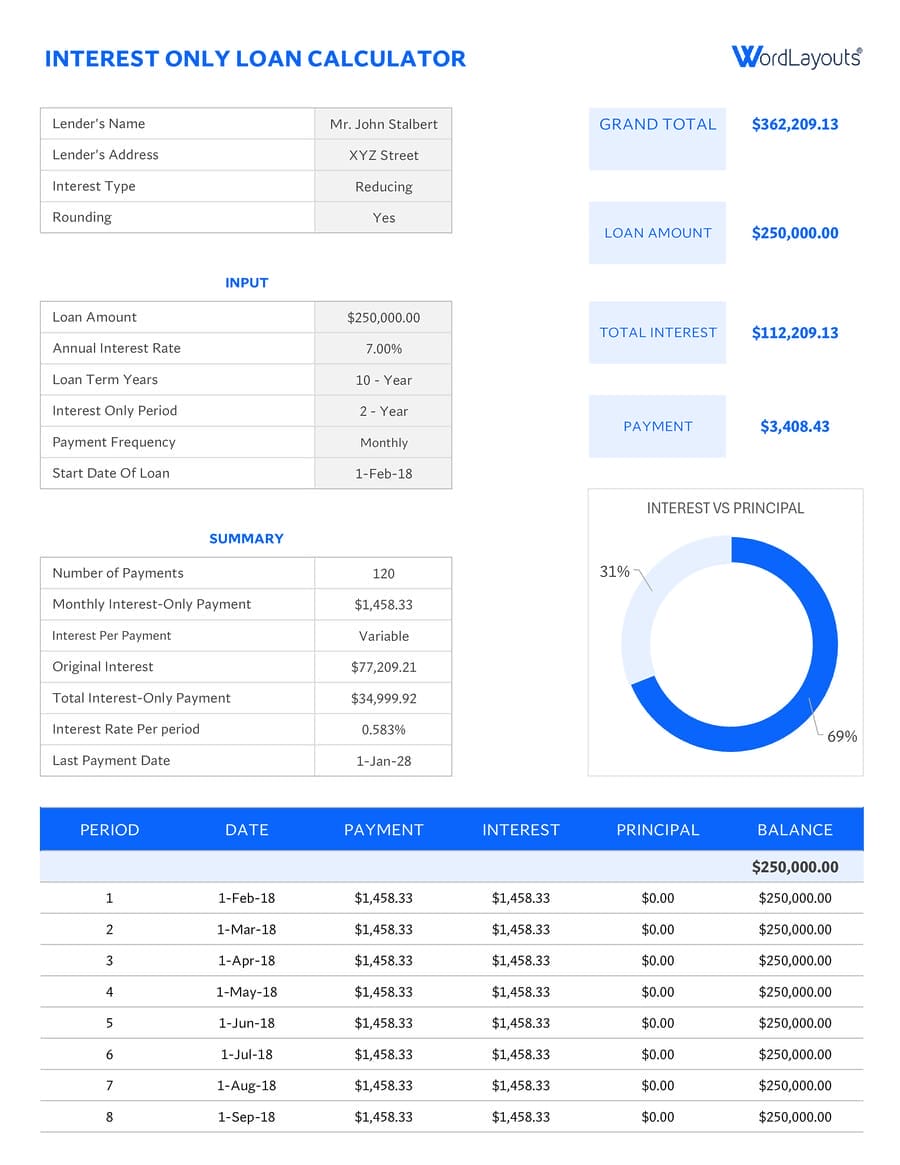
Most people grab a Payment Calculator Interest Only tool because they want to see the lowest possible monthly number before committing to a loan. That is not always the right question to ask. The monthly payment is only one slice of the problem. The real issue is what happens at the end of the term, how the principal balance behaves, and whether the loan structure makes sense for the borrower's cash flow timeline.I have run these calculations for years, mostly for investors and business owners who pull money out of properties for renovations or cash-out refis. The formula itself is straightforward: divide the annual interest rate by twelve to get the monthly rate, then multiply that by the outstanding principal. A $500,000 loan at 7.25% annually gives you a monthly interest payment of $3,020.83. That number will never change as long as the principal stays the same. But that is where things get messy in practice. The basic workflow is simple. Enter the loan amount, select interest-only as the payment type, input the rate, and set the term. The calculator returns your monthly obligation. Done. But I recommend doing one additional step that most free calculators skip entirely: calculate the balloon payment that hits at the end of the term. A lot of people do not realize their monthly payment does not include any principal reduction. At year five, if you have not made extra payments, you still owe the full $500,000. If you planned to sell the property by then, fine. If you did not plan to sell, you are looking at a refinancing question that might not have a friendly answer depending on market conditions. I encountered a specific edge-case recently that illustrates this well. A client was using a standard online calculator and saw a monthly payment of around $2,400 on a $400,000 IO loan. He felt good about it. Then his lender told him the loan had a six-month IO period followed by full amortization. The calculator showed $2,400 forever. The real payment after month six jumped to nearly $3,200. I had to walk him through recasting the entire schedule, which took about twenty minutes once I pulled up the amortization table. The workaround is to ask your lender for the exact IO period length and the start date of the amortizing phase before you rely on any calculator output.
Counter-Intuitive Things About Interest-Only Loans
Here is something most beginners miss. An interest-only loan can sometimes be cheaper overall than a fully amortizing loan, even though you are paying less principal early on. This happens when you can invest the difference between the IO payment and what a traditional payment would be at a higher return rate than the loan interest. It is not a universal rule. It depends entirely on your investment capacity and the spread between your loan rate and your portfolio return. I had a client who compared a 6.5% IO loan against a 6.25% fully amortizing loan and chose the higher rate because he could deploy the freed-up cash into a rental property that cash flowed positive within eighteen months. The math worked out in his favor. It would not have worked for someone who spends every extra dollar as soon as it arrives. Another hidden factor is the impact of rate adjustments. Many IO loans are adjustable. Your payment starts low because the initial rate is teaser pricing. After the adjustment period, the rate resets to a higher index value. A calculator that shows only the current monthly payment will make the loan look better than it actually is over the full life of the product. Always run the calculation at the fully indexed rate, not just the introductory rate. The difference between a 5.5% teaser and a 7.0% indexed rate on a half-million dollar loan is about $625 per month. That is not a rounding error.
Practical Pitfalls and When IO Calculators Fail You
The biggest limitation of any Payment Calculator Interest Only tool is that they do not account for tax implications, insurance, or escrow. They show pure principal and interest. If you are budgeting for a rental property, you need to add property taxes, homeowners insurance, and possibly HOA fees to get the real monthly out-of-pocket number. Some lenders bundle these. Most do not. The monthly payment on the calculator is only the debt service portion. Another scenario where IO calculators break down is when the borrower makes partial principal payments during the IO term. If you pay down $50,000 of principal mid-term, your interest payment drops accordingly. Most basic calculators assume zero principal reduction. They will not adjust dynamically unless you manually re-enter the new balance. I usually keep a separate spreadsheet with the declining balance tracked month by month because the calculator alone does not give you that visibility. It takes about ten minutes to set up and saves you from being surprised when you need to renegotiate or refinance. There are also cases where an interest-only structure is outright harmful. If you are buying a primary residence and plan to live in it for ten or fifteen years, a IO loan means you are not building equity through mandatory principal reduction. You are relying entirely on property appreciation to grow your stake. In a flat or declining market, you could end up underwater even after five years of payments. A traditional 30-year fixed is almost always the safer bet for owner-occupants. IO loans shine for investors with clear exit strategies or for businesses that need cash flow flexibility for a defined period.
Get the Full Details
What to Check Before Trusting the Number
Before you finalize any loan based on a calculator output, verify three things. First, confirm whether the loan has a prepayment penalty. Some IO products charge a fee if you pay off the balance early, which defeats the purpose of making extra principal payments when rates drop. Second, check if there are points or origination fees that are rolled into the loan amount. A $500,000 loan with $10,000 in fees rolled in becomes a $510,000 interest base, and the calculator may not show that adjustment unless you input the exact financed amount. Third, look at the recast option. Some lenders allow you to recast the loan after a large principal payment, lowering your future payments even after the IO period ends. This feature is not available on every product and should be confirmed before you sign. I do not recommend any specific calculator brand. The free tools online vary widely in accuracy, and some do not handle adjustable rates or balloon structures correctly. What matters is understanding the inputs and questioning the outputs. Run the numbers at the fully indexed rate. Add the exit scenario. Write down what you would do if the property did not appreciate or if you could not sell within the IO window. That is the exercise that actually protects you, not the monthly payment number itself.