
The Math Behind Killing Debt Faster
Most people misunderstand how extra payments work on amortizing loans. The core mechanism is straightforward. When you pay $200 over your minimum, that $200 hits principal directly. It does not get recycled into the next month's payment. The remaining principal balance drops immediately, which means the next interest calculation uses a smaller number. Interest is computed on outstanding principal at the end of each period. Less principal equals less interest next cycle. The standard payment formula uses present value of an annuity: PMT = P × r × (1+r)^n / ((1+r)^n - 1)
Where P is the original principal, r is the periodic rate, and n is the number of payments. That formula gives you the baseline. Extra payments bypass it entirely because you are actively shrinking P mid-stream. The calculator simply tracks each period's remaining balance, subtracts the regular principal portion, then subtracts the extra amount on the row where it occurs. The next period compounds from the new, lower balance.
How to Build a Payment Calculator With Extra Payments
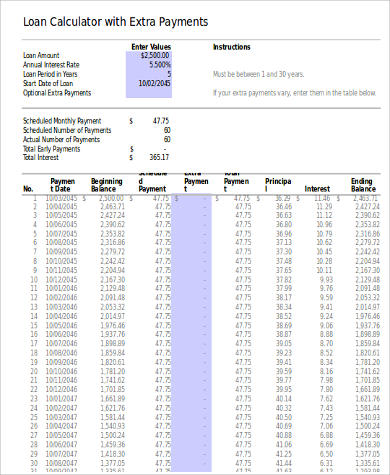
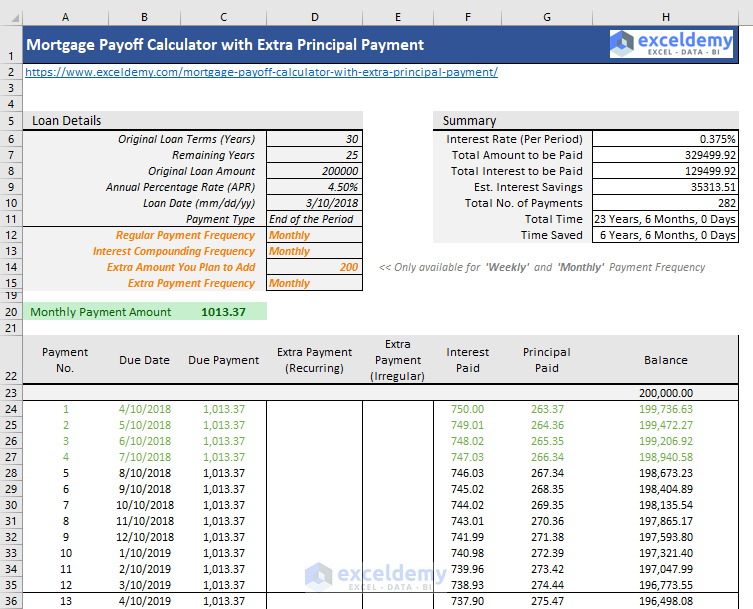
I spent years rebuilding payment calculators in Excel because nothing out of the box handled irregular extra payments correctly. Here is what works without the headache. Create columns for: beginning balance, regular payment, extra payment, total payment that period, principal portion, interest portion, ending balance. The principal portion equals total payment minus interest. Interest equals beginning balance times the periodic rate. Ending balance equals beginning balance minus principal portion. Carry ending balance into the next row. That is it. One loop. Here is a concrete example. You have a $200,000 mortgage at 6.5% annual, 30 years. The regular payment comes to roughly $1,264.14. You decide to throw an extra $300 every month starting in month 6. The spreadsheet recalculates from that point onward using the new lower balance. Total interest drops from about $255,090 to roughly $193,000. You save around $62,000 and shave about 7 years off the term. The numbers shift depending on when you start the extra payments, how large they are, and what the interest rate is. Starting year 15 instead of year 1 changes everything. By then, most of your payments are already principal-heavy, so the marginal impact of extra dollars is smaller. This is where most people trip up. They run the calculator once, see a big savings number, and assume it applies linearly. It does not. The relationship between extra payment timing and total interest savings is highly non-linear because interest compounds on a shrinking base. Throwing $500 extra in year one of a 30-year mortgage is worth dramatically more than throwing $500 extra in year twenty.
Get the Full Details
Edge Cases That Break Most Calculators
I learned this the hard way. A client insisted his loan software showed a $40,000 savings from extra payments. I rebuilt the schedule in a raw spreadsheet and found the real number was closer to $21,000. The software was applying his extra payment to the next scheduled payment instead of reducing principal immediately. He was effectively prepaying a month he would have paid anyway. The extra money vanished into normal amortization with zero acceleration. I switched his calculation to a direct principal reduction model and the numbers aligned with reality. Always verify what your tool is actually doing with the extra amount. Another silent problem is the difference between prepayment models. Some calculators assume the extra payment shortens the term while keeping the same regular payment amount. Others recalculate the payment based on the new shorter term. These produce meaningfully different outcomes. The first model keeps your cash flow fixed. The second frees up monthly capacity. Pick one approach and stick with it. Mixing them creates confusion fast. Frequency matters too. Making $100 extra per week instead of per month is not the same as making $400 per month. Weekly payments hit principal sooner because interest compounds monthly. If your calculator supports biweekly or weekly extra payments, it needs to adjust the compounding assumption correctly. Most free online tools do not.
When This Approach Falls Apart
Extra payment calculators assume a few things that are not always true. First, they assume you can actually make the extra payment every period. Miss three months in a row and the projected savings evaporate. Second, they ignore prepayment penalties. Some mortgages, particularly certain government-backed loans or jumbo products, charge penalties if you pay down principal above a threshold in the first few years. A 1% penalty on a $50,000 extra payment is $500 you never see back. Factor that in before you commit. Third, they do not account for opportunity cost. Money put toward a 6.5% mortgage is money not earning returns elsewhere. If your alternative investment yields 8% after tax, the mortgage extra payment is actually costing you net. The calculator will still show interest savings, but your overall wealth trajectory may be worse. Run both sides separately before deciding. High-interest debt behaves differently. Credit cards often have no fixed amortization schedule. An extra payment there reduces the balance, yes, but the compounding is daily rather than monthly. A Payment Calculator With Extra Payments designed for installment loans will understate the benefit on revolving debt. Use a different model for that. Daily compounding changes the math enough that monthly amortization spreadsheets give you optimistic numbers.
Practical Implementation Tips
Start with a spreadsheet for anything beyond simple cases. It takes about 20 minutes to set up and gives you full visibility into every assumption. Use absolute cell references for the loan amount, rate, and term. Lock those so you can swap inputs without breaking formulas. Keep the amortization schedule unencrypted so you can audit individual rows when the numbers look wrong. Track the cumulative principal paid versus the original schedule. The divergence point shows you exactly when extra payments start mattering. Most schedules show a flat line for the first 18 months before the gap becomes visible. That is normal. Interest front-loading means principal reduction is slow at the start regardless of what you do. If you must use a web tool, pick one that lets you input irregular extra payment dates and amounts. Many calculators only allow a fixed monthly extra. Life is not fixed monthly. A medical bill, a bonus, a tax refund—these hit on unpredictable schedules. The tool should reflect that reality.
One more thing nobody mentions. Refinancing after making extra payments can undo months of work. If you refinance and roll the remaining balance into a new 30-year term, you reset the clock. The extra payments you made earlier only affected the old loan's tail end. Run a break-even analysis on the refinance before you pull the trigger. Compare total interest paid under both scenarios including closing costs. The formula itself is not complex. The behavior of real loans is. Build the schedule manually if you need accuracy. Trust the spreadsheet over the website. Verify the prepayment treatment. Check for penalties. Then use the numbers to make a decision that actually fits your cash flow.


