Understanding PEP Stock: A Practical Look at PepsiCo as an Investment
PEP is the ticker for PepsiCo Inc., one of those companies that has been around long enough that its quarterly earnings calls feel like annual traditions. The stock sits at the intersection of consumer staples and snack foods, which means it tends to move slower than tech plays but holds up better when the market gets spooked. That isn't a compliment to its stability so much as a description of its volatility profile. PepsiCo owns Frito-Lay, Gatorade, Quaker, and a whole portfolio of beverage brands including Pepsi itself. The company reports revenue in the range of $80 to $90 billion annually. For investors, the two metrics that actually matter are free cash flow generation and the payout ratio on dividends, because the stock has historically returned value to shareholders through both channels rather than relying on one or the other. One thing beginners consistently miss is how the international segment distorts year-over-year comparisons. When the dollar strengthens, PepsiCo's overseas revenue converts to fewer dollars on paper, and management will often walk you through "constant currency" figures in the earnings release. Those constant currency numbers tell you what is actually happening with sales volume. The reported numbers tell you what happens when currency fluctuations hit. I always look at both and then make a decision based on the constant currency data, because that's the real business trend.
What to Watch Before Buying
The input cost of commodities, particularly aluminum for cans and agricultural products for snacks, moves directly through PepsiCo's margins. If corn prices spike or aluminum futures run up, the company either absorbs the hit or passes it through to consumers through price increases. The market usually prices in the expectation of a pass-through, but there are delays. During the 2022 inflation surge, PepsiCo raised prices across multiple categories, and the stock got caught in a weird spot where analysts were watching volume decline even as revenue climbed because of those price hikes. Revenue looked fine. The underlying demand story was slightly weaker than the top line suggested. Another thing nobody talks about enough is the debt load relative to cash flow. PepsiCo carries meaningful leverage, but it is manageable debt for a company of this size. The real question is whether the free cash flow can support the dividend while still funding share buybacks and capital expenditures. Check the capex line item. If it has been declining while the dividend has been growing, that's not automatically a red flag, but it means the company is prioritizing shareholder returns over expansion, which is a specific strategic choice rather than a neutral fact.
Dividend History and Yield Expectations
PEP has a Dividend King status, meaning it has increased its dividend for at least 50 consecutive years. The current yield typically lands somewhere between 2.5 and 3.2 percent depending on the share price. For income-focused investors, that is a reasonable yield for a stock that also offers some growth potential, though calling it a growth stock would be inaccurate. The yield will compress if the stock price rises faster than the dividend increases, and it will expand during market selloffs when everyone rotates into defensive names. The payout ratio usually sits between 60 and 70 percent of earnings, which is on the higher side for aDividend King. That leaves less room for error if earnings contract. I have seen people treat the long dividend increase streak as a guarantee of future performance, which is a logical fallacy. Past increases do not create future increases. Management announces them quarterly based on current conditions.
Get the Full Details
How I Approach Position Sizing for PEP
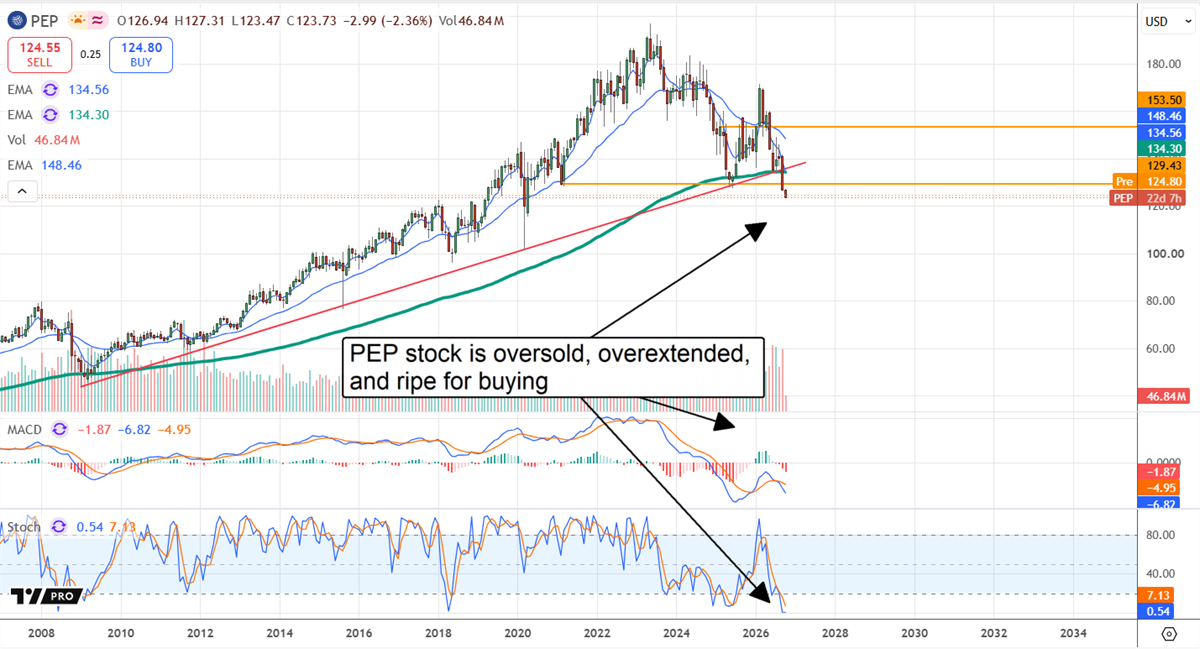
I don't treat it as a core holding that gets the same allocation as a broad index fund. It works better as a stabilizer within a portfolio, maybe five to ten percent depending on your overall risk tolerance. The reason is straightforward: consumer staples stocks like PEP tend to underperform during strong bull markets and outperform during corrections. That behavior is predictable enough that you can plan around it rather than being surprised by it. When I entered a position recently, I waited for the stock to pull back roughly twelve percent from its recent high. The pullback was driven by concerns about volume softness in North America, which turned out to be a temporary factor rather than a structural problem. Buying into that dip gave me a better entry point than chasing the stock near its all-time highs. I do not recommend timing the market precisely. I am saying that in this case, the dip was real, the fundamentals were intact, and the subsequent recovery validated the patience.
Risks and Where the Thesis Breaks Down
The main risk is regulatory pressure on sugar and sodium content in products. Several markets have introduced sugar taxes or labeling requirements that increase compliance costs and may affect demand for certain SKUs. This is a slow-moving risk, not an overnight event, but it has been building for years and will continue to shape the product mix over the next decade. Another scenario where PEP underwhelms is during periods of strong economic growth when consumers trade up to premium products or shift spending toward experiences rather than packaged goods. The stock will still pay the dividend, but the capital appreciation component may lag behind the broader market significantly. If you are looking for high growth, PEP is the wrong stock. If you need income with moderate capital preservation and can tolerate underperformance during rallies, it fits the profile. There is no perfect stock, and Pep Stock is simply a tool that works well within a specific portfolio strategy.
Where to Track the Data
The official investor relations page for PepsiCo publishes earnings releases, SEC filings, and presentation decks. Bloomberg and Reuters provide real-time quotes and analyst consensus estimates. For dividend tracking, the's investor site lists historical dividend amounts and ex-dividend dates. I usually cross-reference the quarterly earnings call transcript with the SEC 10-Q filing because management sometimes emphasizes different metrics in each document, and reconciling both gives a clearer picture than relying on either one alone.